
The Complete Overview of Net Worth in American Households
The net worth of American households is a moving target, influenced by macroeconomic trends, policy shifts, and cultural attitudes toward savings and investment. While headlines often focus on the stock market’s performance or GDP growth, the reality for most families is far more granular: a mix of home equity, retirement accounts, and debt obligations that define their financial standing. The Federal Reserve’s triennial Survey of Consumer Finances remains the gold standard for tracking these metrics, but even its data points to a fragmented landscape. For example, the top 10% of households hold nearly 70% of all wealth, while the bottom 50% collectively own just 2.6%. This concentration isn’t static; it evolves with inflation, tax laws, and generational transfers of assets.
The pandemic era accelerated existing trends. Remote work boosted housing demand in suburban and rural areas, driving up home values and net worth for owners—but renters and lower-income families saw little relief. Meanwhile, the S&P 500’s surge lifted retirement portfolios for those with 401(k)s or IRAs, while younger workers with lighter investment holdings lagged behind. The result? A widening gap between those who could leverage asset appreciation and those trapped in cycles of debt or stagnant wages. Even as policymakers debate wealth redistribution or financial education programs, the underlying question persists: How do households accumulate—or lose—wealth over time, and what levers can shift the trajectory?
Historical Background and Evolution
The concept of household net worth as a measure of economic well-being gained prominence in the 1980s, as economists sought to quantify the assets and liabilities that defined middle-class stability. Before then, discussions centered on income alone, ignoring the cumulative effect of homeownership, inheritance, and investment returns. The Federal Reserve’s first comprehensive survey in 1989 revealed that the median net worth of white households was nearly six times that of Black households—a disparity that has persisted with only marginal improvement. The 2008 financial crisis further exposed these divides: while white households saw their net worth decline by 16%, Black households lost 31%, and Latinx households lost 28%, according to the Urban Institute. The crisis didn’t create the gap; it deepened it.
Post-crisis recovery was uneven. The stock market’s rebound benefited those with retirement accounts, while wage growth failed to keep pace with rising costs of living. The 2020s brought another inflection point: the COVID-19 pandemic and its economic fallout. Stimulus payments and expanded unemployment benefits provided temporary relief, but the long-term impact on net worth hinged on asset ownership. Homeowners with mortgages saw equity surge, while renters faced eviction risks and job instability. Meanwhile, student loan forbearance masked the debt burden that continues to suppress wealth-building for younger cohorts. Historical data suggests that without targeted interventions, these cycles of inequality will persist, with each generation inheriting—or failing to inherit—the financial advantages of the last.
Core Mechanisms: How It Works
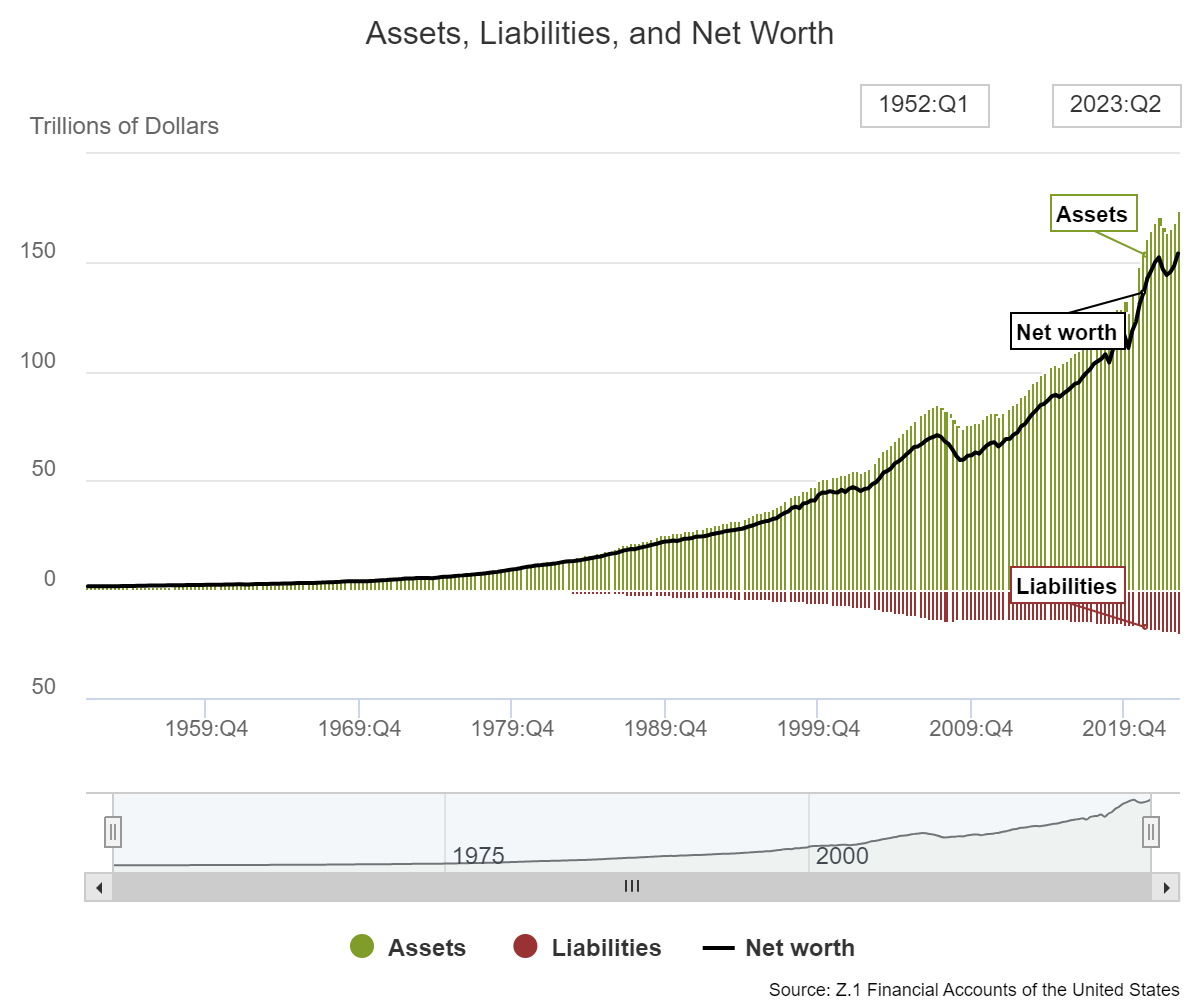
Net worth is the balance sheet of a household’s financial life: assets on one side, liabilities on the other. For most Americans, the largest asset is their primary residence, followed by retirement accounts like 401(k)s and IRAs. Liabilities typically include mortgages, student loans, credit card debt, and auto loans. The interplay between these components determines whether a household’s net worth grows, stagnates, or declines. For example, a homeowner with a paid-off mortgage and a diversified investment portfolio will see their net worth rise with market conditions, while a renter with high student debt may struggle to build equity even during economic expansions.
The mechanics of wealth accumulation are also tied to time and timing. Inheritance plays a disproportionate role: households that receive intergenerational transfers see their net worth jump by an average of 20%, according to the Brookings Institution. Meanwhile, those without family wealth must rely on savings rates, wage growth, and access to credit—factors that are heavily influenced by race, education, and geography. Even small differences in interest rates on mortgages or student loans can compound over decades, widening the gap between households that play by the rules and those left behind by systemic barriers.
Key Benefits and Crucial Impact
A strong net worth isn’t just a measure of financial security; it’s a buffer against economic shocks. Households with higher net worth are more likely to weather job loss, medical emergencies, or market downturns without falling into debt. They also have greater flexibility to invest in education, entrepreneurship, or home repairs—decisions that further compound their financial advantages. Conversely, low net worth correlates with higher stress levels, limited mobility, and reduced access to opportunities. The psychological toll of financial insecurity is well-documented: studies show that households with negative net worth report lower life satisfaction and higher rates of depression.
The impact extends beyond individuals. Communities with higher median net worth tend to have better schools, lower crime rates, and more stable local economies. Wealthier households contribute more to tax revenues, fund public services, and create demand for higher-paying jobs. Yet the benefits of net worth are unevenly distributed, reinforcing cycles of advantage and disadvantage. As economist Thomas Piketty has argued, the concentration of wealth in fewer hands distorts economic mobility, making it harder for future generations to climb the ladder.
"Net worth is not just about money—it’s about opportunity. The households that build wealth early have a head start that lasts lifetimes. Without addressing the barriers they face, we’re not just talking about economics; we’re talking about justice." — Rachel Schneider, Senior Economist, Urban Institute
Major Advantages
- Financial resilience: Households with higher net worth can absorb unexpected expenses (e.g., medical bills, car repairs) without relying on debt.
- Generational wealth transfer: Assets like homes and investments can be passed down, reducing the burden on future generations.
- Access to credit and opportunities: Strong net worth improves loan approval odds and unlocks higher-paying jobs or education.
- Retirement security: Those with substantial net worth are far more likely to retire comfortably, reducing reliance on Social Security.

Comparative Analysis
| Metric | White Households | Black Households |
|---|---|---|
| Median Net Worth (2022) | $188,200 | $24,100 |
| Homeownership Rate | 74% | 43% |
| Student Debt Burden | $30,000 (median) | $25,000 (median) |
Future Trends and Innovations
The next decade will test whether net worth in American households continues to diverge or begins to converge. On one hand, technological advancements—like robo-advisors and fintech platforms—could democratize wealth-building tools, making investing accessible to lower-income families. On the other, rising costs of housing, healthcare, and education may outpace wage growth, squeezing net worth for younger generations. Policy innovations, such as expanded child tax credits or student debt relief, could act as catalysts for change, but their effectiveness depends on political will and economic conditions.
Another wild card is the role of assets beyond traditional investments. Cryptocurrency, for instance, has introduced volatility but also potential upside for early adopters. Meanwhile, the gig economy’s rise means more households have irregular income streams, complicating net worth calculations. As automation reshapes labor markets, the link between employment stability and wealth accumulation may weaken, forcing households to adopt new strategies—like side hustles or alternative investments—to maintain financial security.
Conclusion
The net worth of American households is more than a statistical footnote; it’s a reflection of a society’s priorities and its failures. The data reveals not just economic trends but the persistent gaps that define opportunity in the U.S. Whether through policy reforms, financial education, or cultural shifts, addressing these disparities requires acknowledging the structural forces at play. For individuals, the message is clear: wealth isn’t built overnight, and the tools available to one household may be inaccessible to another. The challenge ahead is to bridge that divide—not just for equity’s sake, but for the stability of the economy itself.
The conversation about net worth isn’t about blaming individuals for their circumstances but about recognizing the systems that shape those circumstances. From inheritance patterns to access to credit, the mechanisms of wealth accumulation are deeply embedded in history. Moving forward, the question isn’t whether net worth will remain unequal—it’s how society will respond to that inequality.
Comprehensive FAQs
Q: How often is the net worth of American households updated?
The Federal Reserve’s Survey of Consumer Finances, the most comprehensive source, is conducted every three years. Supplemental data, like the Current Population Survey, provides annual snapshots but with less detail. For real-time trends, economists often rely on proxy metrics like home price indices or stock market performance.
Q: Does homeownership always increase net worth?
Not necessarily. While homeowners typically see their net worth rise over time due to equity gains, factors like mortgage debt, maintenance costs, or market downturns can offset these benefits. Renters, meanwhile, may allocate savings toward investments or emergency funds, potentially building wealth through other assets. The relationship between homeownership and net worth depends on local housing markets and individual financial strategies.
Q: How does student debt affect net worth?
Student loans act as a wealth drain by delaying major milestones like homeownership and retirement savings. Borrowers with high debt loads often have lower credit scores, limiting access to mortgages or business loans. Over time, this can reduce a household’s net worth by tens—or hundreds—of thousands of dollars compared to peers without student debt.
Q: Are there racial disparities in net worth beyond homeownership?
Yes. Beyond housing, racial gaps appear in retirement accounts, business ownership, and inheritance. For example, white households are more likely to receive intergenerational wealth transfers, while Black and Latinx households face higher rates of predatory lending and lower access to capital for entrepreneurship. These disparities compound over generations, making it harder to close the wealth gap through income alone.
Q: Can financial literacy programs close the net worth gap?
Financial education is necessary but insufficient on its own. While programs can improve budgeting and investing habits, they don’t address systemic barriers like discriminatory lending practices or wage discrimination. Effective change requires combining literacy initiatives with policy reforms, such as expanding access to credit, increasing minimum wages, and reforming tax structures that favor asset accumulation.
Q: How does inflation impact net worth?
Inflation erodes the purchasing power of cash assets (like savings accounts) and fixed-income investments (e.g., bonds). However, households with diversified portfolios—including stocks, real estate, or commodities—often see their net worth grow during inflationary periods. The key is asset allocation: those who can shift wealth into appreciating assets tend to fare better than those stuck in low-yield holdings.
Q: What role do inheritances play in net worth inequality?
Inheritances are a major driver of wealth inequality. According to the Federal Reserve, the top 10% of households receive about 70% of all intergenerational transfers. For many middle- and upper-class families, inheritances provide the down payment for a home or a financial cushion in retirement. Without these transfers, wealth accumulation becomes far more difficult, widening the gap between those who inherit advantage and those who don’t.
