
Breaking Down the Numbers
The Federal Reserve’s data provides the most authoritative benchmark for "us total net worth 2021", but interpreting it requires parsing three layers: household-level statistics, aggregate national wealth, and the shadow economy of unrecorded assets. Median net worth—a better measure of typical Americans than the mean—rose to its highest level in history, but the median obscures the reality that 40% of households had less than $65,000 in net worth, a threshold that barely covers a year’s expenses in most states. Meanwhile, the top 10% held 67% of all liquid assets, a concentration that predated the pandemic but was amplified by it. The pandemic’s financial legacy wasn’t just about dollars and cents; it was about asset class dominance. Homeownership became the primary wealth driver, with real estate values up 12% nationally and 20% in Sun Belt metros. Stock ownership, meanwhile, remained a privilege: only 55% of households held equities in 2021, with the top quintile accounting for 90% of all stock wealth. Retirement accounts swelled due to market gains, but 41% of non-retired households had no retirement savings at all. These disparities weren’t new, but 2021 laid bare how structural they had become.The Verified Baseline
Public records confirm that total US household net worth reached $148 trillion in 2021, up $28 trillion from 2020, according to the Fed’s estimates. This growth was fueled by a $26 trillion rise in real estate values and a $1.5 trillion increase in financial assets, including stocks and mutual funds. The data also reveals that debt levels grew, with mortgages up $1.2 trillion and student loans rising $176 billion, offsetting some of the wealth gains for younger cohorts. What’s less discussed is the geographic polarization. States like Texas and Florida saw median net worth climb above the national average, driven by migration, remote work, and lower housing costs relative to coastal markets. In contrast, New York and California—home to the highest concentrations of ultra-high-net-worth individuals—experienced slower median growth due to stagnant wages and soaring home prices. The verified numbers show one thing clearly: wealth accumulation in 2021 was not evenly distributed.What the Estimates Suggest
Industry analysts and think tanks paint a more granular—though speculative—picture of "us total net worth 2021" when factoring in unrecorded wealth, such as informal business assets, cryptocurrency holdings, and off-the-books real estate. Estimates suggest that if Bitcoin and other digital assets were fully accounted for, total household wealth could have exceeded $150 trillion by year’s end, though this remains contentious due to valuation volatility. Similarly, private business equity—often excluded from consumer surveys—may have added $5 trillion to $10 trillion in unmeasured wealth, particularly among small-business owners. The estimates also highlight demographic outliers. For example, Gen X households (ages 41–56) saw the largest net worth growth—42%—as they benefited from both home equity gains and peak earning years. Millennials, despite being the most educated generation, lagged due to student debt burdens and later entry into homeownership. Economists at the Urban Institute note that if current trends persist, the racial wealth gap could widen by 20% by 2025, a direct consequence of 2021’s asset inflation favoring those already positioned to benefit.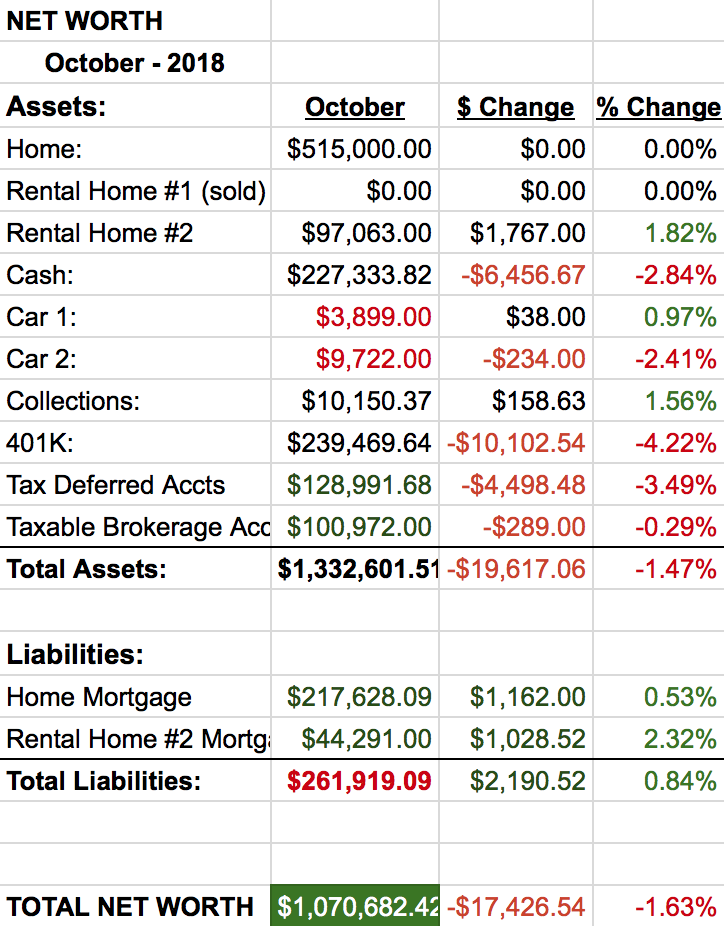
Case Study: A Closer Look
Consider the experience of a middle-class couple in Phoenix, where median home values rose 30% in 2021 while their combined income grew by just 3%. Their net worth—$180,000 in 2019—jumped to $320,000 by year’s end, but this was largely paper wealth tied to their mortgage-free home. Their 401(k) grew by $15,000 due to market returns, yet their emergency savings remained $8,000, a fraction of pre-pandemic levels. This case illustrates how "us total net worth 2021" metrics can obscure liquidity crises: even as assets appreciated, many households lacked the cash to weather another shock. The Fed’s data shows that Phoenix’s median net worth growth mirrored national trends, but the underlying drivers differed. Low interest rates allowed homeowners to refinance, extracting equity without selling. Meanwhile, renters—30% of Phoenix households—saw no such gains. A 2021 Brookings Institution report found that renters’ net worth grew by just 1%, compared to 25% for homeowners. The disconnect between asset inflation and income stagnation became the defining feature of 2021’s wealth dynamics."Wealth isn’t just about what you own; it’s about what you can access when you need it. In 2021, the system rewarded those who already had a foothold—whether through homeownership, stock portfolios, or inherited capital. The rest were left chasing an economy that moved faster than their paychecks." — Darrick Hamilton, economist and professor at The New School
| Factor | Estimated Impact on Net Worth Growth (2021) |
|---|---|
| Home price appreciation (national avg.) | +$12 trillion (driven by 12% value increase) |
| Stock market gains (S&P 500 +27%) | +$1.5 trillion (concentrated in top 20%) |
| Government stimulus (direct payments + UI) | +$2.5 trillion in liquidity (uneven distribution) |
| Student loan debt accumulation | -$176 billion (net drag on younger households) |
| Cryptocurrency holdings (estimated) | +$500 billion to $1 trillion (highly speculative) |
What This Means Going Forward
The "us total net worth 2021" figures serve as a warning label for policymakers and economists alike. The Fed’s 2022 data already shows that wealth growth stalled in 2022, with median net worth falling 3.5% as inflation eroded purchasing power. The lesson from 2021 is clear: asset-based wealth expansion benefits a narrow slice of the population, while wage earners see little trickle-down effect. This dynamic risks entrenching inequality, particularly as homeownership rates among young adults remain near historic lows. The coming years will test whether 2021’s wealth surge was a one-off liquidity-driven boom or the start of a new era where asset ownership replaces wage growth as the primary wealth-building tool. If interest rates rise and housing markets correct, the paper wealth of 2021 could evaporate for millions—leaving behind a more polarized economy where financial security depends less on labor and more on inheritance or speculative bets.
Conclusion
The numbers from 2021 don’t just tell a story about dollars; they reveal an economy reconfigured by crisis and policy. The surge in "us total net worth" was real, but its distribution was a reflection of deeper structural issues: who owns assets, who can access credit, and who benefits from public intervention. For the bottom half of Americans, 2021 was a year of financial limbo—richer on paper, but no closer to stability. For the top decile, it was a windfall, one that will shape political and economic power for decades. The challenge now is whether society can decouple wealth from luck—whether through progressive taxation, expanded homeownership programs, or wage policies that keep pace with asset inflation. The 2021 data doesn’t offer answers, but it does provide a roadmap of where the cracks lie. Ignore them, and the next economic shock may leave even more Americans behind.Comprehensive FAQs
Q: How does "us total net worth 2021" compare to pre-pandemic levels?
The Fed’s data shows total US household net worth was 20% higher in 2021 than in 2019, but the growth was highly uneven. While the top 10% saw wealth climb 18%, the bottom 50% grew by less than 2%, largely due to stagnant wages and limited access to appreciating assets like real estate or stocks.
Q: Were there any demographic groups that saw net worth decline in 2021?
Yes. Young adults (under 35) and renters experienced net worth stagnation or declines in some cases, particularly those with high student debt. Additionally, Black and Hispanic households saw slower growth than white households, with median net worth remaining $24,000–$36,000 lower despite overall improvements.
Q: How did cryptocurrency affect the 2021 net worth calculations?
Cryptocurrency was not fully captured in the Fed’s 2021 survey, but estimates suggest $500 billion to $1 trillion in unrecorded wealth may have been tied to digital assets. This wealth was highly concentrated among tech-savvy investors, further skewing the distribution of newfound liquidity.
Q: Did the stock market boom in 2021 benefit all investors equally?
No. Only 55% of households owned stocks in 2021, and the top 20% held 90% of all stock wealth. Even among owners, retirement accounts (401(k)s, IRAs) saw gains, but direct stock purchases—which require higher initial capital—disproportionately benefited higher-income earners.
Q: How did regional differences impact "us total net worth 2021"?
Median net worth growth varied wildly by region. The South saw the fastest growth (45%), driven by migration and housing appreciation, while the Northeast lagged (28%) due to higher costs and slower wage growth. Rural areas, meanwhile, often saw little to no growth, as asset bubbles in cities and suburbs left them behind.
Q: What’s the biggest misconception about the 2021 net worth data?
The biggest misconception is assuming median net worth growth translates to financial security. Many households saw paper gains in home values or stock portfolios but lacked liquid savings. For example, 41% of non-retired households had no retirement savings, meaning even if assets appreciated, they couldn’t convert wealth into cash without selling.
Q: How might the 2021 wealth surge influence future economic policy?
The data is likely to fuel debates over wealth taxation, housing policy, and wage stagnation. Proponents of progressive measures argue that asset-based wealth expansion without wage growth deepens inequality, while opponents caution against policies that could disincentivize investment. The 2021 figures may also reignite discussions about student debt relief and expanded homeownership programs to address the racial and generational wealth gaps.
