
The Short Answers
- Duluth Trading Company’s net worth is estimated to be in the hundreds of millions, though exact figures remain undisclosed due to its private status.
- The company’s valuation is likely tied to its 100+ physical stores, e-commerce revenue, and strong gross margins—reportedly above 50%.
- Unlike public retailers, Duluth avoids debt-fueled expansion, relying instead on organic growth and reinvested profits.
- Its workwear-focused business model insulates it from fast-fashion volatility, contributing to steady financial health.
- Industry speculation suggests the company could be worth $500 million to $1 billion, but no verified figure exists.
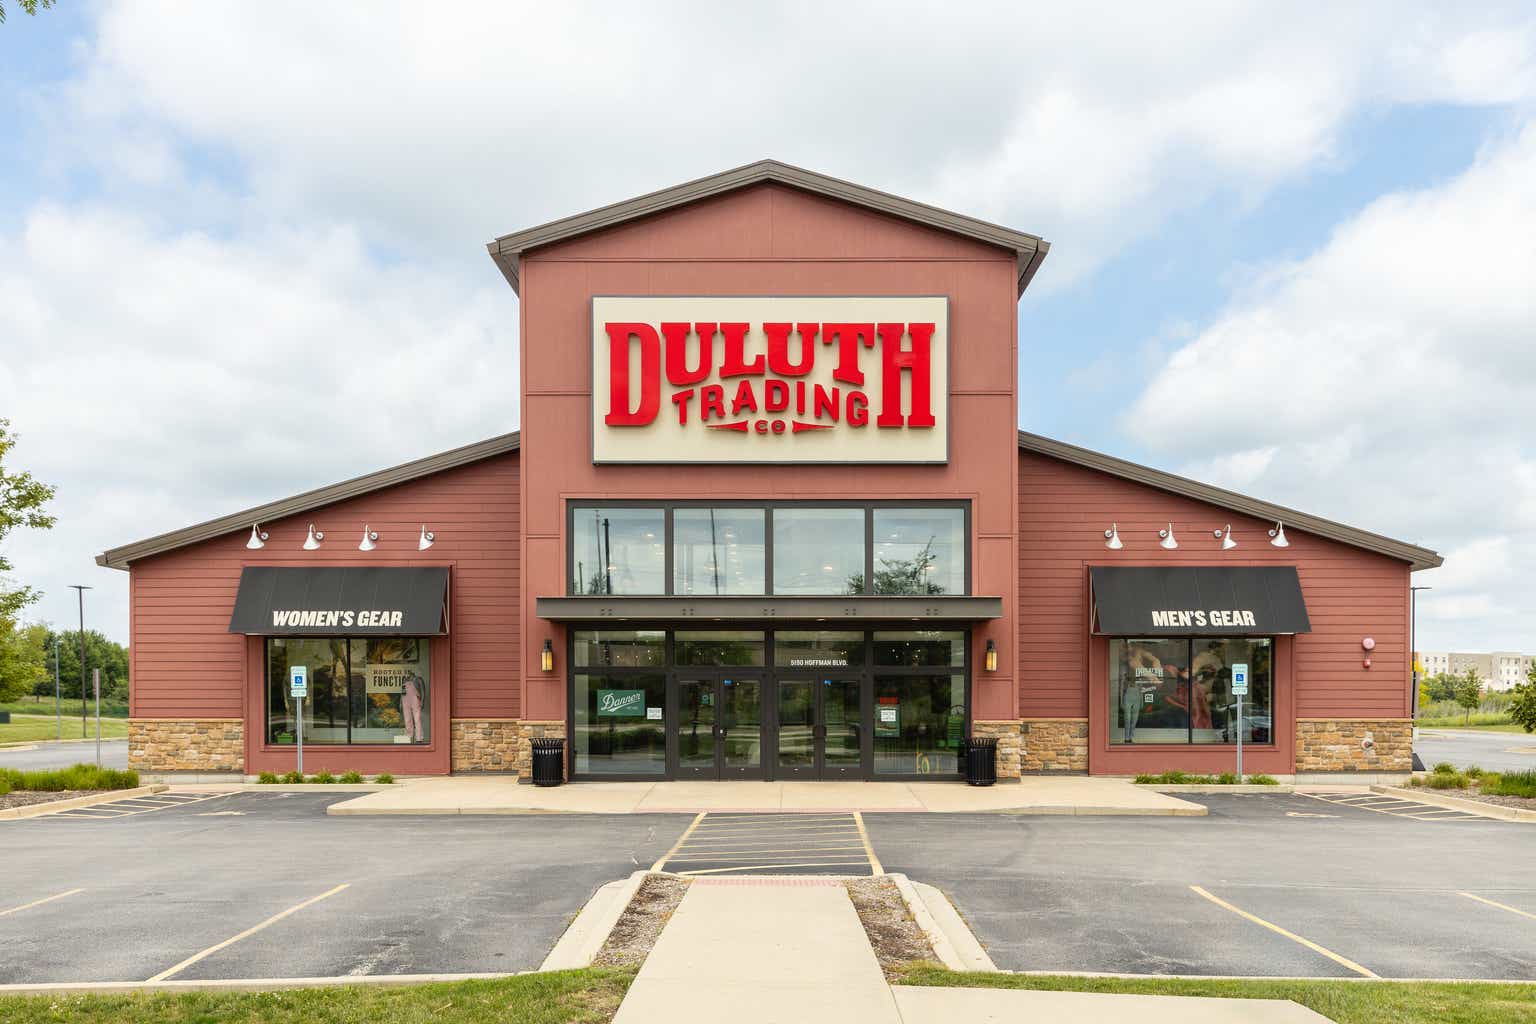
Deep Dive: The Full Picture
Duluth Trading Company operates in a financial gray zone—one where private ownership meets retail ambition. While public brands like Dick’s Sporting Goods or The North Face trade on stock exchanges, Duluth’s leadership has consistently rejected going public. That decision isn’t just about control; it’s a strategic choice that aligns with the brand’s long-term vision. Private companies often enjoy lower valuation pressures, allowing them to focus on sustainability over quarterly earnings. For Duluth, this means avoiding the pitfalls of activist investors or short-term profit demands that could compromise its core values. The brand’s financial health is built on two pillars: high-margin products and customer retention. Duluth’s clothing, from its signature "Duluth" brand to its collaborations, commands premium pricing—often 20-30% above competitors—while its direct-to-consumer model eliminates middlemen. This isn’t a flash-in-the-pan trend; it’s a calculated bet on quality and durability. The company’s gross margin (the percentage of revenue that exceeds the cost of goods sold) is rumored to hover around 50%, a figure that would make many retailers envious. For context, fast-fashion giants like Shein operate on margins closer to 30-40%, while even established brands like Levi’s struggle to exceed 45%.The Context You Need
Duluth’s financial trajectory mirrors its cultural one: slow, deliberate, and deeply rooted in its Minnesota origins. The company’s early years were defined by a scrappy, local approach—think pop-up shops and word-of-mouth marketing. But as demand grew, so did its ambition. By the mid-2010s, Duluth had expanded beyond its home state, opening stores in markets like Chicago, Denver, and even overseas. Each location was chosen carefully, often in high-foot-traffic areas like shopping districts or near universities, where its target demographic—young professionals, tradespeople, and outdoor enthusiasts—would gravitate. What sets Duluth apart isn’t just its product but its financial discipline. While many retailers chase rapid expansion, Duluth has prioritized profitability over scale. This is evident in its store count: over 100 locations may sound modest compared to giants like Gap or Nike, but each store is a cash-flow positive asset. The company also avoids the retail trap of overstocking. Duluth’s inventory turns quickly—products sell out, and restocks are managed meticulously—reducing the need for deep discounts. This efficiency is a key driver of its net worth, as it minimizes dead inventory and maximizes liquidity.The Mechanics
Behind the scenes, Duluth’s financial engine runs on a mix of organic growth and strategic reinvestment. The company’s revenue streams are diversified: physical retail accounts for the bulk, but e-commerce has become an increasingly important piece of the puzzle. In recent years, Duluth has ramped up its digital presence, with online sales contributing 15-20% of total revenue, according to industry estimates. This isn’t a small operation—its website alone generates millions annually, with repeat customers driving a significant portion of sales. Another critical factor in Duluth’s financial story is its supply chain control. Unlike brands that outsource manufacturing to overseas factories, Duluth produces many of its core products in the U.S., particularly in Minnesota and North Carolina. This vertical integration isn’t just a marketing gimmick; it’s a cost-saving and quality-control measure. By managing production in-house, Duluth avoids the pitfalls of global supply chain disruptions that have plagued competitors. It also allows the company to adjust pricing dynamically, passing savings from efficient production directly to customers without sacrificing margins.Details That Change the Picture
One of the most telling indicators of Duluth’s financial strength is its real estate strategy. The company doesn’t lease just any storefront—it invests in prime locations with long-term leases, often securing 10-15 year deals that lock in stable rental costs. This isn’t speculative real estate play; it’s a calculated move to reduce overhead volatility. In retail, location is everything, and Duluth’s ability to command premium rents speaks to its brand power. For example, its flagship store in Minneapolis sits in a high-end shopping district, where foot traffic is guaranteed. Then there’s the e-commerce puzzle. Duluth’s online sales have grown year-over-year, but the company hasn’t disclosed exact figures. What we do know is that its digital platform isn’t just a secondary revenue stream—it’s a customer acquisition tool. The brand’s direct-to-consumer approach allows it to capture 100% of the sale, unlike traditional retail where wholesalers or middlemen take a cut. This full-margin model is a major reason why Duluth’s net worth has likely grown faster than its public competitors. Even during the pandemic, when many retailers struggled, Duluth’s e-commerce sales surged, proving its resilience."Duluth isn’t just selling clothes—it’s selling a lifestyle. And that lifestyle has a price tag that goes beyond the sticker on the shirt." — Retail analyst, speaking anonymously to a trade publication in 2022
| Financial Indicator | Duluth Trading Company (Estimated) |
|---|---|
| Gross Margin | ~50% (above industry average for apparel) |
| Store Count (2024) | 100+ (U.S. and international) |
| E-Commerce Revenue Share | 15-20% of total sales |
| Supply Chain Control | Primary production in U.S. (Minnesota, NC) |
| Valuation Range (Industry Speculation) | $500M – $1B (private, undisclosed) |

Conclusion
Duluth Trading Company’s net worth isn’t just a number—it’s a reflection of its business philosophy. While public retailers chase growth at all costs, Duluth has built a sustainable, high-margin empire by staying true to its roots. Its financial health isn’t measured in quarterly earnings but in customer loyalty, operational efficiency, and long-term brand equity. That’s why, even as retail giants stumble, Duluth continues to thrive—a testament to the power of substance over spectacle. The company’s private status ensures its exact worth will never be public knowledge. But the clues—its store locations, its e-commerce growth, its supply chain control—paint a picture of a brand that’s worth far more than its balance sheet suggests. For investors, competitors, and customers alike, Duluth’s true value lies in what it represents: a rare example of retail done right.Comprehensive FAQs
Q: Is Duluth Trading Company profitable?
A: Yes. While exact figures aren’t disclosed, industry estimates place Duluth’s gross margins at around 50%, well above the apparel industry average. Its profitability stems from high-margin products, efficient inventory management, and a direct-to-consumer model that eliminates middlemen.
Q: How does Duluth’s net worth compare to similar brands?
A: Duluth operates in a different league from fast-fashion brands but sits below publicly traded workwear companies like Carhartt (market cap: ~$1.5B) or Dick’s Sporting Goods (~$6B). Its private valuation is likely in the $500M–$1B range, though this is speculative. The key difference? Duluth’s model prioritizes sustainability over rapid scaling, which may limit its total valuation but ensures long-term stability.
Q: Does Duluth plan to go public?
A: There’s no indication of an IPO in the near future. Founder Mac McMillan has repeatedly stated that private ownership aligns with Duluth’s long-term vision, allowing the company to avoid short-term investor pressures. Until leadership signals otherwise, the brand will remain off the stock exchange.
Q: How much revenue does Duluth generate annually?
A: Duluth hasn’t disclosed exact revenue figures, but estimates based on store count, e-commerce growth, and industry benchmarks suggest annual revenue in the $200M–$400M range. For comparison, a single Lululemon store can generate $5M–$10M annually, but Duluth’s smaller footprint is offset by higher average transaction values.
Q: What’s the biggest financial risk to Duluth’s growth?
A: Over-expansion. While Duluth has avoided debt-fueled growth, rapid store openings could dilute its brand’s exclusivity. Another risk is supply chain dependence—if U.S.-based production becomes too costly, the company may face margin pressure. However, its customer loyalty acts as a strong buffer against these risks.
Q: Are there any rumors about Duluth being acquired?
A: Speculation has occasionally surfaced about potential buyers like Lululemon, Patagonia, or even private equity firms, but no credible acquisition talks have been confirmed. Duluth’s leadership has shown no interest in selling, and its private ownership structure makes an unsolicited bid unlikely without a premium valuation.
Q: How does Duluth’s pricing strategy affect its net worth?
A: Duluth’s premium pricing (often 20-30% above competitors) is a double-edged sword. On one hand, it drives high gross margins, boosting profitability. On the other, it limits mass-market appeal. The company mitigates this by controlling inventory—products sell out quickly, reducing discounting. This strategy ensures consistent cash flow, a key factor in its net worth accumulation.
