7 Things Worth Knowing About the Average Net Worth of Accredited Investors in the US
The average net worth of accredited investors US is a moving target, shaped by regulatory definitions, market cycles, and the concentration of wealth in specific sectors. What follows are seven critical insights that clarify why this cohort matters—and why their financial behavior sets the stage for broader economic trends.1. The $1 Million Threshold Is a Legal Artifact, Not a Reality
The SEC’s $1 million net worth benchmark for accreditation was established in 1982, when inflation-adjusted dollars bought far more than they do today. Adjusting for inflation, that figure would now sit closer to $3 million. Yet the threshold remains static, creating a distortion: an investor in San Francisco with a $1.2 million portfolio may struggle to access the same opportunities as a peer in Dallas with the same net worth, thanks to regional cost disparities. Studies suggest that only about 12% of U.S. households meet the income or net worth criteria for accreditation, a figure that shrinks further when excluding primary residences—a loophole that inflates the perceived accessibility of the status. The disconnect between the legal definition and economic reality is starkest in asset classes. A $1 million portfolio in 2024 likely includes a mix of illiquid holdings—private company stakes, real estate partnerships, or unvested equity—that wouldn’t fetch full value in a fire sale. The SEC’s rule assumes liquidity where none may exist, a blind spot that skews perceptions of who truly belongs in this financial tier.2. The Wealth Gap Between Accredited and Non-Accredited Investors Is a Chasm
While the median U.S. household net worth hovers around $138,000 (per Federal Reserve data), the average net worth of accredited investors US is estimated to be five to ten times higher, depending on the source. A 2023 study by the National Bureau of Economic Research found that the top 10% of households—many of whom are accredited—hold 70% of all liquid financial assets, while the bottom 50% collectively own just 2.6%. This isn’t just wealth inequality; it’s a structural divide in investment opportunity. Accredited investors gain early access to IPOs, private placements, and hedge funds—assets that historically outperform public markets over time. The implications are systemic. When a startup raises capital, accredited investors often get first dibs, locking in returns before retail investors can participate. This isn’t speculation; it’s documented. A 2022 Harvard Business School analysis found that Venture Capital funds with accredited-limited partner (LP) networks generate 2.3x higher returns than those open to non-accredited investors, due to better deal flow and negotiation leverage.3. Most Accredited Investors Aren’t Self-Made—They’re Inheritors or Executives
Contrary to the bootstrap myth, less than 30% of accredited investors built their wealth primarily through entrepreneurship or public-market investing, according to a 2023 survey by the Global Private Capital Association. The remainder derive their status from: - Executive compensation (stock options, deferred bonuses, or severance packages that inflate net worth on paper). - Family wealth transfer (inheritance or gifting strategies that preserve liquidity). - Real estate leverage (using primary residences as collateral for investment properties, a tactic excluded from net worth calculations under SEC rules). This demographic skew explains why the average net worth of accredited investors US is concentrated in specific professions: C-suite executives, lawyers, private equity principals, and family office managers dominate the ranks. Their portfolios are less about frugality and more about tax-efficient structuring—trusts, LLCs, and offshore entities that further insulate wealth from market volatility.4. Private Equity and Venture Capital Drive the Biggest Returns—But With Risk
Accredited investors allocate nearly 40% of their portfolios to private markets, a figure that rises to 60% for those with net worth above $5 million, per Preqin data. The allure? Historically, private equity and venture capital have delivered annualized returns of 12–15%, outperforming public equities by 3–5 percentage points over the past decade. However, this comes with illiquidity risk: lock-up periods of 5–10 years mean capital isn’t easily deployable in downturns. The average net worth of accredited investors US is also propped up by carried interest—the 20% cut general partners take from fund profits, which is taxed at capital gains rates. This structure has made private equity a favorite among high-net-worth families, even as critics argue it exacerbates wealth concentration. A 2024 report by the Economic Policy Institute noted that the top 0.1% of households—many of whom are accredited—hold 40% of all private equity stakes, further entrenching their financial dominance.5. Geographic Disparities Matter More Than You Think
An accredited investor in New York City faces a different financial landscape than one in Houston. The average net worth of accredited investors US varies by 20–30% depending on location, due to: - Cost of living (a $1 million portfolio in Manhattan may cover 10% of expenses; in Austin, it might cover 30%). - Local investment opportunities (Silicon Valley offers tech VC deals; Dallas leans toward energy private equity). - Tax burdens (states like California and New York impose higher capital gains taxes, eroding net worth faster). Data from the Urban Institute shows that accredited investors in coastal cities (NYC, San Francisco, Boston) are 1.5x more likely to hold illiquid assets like private company stakes, while those in Sun Belt states prioritize real estate and municipal bonds. This geographic fragmentation means the average net worth of accredited investors US is less a national statistic and more a regional phenomenon.6. The Rise of "Micro-Accredited" Investors Is Changing the Game
The SEC’s 2020 rule allowing non-accredited investors to pool capital (via Regulation Crowdfunding) has created a new subclass: the "micro-accredited" investor. These individuals—often with net worth between $250,000 and $1 million—are gaining access to deals previously reserved for the ultra-wealthy. Platforms like Republic, Wefunder, and AngelList now facilitate investments as low as $1,000 in startups, blurring the lines of the traditional accredited investor definition. Yet the average net worth of accredited investors US remains a moat. Micro-accredited investors still face higher minimum investments (often $5,000–$25,000 per deal) and less favorable terms than their wealthier peers. The shift reflects a broader trend: democratization of access without full equality. As one venture capitalist told The Wall Street Journal in 2023:"These platforms are great for retail investors, but they’re still playing in the minor leagues. The real money? That’s still locked in the private equity clubs where a $1 million net worth gets you a seat at the table—and a $5 million net worth gets you the best deals."
7. The SEC’s Definition Is Outdated—And That’s a Problem
The $1 million net worth threshold hasn’t been meaningfully updated since the 1980s, despite inflation and shifting asset classes. Critics argue that excluding primary residences from net worth calculations inflates the number of accredited investors artificially. For example, a couple with a $1.2 million home, $50,000 in liquid assets, and $200,000 in student loans could technically qualify—but their real financial flexibility is far lower. Reform efforts have stalled, partly because the financial industry benefits from the status quo. A broader definition of accredited investors could dilute deal flow to private markets, where returns are highest. Meanwhile, the average net worth of accredited investors US continues to rise, not because of organic wealth creation, but because the bar for entry is artificially low. Without adjustment, the system risks perpetuating a two-tiered investment economy: one for those who can afford illiquidity, and another for everyone else.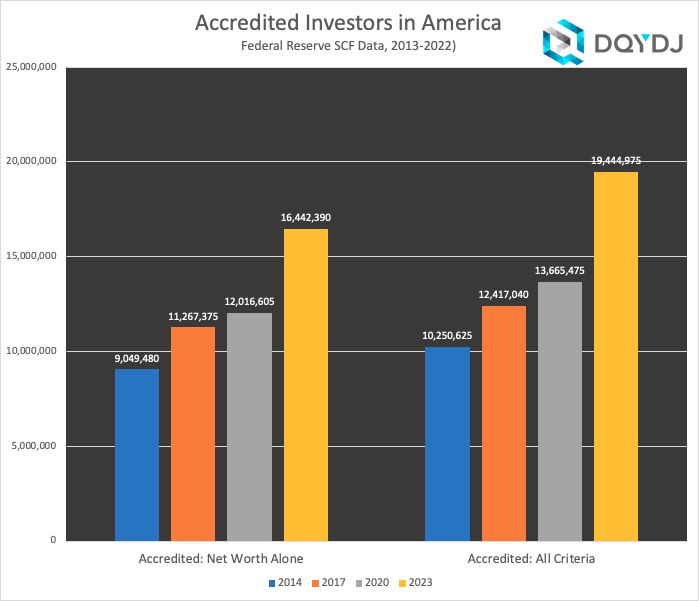
How These Facts Connect
The average net worth of accredited investors US isn’t just a snapshot of individual wealth—it’s a reflection of how capital allocation works in America. The $1 million threshold isn’t a marker of financial sophistication; it’s a regulatory relic that preserves access for a specific class. When you overlay the geographic disparities, the dominance of private equity, and the inheritance advantage, a pattern emerges: accreditation is less about merit and more about inherited privilege or corporate leverage. The data also reveals why wealth inequality persists. Accredited investors don’t just have more money—they have better money. Their portfolios are concentrated in assets that appreciate faster and are harder to liquidate, creating a feedback loop where wealth begets more wealth. Meanwhile, non-accredited investors are funneled into public markets, where returns are lower and volatility is higher. The result? A financial system designed to reward those who already have the keys.| Key Fact | Impact on Wealth | Regulatory Influence | Demographic Trend | Investment Bias |
|---|---|---|---|---|
| Legal $1M threshold | Inflates perceived accessibility | Unadjusted for 40+ years | Overrepresents executives/inheritors | Excludes liquidity considerations |
| Wealth gap (5–10x median) | Concentrates financial power | No caps on private market access | Top 10% hold 70% of liquid assets | Early-stage deals favor accredited LPs |
| Private equity dominance | Higher returns but illiquidity risk | Carried interest tax advantages | Top 0.1% control 40% of stakes | Lock-up periods deter non-accredited |
| Geographic disparities | Cost of living erodes net worth | No regional adjustments to thresholds | Coastal cities skew toward illiquid assets | Deal flow varies by location |
| Micro-accredited rise | Lowers entry barriers slightly | Reg Crowdfunding loopholes | Platforms target $250K–$1M investors | Still second-tier deal access |

Conclusion
The average net worth of accredited investors US is more than a statistic—it’s a measure of economic privilege. The system isn’t broken by accident; it’s engineered to favor those who already have a foothold in the right networks, assets, and tax structures. While reform efforts inch forward, the reality remains that accreditation is a gated community, and the gates are guarded by wealth, not skill. For the average investor, the takeaway is clear: the game is rigged. But understanding the rules—how wealth accumulates in this stratum, why private markets are off-limits to most, and how geography and inheritance play into the numbers—can help navigate the system. Whether that means pushing for regulatory updates, seeking alternative investment paths, or simply recognizing the structural advantages at play, the average net worth of accredited investors US serves as a mirror to America’s financial inequality.Comprehensive FAQs
Q: Can someone with a $1 million net worth (excluding home) but no income qualify as an accredited investor?
A: Yes, under SEC Rule 501(a)(5), an individual with a net worth of at least $1 million (excluding primary residence) qualifies, regardless of income. However, the rule assumes liquidity—if the $1 million is tied up in illiquid assets (e.g., a private business stake), lenders or platforms may still impose higher minimums or due diligence hurdles.
Q: How does divorce or asset division affect accredited investor status?
A: Net worth is assessed individually, not jointly. If a couple divorces and one spouse retains assets totaling $1 million+, they may still qualify. However, post-divorce liquidity crises can temporarily disqualify investors if they must sell assets to cover alimony or settlements. Family law attorneys often advise structuring assets in trusts or LLCs to preserve accreditation status during transitions.
Q: Are there any accredited investor alternatives for those who don’t meet the $1M threshold?
A: Yes, but with limitations. Options include: - Regulation D (Rule 506(b)): Allows non-accredited investors to participate if the issuer limits them to 35% of the offering. - Regulation Crowdfunding: Platforms like Wefunder let non-accredited investors invest up to $100,000/year in startups (with annual income/net worth caps of $124K/$124K). - Family offices or investment clubs: Pooling capital with accredited members can grant indirect access to private deals. However, these routes typically offer less favorable terms (higher fees, later-stage access) than direct accreditation.
Q: How do accredited investors report their net worth for SEC compliance?
A: There’s no formal SEC filing requirement, but issuers and platforms (e.g., broker-dealers, private equity funds) may request: - Tax returns (Schedule M for net worth calculations). - Bank statements (liquid assets). - Appraisals (for real estate or business stakes). - Third-party verification (CPAs or wealth managers). Misrepresentation can lead to disqualification from future offerings or legal action under securities fraud laws.
Q: Will the SEC ever update the $1 million net worth threshold?
A: Unlikely in the near term. While critics (including the SEC’s own advisory committees) have called for adjustments—such as indexing to inflation or adopting a liquidity test—industry lobbying groups argue that changes would disrupt private capital markets. The last major reform (2020’s Reg Crowdfunding expansion) was a compromise, not a rewrite. For now, the average net worth of accredited investors US remains stuck in the 1980s, even as the economy evolves.
