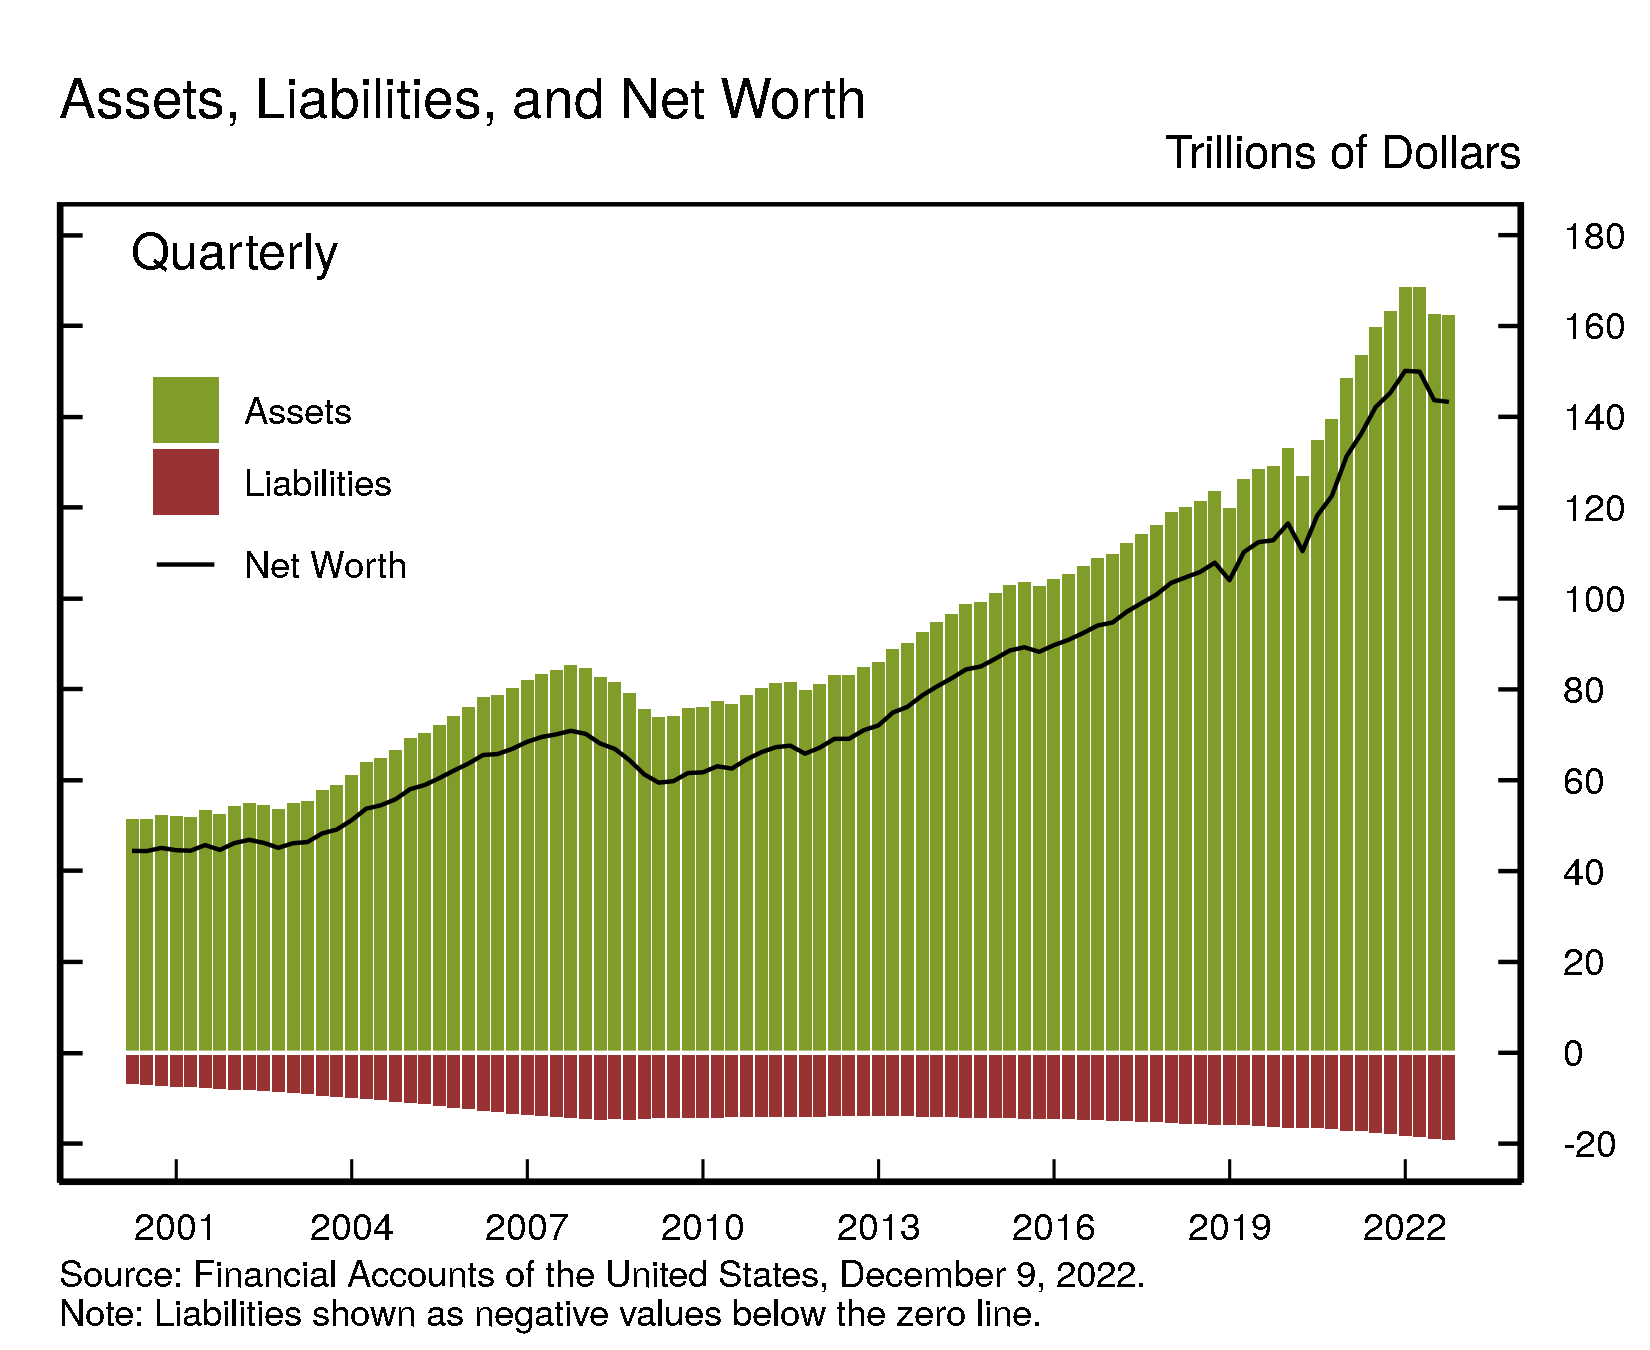
Where It All Began
The concept of tracking net worth and assets of households emerged alongside the rise of modern capitalism. Before the 20th century, wealth was largely tied to land ownership and physical possessions. A farmer’s net worth was the value of his crops, livestock, and tools—simple arithmetic. The Industrial Revolution changed that. Wages became regular, savings accounts appeared, and for the first time, people could accumulate wealth beyond immediate consumption. By the early 1900s, economists like Irving Fisher began formalizing the idea of net worth: assets minus liabilities. It was a way to quantify what people actually owned, not just what they earned. The Great Depression forced a reckoning. When banks failed and stocks collapsed, households realized their wealth accumulation strategies were fragile. Governments responded with social safety nets—Social Security, FDIC insurance—and a cultural shift toward stability over speculation. Post-war prosperity in the U.S. and Europe saw a surge in homeownership and pension plans, creating a middle-class asset base for households that lasted until the 1970s. But beneath the surface, inequality was already simmering. The top 1% held a disproportionate share of wealth, while the majority relied on wages and modest savings. The gap in net worth between households was widening, though most didn’t notice—until the numbers started to scream.The Early Signs
The cracks became visible in the 1980s. Deregulation of financial markets, the rise of credit cards, and the explosion of consumer debt changed how households built—and borrowed—wealth. The composition of household assets shifted from bricks and mortar to stocks, bonds, and leveraged real estate. For the first time, ordinary people could invest in markets, but they could also lose everything in a crash. The savings-and-loan crisis of the late 1980s exposed how fragile household financial resilience could be when banks took reckless risks with deposits. Meanwhile, the top tiers of society were diversifying into private equity, hedge funds, and offshore accounts—assets invisible to traditional wealth tracking. The net worth disparity between households wasn’t just about income anymore; it was about access to certain types of investments. A teacher might own a home and a 401(k), while a hedge fund manager held limited partnerships and art collections. The tools to measure wealth became outdated overnight.The Turning Point
The 2008 financial crisis was the earthquake. When the housing bubble burst, millions of households saw their primary asset—home equity—evaporate. Foreclosures became a national crisis, and for the first time, net worth and assets of households became a political football. The Federal Reserve’s response—quantitative easing—flooded markets with liquidity, but the benefits didn’t trickle down evenly. While the top 10% saw their wealth recover and grow, the bottom 50% remained stagnant. The wealth recovery trajectory of households became a stark divide: the rich got richer, the poor got debt. The crisis also exposed the fragility of modern household asset portfolios. Many families had poured everything into their homes, assuming real estate would always appreciate. When it didn’t, they were left with negative equity and no safety net. The lesson? Diversification wasn’t just for the wealthy—it was survival. Yet for millions, the damage was permanent. The median net worth of households in the U.S. didn’t return to pre-crisis levels until 2017, a decade later."Wealth isn’t just about money. It’s about control—control over your future, your options, your ability to absorb shocks. In 2008, we saw who had that control, and who didn’t." — Raghuram Rajan, Former Governor of the Reserve Bank of India

The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1970s–1980s | Rise of financialization: mutual funds, index investing, and the birth of the 401(k) system. The wealth accumulation strategies of households shifted from savings accounts to market-linked assets. Meanwhile, deregulation allowed banks to offer risky mortgages, setting the stage for future bubbles. |
| 1990s | Dot-com boom and bust. Tech wealth created new billionaires overnight, but many households lost savings in the crash. The asset allocation of middle-class households became more aggressive, chasing stock market gains. |
| 2000s | Housing bubble inflates. Subprime mortgages and adjustable-rate loans expanded household debt levels, treating homes as ATMs. When the bubble popped, millions faced foreclosure, wiping out decades of wealth. |
| 2010s–Present | Passive investing (ETFs, robo-advisors) democratizes wealth-building, but the net worth gap between households widens further. The rich invest in private markets; the middle class relies on stagnant wages and student loans. |
Lessons From the Journey
- Debt is the great equalizer—and divider. Credit cards, student loans, and mortgages can amplify wealth for some while crushing others. The leverage strategies of households now dictate long-term stability more than ever.
- Assets aren’t just numbers—they’re power. A home isn’t just shelter; it’s collateral. A retirement account isn’t just savings; it’s leverage for future opportunities. The control over assets within households determines mobility.
- Markets reward the connected. Information asymmetry means those with access to advisors, private deals, or insider knowledge outpace the rest. The wealth-building tools available to households are no longer equal.
- Policy shapes outcomes. Tax breaks for capital gains, student loan interest deductions, and inheritance rules tilt the playing field. The structural biases in household wealth accumulation are engineered, not accidental.
Where Things Stand Today
Today, the net worth and assets of households tell two stories. For the top 10%, wealth is a mosaic of liquid and illiquid assets: publicly traded stocks, private equity stakes, real estate portfolios, and alternative investments like wine or NFTs. Their wealth preservation strategies include trusts, offshore accounts, and professional management. The bottom 50%? Many still rely on home equity, retirement accounts, and—if they’re lucky—a side gig. The median net worth of households in the U.S. is around $130,000, but that masks a yawning chasm: the top 1% holds roughly 35% of all wealth. The pandemic accelerated existing trends. Stimulus checks and remote work boosted some household asset values (homes, stocks), while others faced job losses and medical debt. Cryptocurrency became a speculative asset for the young and wealthy, further polarizing wealth distribution among households. Meanwhile, student loan debt—now exceeding $1.7 trillion—acts as a wealth drain for younger generations, delaying homeownership and retirement savings. The biggest question isn’t how much people have, but how they got it. The paths to building household wealth have diverged into two lanes: those who inherit or invest early, and those who play catch-up with debt. The system is rigged, but the rules are clear.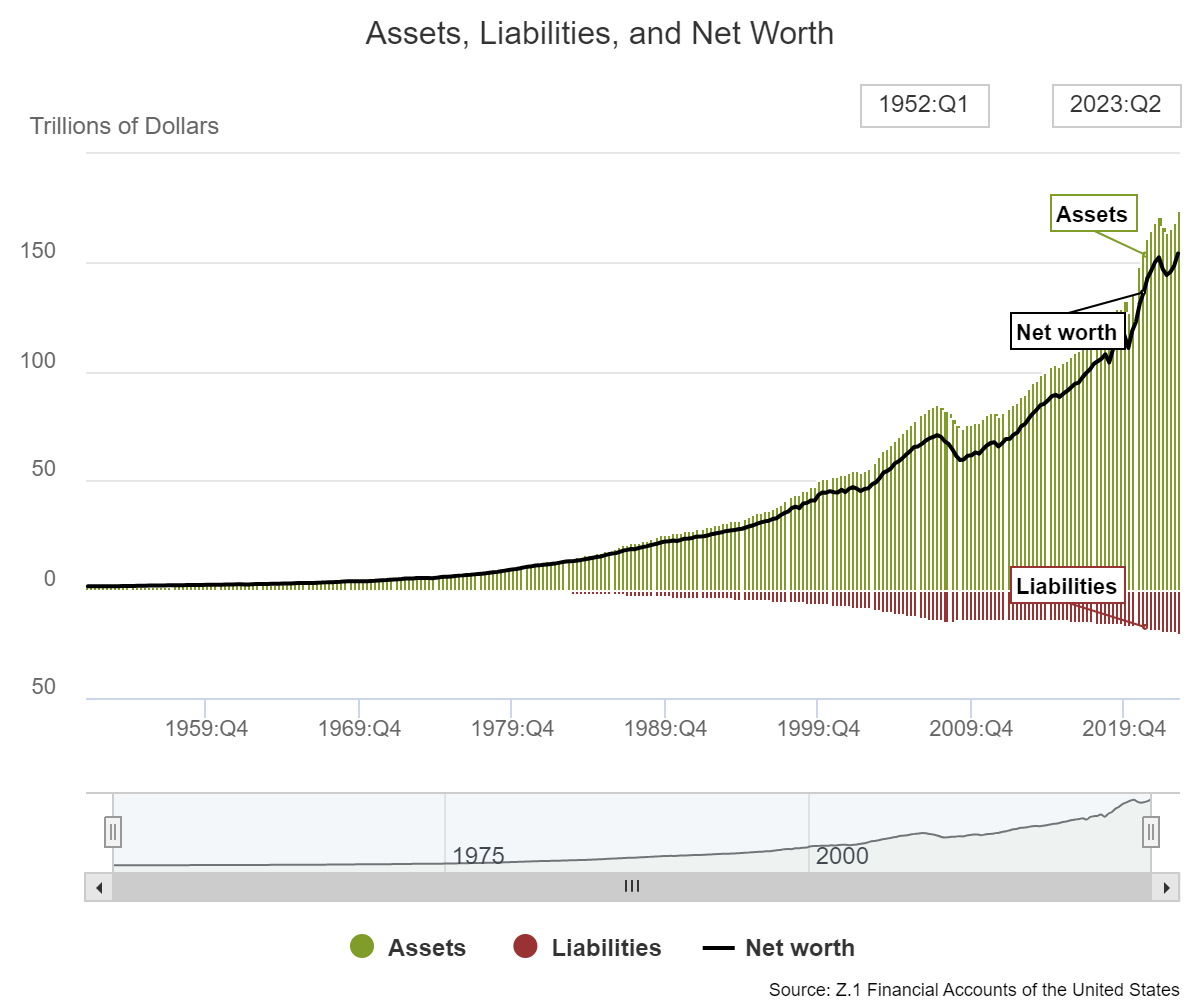
Conclusion
Understanding net worth and assets of households isn’t just about crunching numbers—it’s about uncovering the hidden rules of modern economics. Wealth isn’t static; it’s a living, breathing entity shaped by policy, luck, and access. The data shows one thing clearly: the accumulation of household assets has never been more unequal, and the tools to change that are in short supply. The conversation about wealth must move beyond "how much" to "how we got here." Because the numbers don’t lie, but the stories behind them do—and those stories are what really matter.Comprehensive FAQs
Q: How is net worth calculated for households?
Net worth is the total value of all assets (cash, real estate, investments, retirement accounts, etc.) minus total liabilities (mortgages, loans, credit card debt). For most households, the largest assets are home equity and retirement savings, while debt typically includes mortgages, student loans, and auto loans.
Q: Why does the gap in net worth between households keep growing?
The gap widens due to compounding factors: the rich invest in assets that appreciate faster (stocks, private equity), inherit wealth, and benefit from lower effective tax rates. Meanwhile, middle- and low-income households carry more debt (student loans, medical bills) and lack access to high-return investments. Policy also plays a role—capital gains taxes favor long-term investors, and homeownership subsidies disproportionately help those already wealthy.
Q: Are there safe ways for households to build wealth without risk?
No investment is entirely risk-free, but diversification and patience mitigate risk. Historically, low-cost index funds, consistent retirement contributions (401(k)s, IRAs), and homeownership (if affordable) have been stable wealth-builders. Avoiding high-fee products and speculative bets is key. However, "safe" depends on time horizon—what’s low-risk for a 60-year-old may not be for a 25-year-old.
Q: How do student loans affect household net worth?
Student debt suppresses net worth in two ways: it’s a liability that reduces total assets, and it delays major wealth-building milestones (homeownership, investing). A 2023 Federal Reserve study found that households with student loans have net worth and assets of households about 30% lower than those without, even after controlling for income. The debt also limits financial flexibility during crises.
Q: Can a household’s net worth ever be negative?
Yes. If liabilities exceed assets (e.g., a home worth less than the mortgage, combined with credit card debt), net worth is negative. This is common in foreclosure scenarios or during economic downturns. Negative net worth doesn’t mean insolvency—it means the household is "underwater" and must rebuild assets to recover.
Q: How do offshore accounts and trusts impact household wealth?
Offshore accounts and trusts are tools for wealth preservation and tax optimization, primarily used by high-net-worth households. They can shield assets from creditors, reduce estate taxes, or provide privacy. However, they’re costly to set up and maintain, and improper use can trigger legal or tax penalties. For most families, simpler strategies (retirement accounts, life insurance trusts) suffice.
Q: What’s the biggest myth about household net worth?
The biggest myth is that net worth is purely about income or spending habits. While discipline matters, the timing of wealth accumulation (inheritance, market cycles) and access to opportunities (education, networks) play outsized roles. Many high-earners remain poor in net worth due to debt or poor investment choices, while others with modest incomes thrive through frugality and smart asset allocation.
