
The Complete Overview of How Many Millionaires in the US Combined Net Worth
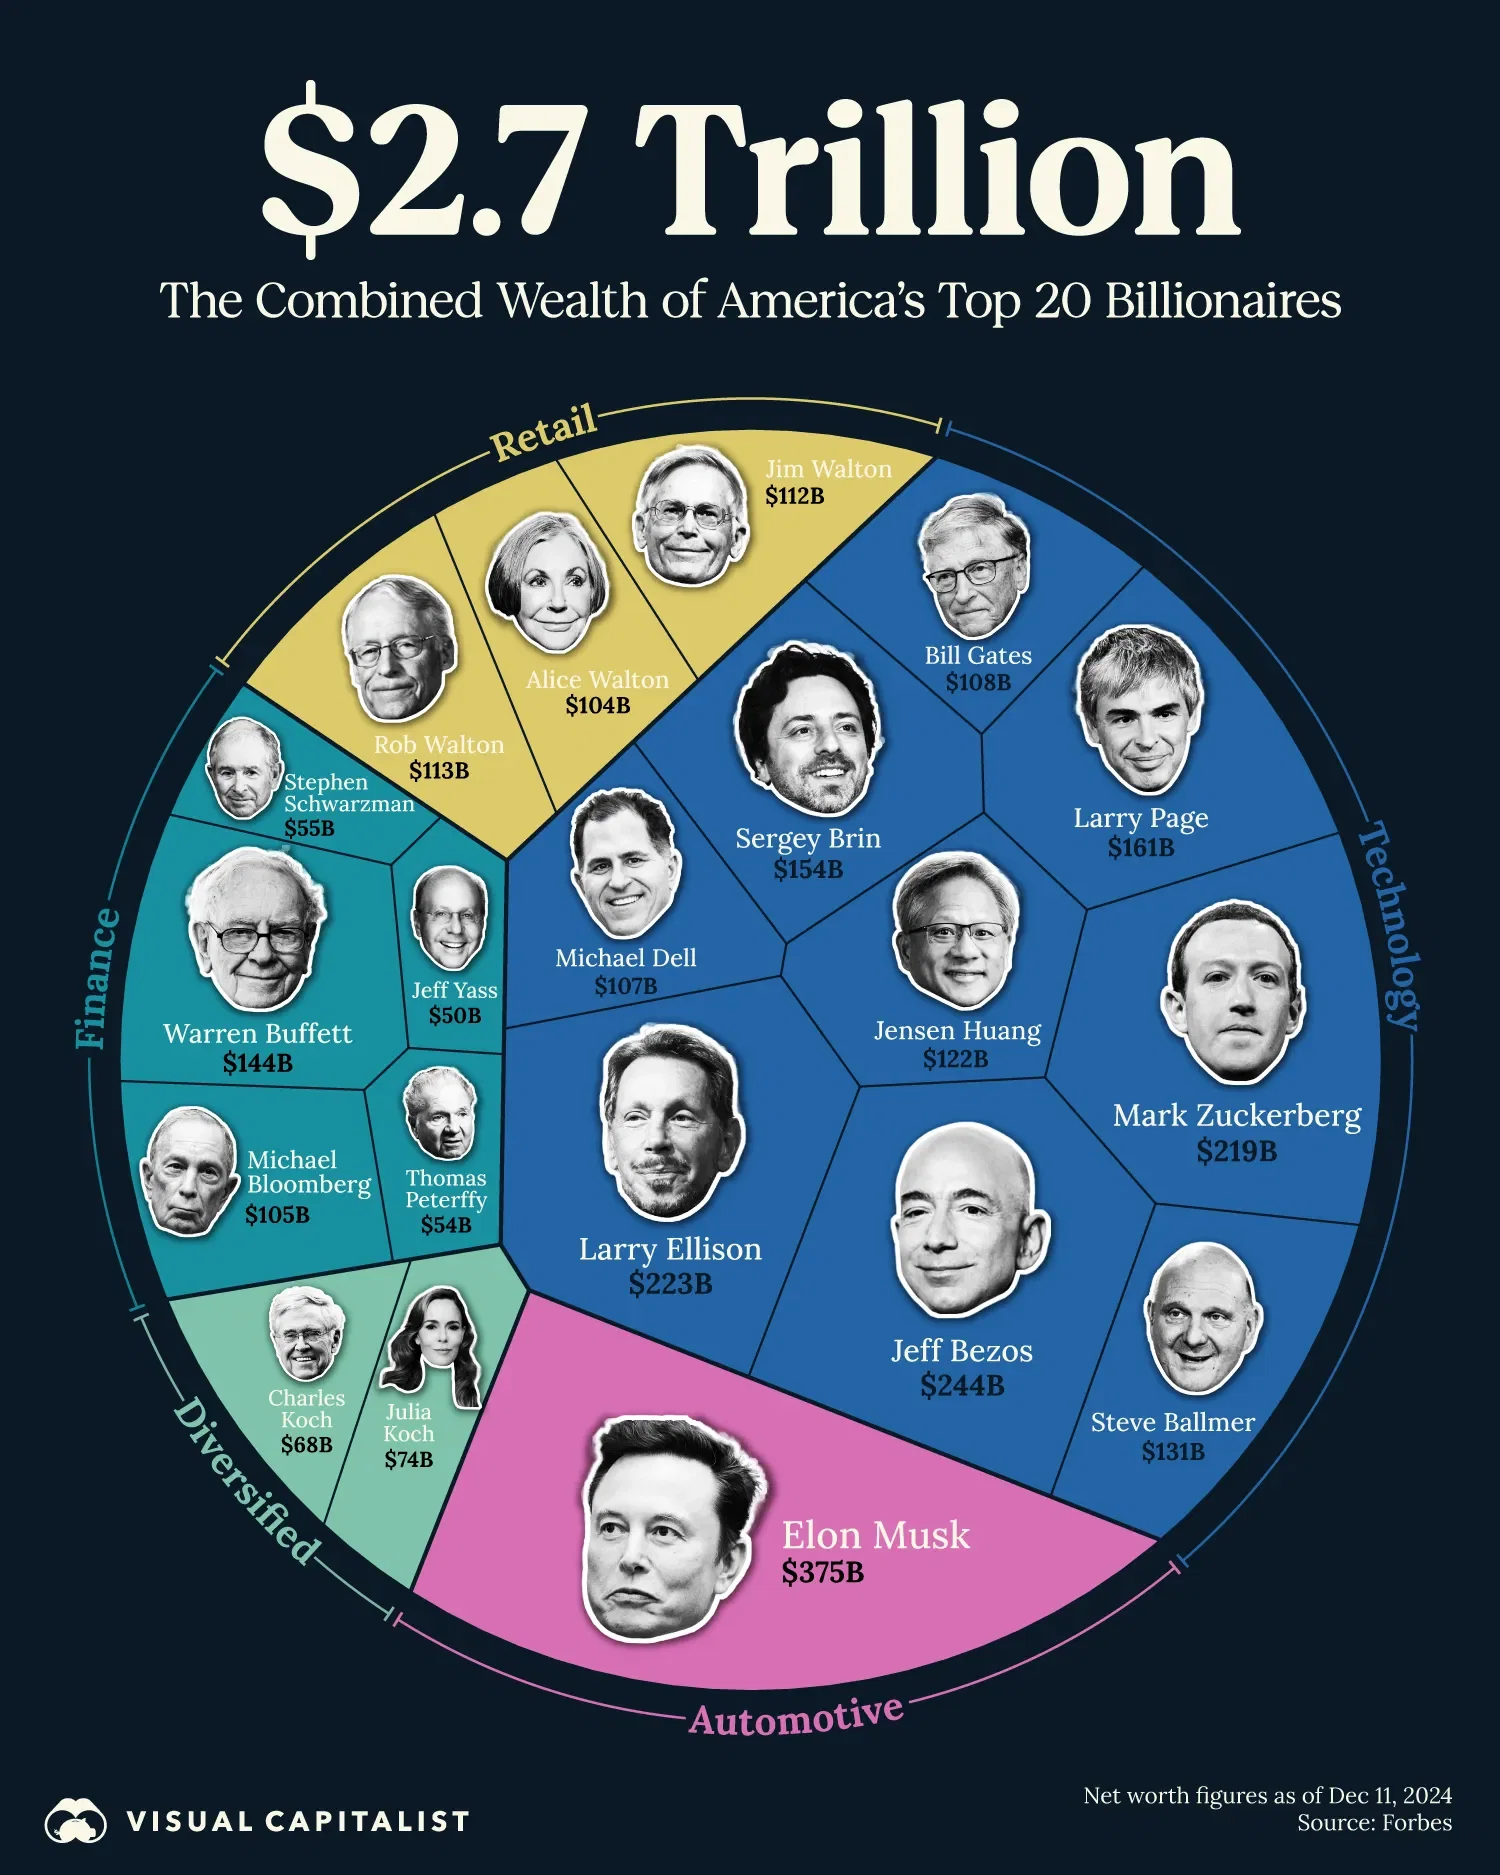
The most cited estimate for the combined net worth of U.S. millionaires hovers around $50 trillion, though this figure is fluid. To put that in perspective, it exceeds the annual GDP of Germany, the world’s fourth-largest economy. But here’s the catch: this total includes all liquid and illiquid assets, from publicly traded stocks to family-owned businesses, art collections, and even cryptocurrency holdings. The challenge lies in verification—wealth isn’t just cash in the bank. A tech executive’s unvested equity or a farmer’s land value might not appear on a balance sheet but still contribute to the millionaire count. The breakdown reveals another layer: household wealth vs. individual wealth. The SCF defines a millionaire as a household with net assets of $1 million or more, excluding primary residences. This means a couple with a $3 million portfolio but a $2 million mortgage could still qualify. When you factor in deferred compensation (like restricted stock units) and non-reportable assets (such as certain trusts), the true figure likely exceeds published estimates. For context, the bottom 50% of U.S. households collectively hold just 2.6% of total wealth—a disparity that underscores why the combined net worth of U.S. millionaires dominates economic narratives.Historical Background and Evolution
The modern millionaire class in the U.S. didn’t emerge overnight. Post-World War II saw the rise of industrial dynasties—Rockefellers, Fords—but it was the 1980s tax reforms that truly accelerated wealth accumulation. The elimination of estate taxes on large inheritances and the capital gains tax cuts turned asset appreciation into a wealth-generation engine. By the 1990s, the dot-com boom created a new cohort of millionaires overnight, many of whom saw paper fortunes vanish in the 2000 crash. Yet the rebound was swift, fueled by the 2010s real estate recovery and the S&P 500’s decade-long bull market. The combined net worth of U.S. millionaires today is a product of these cycles, but also of structural shifts. The decline of unionized labor, the gig economy’s rise, and the financialization of wealth (where assets like stocks and bonds replace wages as primary income sources) have reshaped who qualifies as a millionaire. In 1989, the average millionaire was a 55-year-old white male with a college degree; today, it’s increasingly diverse, though still skewed toward older, male, and white demographics. The pandemic’s stock market rally alone added $5.2 trillion to U.S. household wealth in 2020–2021, with the top 10% capturing the lion’s share.Core Mechanisms: How It Works
The combined net worth of U.S. millionaires isn’t just about individual savings—it’s about compounding advantages. Consider the wealth multiplier effect: a millionaire investing in private equity or venture capital can see returns of 20–30% annually, far outpacing the average 401(k) or IRA. Meanwhile, the tax code’s step-up in basis allows heirs to inherit appreciated assets without capital gains taxes, preserving wealth across generations. Add to this the homeownership advantage—millionaires are far more likely to own multiple properties, benefiting from both rental income and equity appreciation—and the system becomes self-reinforcing. The data also highlights asset class dominance. Publicly traded stocks account for 40% of the average millionaire’s portfolio, followed by business equity (25%) and real estate (20%). Cash and equivalents make up just 5%. This concentration in volatile assets explains why the combined net worth of U.S. millionaires can swing wildly with market cycles. The 2008 financial crisis saw U.S. millionaire wealth drop by 25%, but the recovery was swift—thanks in part to monetary policy tools like quantitative easing, which disproportionately benefited those with existing wealth.Key Benefits and Crucial Impact
The combined net worth of U.S. millionaires isn’t just a statistic—it’s a driver of economic activity. Millionaires spend more on high-margin services (private education, luxury goods, financial advisory), which employ white-collar workers and stimulate local economies. They also invest in startups, fueling job creation, and donate to philanthropic causes, shaping everything from healthcare research to arts funding. Yet the benefits aren’t evenly distributed. Critics argue that this wealth concentration distorts markets, inflating asset prices beyond what average earners can access. The impact extends to political influence. Wealthy individuals and families contribute disproportionately to campaigns, lobby for tax policies that favor capital gains, and fund think tanks that shape policy debates. A 2022 study found that the top 0.1% of earners—those with incomes over $5 million—spend $1,400 per year on lobbying, compared to the average household’s $50. This isn’t just about money; it’s about access to power, which further entrenches the combined net worth of U.S. millionaires as an immutable force.“Wealth isn’t just money—it’s the ability to shape the rules by which money is made.” — Thomas Piketty, Capital in the Twenty-First Century
Major Advantages
- Economic stimulus: Millionaires drive demand for premium services, from concierge medicine to bespoke real estate, creating niche industries.
- Innovation funding: Venture capital and angel investing from high-net-worth individuals account for 60% of early-stage startup funding in the U.S.
- Philanthropic leverage: The top 10% of donors contribute 80% of all charitable giving, directing billions toward education, healthcare, and social causes.
- Tax revenue generation: While often criticized, millionaires pay a significant share of federal taxes—40% of all income taxes come from the top 1%, according to the IRS.
- Intergenerational wealth transfer: Trusts and inheritance laws ensure that 70% of millionaire status is inherited, not earned, perpetuating wealth dynasties.
- Market liquidity: High-net-worth individuals provide $1.5 trillion annually in liquidity to financial markets through investments, loans, and purchases.
Comparative Analysis
| Metric | U.S. Millionaires | Global Millionaires |
|---|---|---|
| Total Count (2023) | 23.1 million | 62.5 million |
| Combined Net Worth | $50 trillion (est.) | $90 trillion (est.) |
| Share of Global Wealth | 55% | — |
| Average Net Worth per Millionaire | $2.2 million | $1.4 million |
Future Trends and Innovations
The combined net worth of U.S. millionaires is poised for further concentration, driven by AI and automation. High-net-worth individuals are already leveraging AI for algorithm-driven investing, personalized wealth management, and even predictive philanthropy. The rise of tokenized assets (blockchain-based securities) could also democratize access—but only for those with existing capital to invest. Meanwhile, regulatory changes, such as potential wealth taxes or stricter inheritance rules, may test the resilience of this wealth pool. Demographic shifts will play a role too. The millennial generation—now the largest cohort of potential millionaires—prioritizes liquidity and diversification over traditional real estate holdings. This could lead to a decline in physical asset concentration and a rise in alternative investments like private credit or digital assets. Yet without structural reforms, the gap between the top 1% and the rest will likely widen, making the combined net worth of U.S. millionaires an even more dominant force in the economy.Conclusion
The combined net worth of U.S. millionaires is more than a number—it’s a reflection of an economy where wealth begets wealth. The data tells a story of accelerating inequality, but also of systemic advantages that few can access. Whether this concentration is sustainable—or even desirable—depends on how society chooses to address it. Tax policy, education reform, and labor market changes could all reshape the landscape, but for now, the trends suggest one thing: the millionaire class’s grip on wealth will only tighten. The challenge lies in balancing economic growth with equitable opportunity. The combined net worth of U.S. millionaires won’t disappear, but its impact—on markets, politics, and daily life—will depend on the choices made today.Comprehensive FAQs
Q: How is the combined net worth of U.S. millionaires calculated?
The Federal Reserve’s Survey of Consumer Finances (SCF) provides the most authoritative estimate, summing liquid and illiquid assets (stocks, real estate, businesses) for households with net worth ≥$1 million. Private estimates, like those from Credit Suisse or Wealth-X, use similar methodologies but may include offshore wealth or adjust for inflation differently.
Q: Does the combined net worth include offshore accounts?
Most U.S.-based estimates (e.g., SCF) exclude offshore wealth unless reported. Global studies (like Credit Suisse’s Global Wealth Report) often incorporate offshore holdings, which can add $5–10 trillion to the total. The IRS’s Foreign Bank Account Reporting (FBAR) requirements aim to close this gap, but compliance remains uneven.
Q: How does the pandemic affect the combined net worth of U.S. millionaires?
The pandemic supercharged wealth inequality. Stock market rallies (S&P 500 up ~90% from March 2020) and stimulus checks inflated portfolios, while median households saw no real wage growth. The combined net worth of U.S. millionaires grew by $5.2 trillion in 2020–2021, per Federal Reserve data, as asset prices surged and unemployment benefits propped up spending.
Q: Are there regional differences in millionaire wealth?
Yes. New York, California, and Texas dominate, holding ~60% of all U.S. millionaire wealth. Coastal cities (San Francisco, Boston) have higher concentrations of high-net-worth individuals (HNWIs), while Texas benefits from energy wealth and low taxes. Rural areas and the Midwest lag, with <5% of millionaires residing outside major metros.
Q: Could a wealth tax reduce the combined net worth of U.S. millionaires?
Potentially, but the impact would depend on design. A 2% annual tax on net worth over $50 million (as proposed by Sen. Elizabeth Warren) could raise $3 trillion over a decade, but wealthy individuals might shift assets to trusts, private companies, or offshore accounts to avoid it. Historical examples (e.g., 1930s estate taxes) show such policies can slow wealth accumulation—but they rarely erase it entirely.
Q: How does the U.S. compare to other countries in millionaire wealth?
The U.S. leads in both count and total wealth, with $50 trillion vs. China’s $30 trillion (per Credit Suisse). Europe’s wealth is more widely distributed—Germany and France have lower millionaire concentrations but stronger social safety nets. Japan’s millionaire wealth is stagnant due to aging populations and deflation, while emerging markets (India, Brazil) see rapid growth but from lower bases.
Q: What’s the biggest misconception about the combined net worth of U.S. millionaires?
The assumption that most millionaires are self-made entrepreneurs. In reality, 70% inherit wealth or gain it through asset appreciation (stocks, real estate) rather than founding businesses. Additionally, many millionaires are "paper-rich"—their wealth is tied to volatile assets (e.g., private equity, crypto) that can evaporate in downturns.
