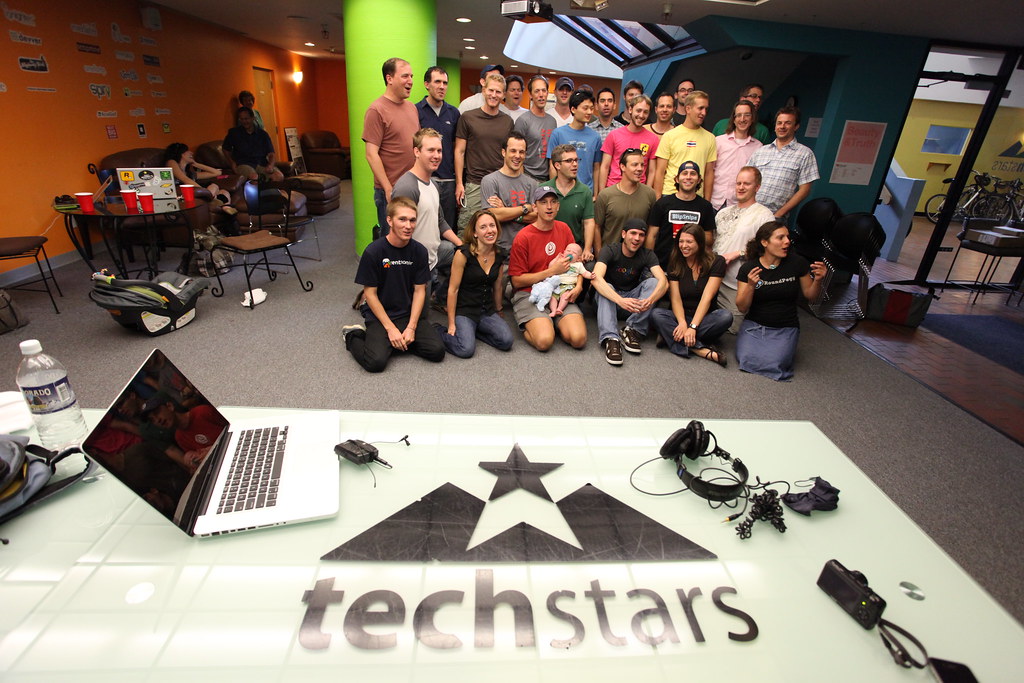
Where It All Began
Techstars’ origins trace back to a frustration. In the early 2000s, Cohen watched as startup after startup in Colorado struggled to access the same resources as their peers in California. The problem wasn’t capital—it was the ecosystem. Founders lacked mentors, investors were risk-averse, and the feedback loop between success and failure was broken. The solution? A 12-week program where startups would live together, share resources, and receive structured feedback from a curated group of investors and operators. The first Demo Day in 2007 drew 200 people; by 2012, it was sold out at 1,000 seats. The model was crude but effective: take a small equity stake, provide $120,000 in seed funding, and offer access to a network that could turn a prototype into a pitch deck worth millions. The early signs of Techstars’ potential were clear before the first big exits. SendGrid’s acquisition by Microsoft in 2011 for $1 billion wasn’t just a windfall—it was validation. Suddenly, accelerators weren’t seen as charity; they were seen as a calculated bet. Cohen’s legal background gave him an edge: he understood the fine print of equity splits, founder vesting, and investor protections better than most VCs. While others in the industry were still debating whether accelerators were a fad, he was structuring deals that would make them indispensable. By 2013, Techstars had raised $100 million in its first institutional fund, proving that the model could scale beyond bootstrapped experiments.The Early Signs
The real inflection point came when Techstars stopped being a regional experiment and became a global franchise. In 2012, the company launched its first international campus in London, followed quickly by New York and Berlin. Each location wasn’t just a copy of Denver—it was tailored to its market, whether that meant courting European angel investors or partnering with NYC’s deep-pocketed VC firms. The strategy paid off: by 2015, Techstars had backed over 1,000 companies, with an alumni network that included founders who would later raise billions. Cohen’s ability to attract top-tier talent—both as mentors and as founders—was another early indicator of his influence. Names like Marc Andreessen (who joined as a mentor) and Fred Wilson (who invested in Techstars’ funds) lent credibility, but the real leverage came from the founders themselves. Many of them, after graduating from Techstars, went on to raise Series A rounds from the same investors who’d once dismissed accelerators as a gimmick. The feedback loop was now self-reinforcing: successful alumni attracted better mentors, which in turn attracted better founders, which pushed the value of Techstars’ equity stakes higher.The Turning Point
The moment Techstars transitioned from a scrappy accelerator to a venture capital powerhouse was when it launched its first institutional fund in 2013. No longer just a program, Techstars had become a fund manager, with Cohen at the helm of a machine that could deploy capital at scale. The fund’s first close at $100 million was modest by Silicon Valley standards, but it signaled a shift: Techstars wasn’t just helping startups; it was becoming one of them. The fund’s success—backed by limited partners like Google Ventures and Founder Collective—proved that accelerators could be a viable asset class, not just a side project. What changed wasn’t just the capital; it was the mindset. Before Techstars, VCs saw accelerators as a loss leader, a way to scout talent for their own funds. After Techstars, they saw them as a high-margin business. The model’s reproducibility meant that competitors like Y Combinator and 500 Startups would have to adapt or risk obsolescence. For Cohen, this was the ultimate validation: he hadn’t just built a company; he’d built a category. And as the category grew, so did the speculation about how much of that growth was flowing into his personal net worth."The best accelerators don’t just fund startups—they fund ecosystems. And the best founders don’t just take money; they take ownership of the future." — David Cohen, 2015

The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 2006–2009 | Techstars launches in Denver with 5 companies. First exits (e.g., SendGrid prototype) prove the model’s viability. Cohen pivots from lawyer to full-time entrepreneur. |
| 2010–2012 | Expansion to New York and London. First institutional investors (Google Ventures) take notice. Alumni like Wildfire (acquired by Google) validate the accelerator’s ability to produce acquirables. |
| 2013–2015 | Launch of Techstars Ventures fund ($100M). Cohen steps back from daily operations but remains a strategic advisor. Net worth estimates begin appearing in industry reports. |
| 2016–2018 | Global expansion accelerates (18 campuses by 2018). Techstars backs companies like ClassPass (valued at $1.3B) and others that later go public or are acquired for hundreds of millions. |
| 2019–Present | Cohen’s focus shifts to later-stage investments and advisory roles. Techstars’ alumni network raises over $50B in follow-on funding. Reports suggest his net worth has grown into the hundreds of millions, driven by equity stakes, secondary sales, and angel investments. |
Lessons From the Journey
- Networks compound value. Techstars’ real asset wasn’t its capital—it was the relationships between founders, investors, and mentors. Cohen understood that a single exit (like SendGrid) could unlock opportunities for dozens of other companies.
- Reproducibility beats uniqueness. While other accelerators bet on "secret sauce," Techstars’ success came from its ability to clone its model globally. This scalability directly translated into higher valuations for Cohen’s equity.
- Founders drive the economy. By giving founders a structured path to funding, Techstars didn’t just create companies—it created a class of entrepreneurs who would later become investors, mentors, and repeat founders.
- Wealth follows influence. Cohen’s net worth isn’t just tied to Techstars’ equity; it’s tied to his ability to shape the industry’s direction. As accelerators became a standard tool in startup toolkits, his role as an architect of that toolkit became increasingly valuable.
Where Things Stand Today
As of 2024, Techstars remains one of the most recognizable brands in early-stage venture capital, with a portfolio that includes unicorns, public companies, and hundreds of acquired businesses. Cohen’s direct involvement has diminished—he stepped down as CEO in 2018 to focus on investments and advisory roles—but his fingerprints are everywhere. The company he co-founded now manages billions in assets, and its alumni network is a who’s who of the startup world. Meanwhile, discussions about Techstars’ net worth and its founders’ personal fortunes persist, though exact figures remain private. What’s clear is that Cohen’s wealth is no longer just about Techstars’ equity. It’s about the secondary markets where his early stakes in companies like SendGrid or ClassPass have been sold or diluted over time. It’s about his angel investments in later-stage startups, his real estate holdings in tech hubs, and his influence over a generation of founders who now look to him for guidance. The man who once drafted term sheets now sits at the intersection of venture capital, entrepreneurship, and the new economy’s power dynamics. And while the exact number tied to David Cohen’s net worth remains speculative, the trajectory is undeniable: he didn’t just build an accelerator. He helped build the infrastructure that would define how startups are funded, scaled, and valued in the 21st century.
Conclusion
The story of Techstars and David Cohen is more than a tale of wealth accumulation—it’s a case study in how an idea can reshape an industry. What started as a bet on structured mentorship became a blueprint for global entrepreneurship, and what began as a side project for a lawyer turned into one of the most influential venture capital vehicles of the past two decades. The numbers—whether it’s Techstars’ $50 billion+ alumni funding or the estimated hundreds of millions tied to Cohen’s net worth—are secondary to the larger truth: he didn’t just fund startups. He funded the future. For founders, investors, and policymakers, the lesson is clear: the accelerators of today are the venture capital firms of tomorrow. And the architects of those accelerators? Their wealth is just the most visible measure of their impact. The real legacy isn’t in the balance sheets, but in the thousands of companies that might never have existed without a 12-week program in Denver, a handshake in New York, or a bet on an idea that once seemed too risky to fund.Comprehensive FAQs
Q: How much is David Cohen’s net worth estimated to be?
Industry estimates place David Cohen’s net worth in the hundreds of millions, driven by his equity stakes in Techstars, secondary sales of portfolio company shares, and angel investments. Exact figures are private, but reports suggest his fortune has grown significantly since Techstars’ early days, particularly after high-profile exits like SendGrid and ClassPass.
Q: What is Techstars’ net worth, and how does it relate to David Cohen’s wealth?
Techstars itself is valued at over $1 billion as of recent private market assessments, though its "net worth" is more accurately measured by the cumulative value of its portfolio companies, funds, and global campuses. Cohen’s personal wealth is tied to his ownership stake in Techstars, secondary sales of equity in alumni companies, and his role as an investor in later-stage startups. The two are interconnected—Techstars’ success directly fuels his net worth.
Q: Did David Cohen sell his stake in Techstars, or does he still own a significant portion?
Cohen stepped down as CEO in 2018 but remains a significant shareholder and advisor. While exact ownership percentages aren’t public, he has not sold his core stake in Techstars. His wealth strategy appears to focus on holding long-term equity while leveraging his influence to access higher-margin investments in later-stage companies.
Q: How does Techstars make money, and where does David Cohen’s wealth come from?
Techstars generates revenue through multiple streams: equity stakes in portfolio companies (typically 6–10%), management fees from its venture funds, and corporate partnerships (e.g., sponsorships from Google, Microsoft). Cohen’s wealth comes from:
- His original equity in Techstars (diluted over time but still substantial).
- Secondary sales of shares in alumni companies like SendGrid or ClassPass.
- Angel investments in high-growth startups.
- Advisory roles and board seats in later-stage ventures.
Q: Are there any public records or filings that disclose David Cohen’s net worth?
No. Unlike public company executives, private individuals like Cohen are not required to disclose their net worth. Estimates come from industry reports, proxy disclosures (where applicable), and anecdotal evidence from his investments. For example, if a portfolio company like ClassPass is valued at $1.3 billion and Cohen holds a small stake, that alone could add tens of millions to his net worth—but without insider confirmation, such figures remain speculative.
Q: How has Techstars’ global expansion affected David Cohen’s net worth?
Techstars’ expansion from a single Denver campus to 18 global locations has dramatically increased its valuation and Cohen’s stake value. Each new campus generates revenue through fees and equity, while the global alumni network (now raising $50B+ in follow-on funding) creates secondary markets where Cohen’s early investments appreciate. Additionally, his reputation as a global operator has opened doors to higher-profile investments, further diversifying his wealth.
Q: What’s the biggest misconception about David Cohen’s wealth?
The biggest myth is that his fortune comes primarily from Techstars’ equity. While that’s a major component, his wealth is also tied to his ability to identify and invest in the right founders at the right time. Many of his most lucrative gains have come from angel investments in companies that never went through Techstars—proof that his influence extends far beyond the accelerator’s walls.
Q: Has David Cohen’s net worth been affected by market downturns, like the 2022 tech crash?
Like most venture-backed figures, Cohen’s net worth is exposed to market volatility. The 2022 downturn—where public tech valuations plummeted and late-stage funding dried up—likely took a toll on his portfolio, particularly in companies that went public or were acquired at inflated valuations. However, his long-term holdings in private companies and diversified investments (including real estate) may have acted as a hedge. The key difference is that while public market valuations fell, private company valuations (where much of his wealth is tied) often hold up better in downturns.
Q: What’s next for David Cohen and Techstars in terms of wealth growth?
Cohen’s focus appears to be shifting toward later-stage investments and advisory roles, where his network and reputation command premium valuations. Techstars itself is exploring new revenue streams, such as corporate innovation programs and AI-focused accelerators. If current trends hold, his wealth will continue growing through:
- Successes in Techstars’ newer funds (e.g., Techstars Ventures II).
- High-profile exits or IPOs from alumni companies.
- Strategic real estate plays in tech hubs.
- Leveraging his brand for high-margin advisory or board roles.
