
7 Things Worth Knowing About DealDash Net Worth
The platform’s financial health isn’t just about balance sheets. It’s about the interplay of user behavior, deal structures, and market liquidity. Here’s what the numbers—and the gaps between them—tell us.1. DealDash’s valuation isn’t public, but its revenue model is transparent
DealDash operates on a pay-to-bid system where users purchase credits to participate in auctions. The platform’s DealDash net worth isn’t directly tied to inventory costs; instead, it’s derived from the volume of bids and the frequency of high-value transactions. Unlike eBay, which relies on seller fees, DealDash’s revenue comes from upfront bid purchases, creating a predictable cash flow. Industry estimates suggest annual revenue figures hover around the $50–75 million range, though exact numbers are rarely disclosed. The model’s strength lies in its simplicity: the more users bid, the higher the platform’s take—regardless of whether the auction succeeds. This structure also explains why DealDash avoids the volatility of traditional retail. There’s no reliance on unsold inventory or seasonal slumps. Instead, the platform’s DealDash net worth is a function of bidder retention and the perceived value of its deals. When users perceive auctions as fair—where the lowest bidder wins but still secures a discount—the system self-perpetuates. The challenge? Proving that perception holds as competition from flash-sale apps like Gilt or even TikTok’s resale trends intensifies.2. The founder’s role in shaping DealDash’s valuation
DealDash was launched in 2008 by Jeffrey Miller, a serial entrepreneur whose previous ventures included the now-defunct BidCake. Miller’s approach to DealDash was unconventional: he eschewed traditional venture funding, instead bootstrapping the platform through user-generated revenue. This decision had lasting implications for the company’s DealDash net worth. Without external investors, DealDash avoided the pressure to scale aggressively or pivot to unrelated markets. Instead, it focused on niche dominance—particularly in electronics, beauty, and home goods—where deal structures could be tightly controlled. Miller’s hands-off management style also meant DealDash never pursued an IPO or major acquisition. Unlike competitors that sold to corporate giants (e.g., eBay’s acquisition of ShopGoodwill), DealDash remained independent. This autonomy allowed the platform to optimize for long-term bidder psychology rather than short-term investor returns. The trade-off? A slower but steadier accumulation of DealDash net worth, built on organic growth rather than explosive scaling.3. User acquisition costs are the silent driver of valuation
Acquiring and retaining bidders is DealDash’s highest variable cost, and it directly impacts the platform’s DealDash net worth. Unlike social media platforms that monetize attention, DealDash’s value depends on converting browsers into active bidders. The platform invests heavily in referral programs, influencer partnerships, and email marketing—strategies that, if successful, increase bid volume without proportionally increasing costs. However, the customer acquisition cost (CAC) remains a critical metric. Industry reports suggest that for every dollar spent on marketing, DealDash generates $3–5 in bid revenue, but the margin narrows as competition grows. The real test of DealDash’s net worth sustainability lies in its ability to monetize casual users. A one-time bidder is less valuable than a repeat player who treats DealDash like a subscription service. The platform’s success hinges on whether it can turn occasional shoppers into habitual bidders—a challenge that becomes harder as alternatives like Facebook Marketplace or OfferUp encroach on its turf.4. The secondary market effect: How DealDash’s deals influence resale values
One of DealDash’s most underrated assets is its impact on secondary market pricing. When DealDash auctions a product at a steep discount, it doesn’t just move inventory—it sets a benchmark for resale values. For example, a DealDash deal on a $500 TV priced at $150 creates a ripple effect: sellers on eBay or Amazon may adjust their listings downward, knowing DealDash’s model attracts bargain hunters. This price discovery function indirectly boosts DealDash’s net worth by increasing the perceived scarcity of its deals. The flip side? If DealDash’s discounts become too aggressive, they risk depressing resale markets for its own sellers. The platform must strike a balance—offering enough value to drive bids but not so much that it undermines the secondary economy it relies on. This delicate equilibrium is a key factor in why DealDash’s valuation hasn’t seen the same explosive growth as platforms like Poshmark or StockX, which deal in higher-margin niche goods.5. The role of partnerships in DealDash’s financial health
DealDash’s DealDash net worth isn’t solely derived from its auction model. A significant portion comes from brand partnerships, where retailers pay to feature their products as exclusive deals. Companies like Samsung, Sephora, and Best Buy have all collaborated with DealDash to liquidate overstock or promote new launches. These partnerships aren’t just revenue streams—they’re trust signals that attract bidders. When a user sees a deal from a recognizable brand, the platform’s credibility—and thus its valuation potential—increases. However, these partnerships come with risks. If a deal flops (e.g., a product sells for far less than retail), the brand may pull future collaborations, reducing DealDash’s high-margin partnership revenue. The platform’s ability to curate successful deals is a direct indicator of its financial stability. Analysts note that DealDash’s net worth growth correlates strongly with its ability to secure high-profile, high-conversion partnerships—a metric that’s harder to quantify than bid volume alone.6. The dark side of DealDash’s valuation: Chargebacks and fraud
For every successful bid, DealDash faces the risk of chargebacks, fraudulent activity, or bid manipulation. These issues don’t just erode revenue—they directly impact the platform’s net worth by increasing customer service costs and damaging reputation. DealDash’s model relies on trust, and any perception of unfairness (e.g., a bidder feeling cheated by a deal’s terms) can trigger a cascade of negative reviews or abandoned accounts. The platform mitigates this through automated bidding systems, buyer protection policies, and strict deal vetting. Yet, the cost of these safeguards is a hidden drain on profitability. Industry estimates suggest that 5–10% of DealDash’s revenue is allocated to fraud prevention and dispute resolution—a figure that, while small in absolute terms, becomes significant when scaled across millions of transactions. The balance between open bidding and security is a constant tightrope walk that affects DealDash’s long-term net worth stability."DealDash’s valuation isn’t just about the deals—it’s about the ecosystem it creates. If the bidders stop trusting the system, the whole house of cards collapses." — Industry analyst specializing in secondary market platforms (2023)
7. The exit strategy: Why DealDash hasn’t been acquired (yet)
Despite its profitability and niche dominance, DealDash remains privately held, with no signs of an impending acquisition. This isn’t for lack of interest—eBay, Walmart, and even private equity firms have reportedly explored deals in the past. So why hasn’t it sold? The answer lies in Miller’s long-term vision and the platform’s self-sustaining model. An acquisition would require DealDash to pivot toward broader e-commerce, diluting the very psychology that drives its DealDash net worth. Additionally, the platform’s low overhead makes it an attractive target, but its lack of scalability in traditional retail terms is a red flag for some buyers. DealDash isn’t built to compete with Amazon or Shopify—it’s optimized for high-frequency, low-margin transactions. This specialization is both its strength and its limitation. Until a buyer emerges willing to preserve its auction-centric model, DealDash will continue operating independently, accumulating net worth through organic growth rather than a windfall sale.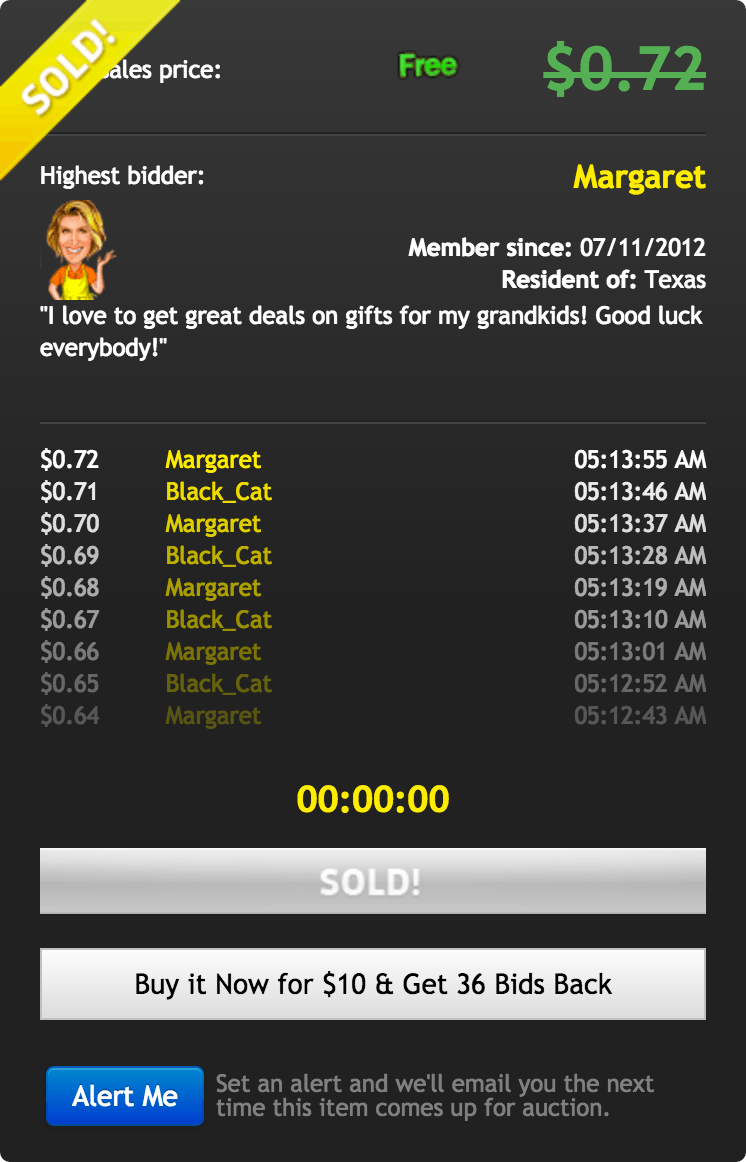
How These Facts Connect
DealDash’s net worth isn’t a static figure—it’s a dynamic interplay between user behavior, deal structures, and external market forces. The platform’s revenue model thrives on recurring bidder engagement, but its long-term valuation depends on maintaining trust in an era where alternatives like TikTok Shop or Shein’s flash sales are eating into its user base. The partnerships and secondary market effects aren’t just revenue streams; they’re feedback loops that reinforce DealDash’s position as a bargain-hunting authority. The absence of an acquisition also tells a story: DealDash’s net worth is being built for sustainability, not a quick exit. Unlike platforms that chase viral growth at the expense of margins, DealDash’s pay-to-bid model ensures predictable cash flow—even if it caps its potential for explosive scaling. The trade-off is clear: steady profitability over rapid expansion. This philosophy explains why DealDash’s valuation remains resilient but unassuming—a quiet giant in the resale economy.| Key Factor | Impact on DealDash Net Worth | Risk to Growth |
|---|---|---|
| Pay-to-bid revenue model | Predictable cash flow, low inventory risk | Dependence on bidder retention |
| Brand partnerships | High-margin revenue, credibility boost | Partnership pullouts if deals underperform |
| Secondary market influence | Price discovery benefits platform liquidity | Risk of depressing resale values for sellers |
| Fraud and chargebacks | Erodes profitability if unchecked | Customer service costs rise with scale |

Conclusion
DealDash’s net worth is a study in niche dominance. It doesn’t chase the latest e-commerce trends—it refines an existing model into a self-sustaining engine. The platform’s strength lies in its simplicity: a feedback loop where bidders, deals, and brand trust reinforce each other. Yet this same simplicity is its vulnerability. As consumer habits shift toward instant gratification (e.g., same-day delivery, social commerce), DealDash’s auction-based timing could become a liability. The bigger question isn’t whether DealDash will hit a $100 million valuation—it’s whether its model can adapt without losing its core identity. The platform’s net worth isn’t just a number; it’s a barometer of how far bargain hunting can scale in a world where discounts are everywhere. For now, DealDash remains a quiet success story—one that proves profitability doesn’t always require disruption, just relentless optimization.Comprehensive FAQs
Q: Is DealDash profitable?
A: Yes, DealDash operates at a consistently profitable level, though exact figures aren’t public. Its pay-to-bid model ensures revenue is generated upfront, reducing reliance on unsold inventory. Profitability is tied to bidder retention and partnership deals, with industry estimates suggesting net margins around 20–30%. The platform’s strength lies in its low overhead—no warehouses, no physical retail—just a digital auction house.
Q: Has DealDash ever been valued at over $100 million?
A: There’s no verified record of DealDash’s valuation exceeding $100 million. While the platform is profitable and growing, its private ownership and niche focus limit its appeal to high-value acquirers. Reports of acquisition talks (e.g., with eBay or Walmart) have surfaced, but no deals have materialized. The lack of an IPO or major sale suggests its net worth is being built for long-term stability rather than a liquidity event.
Q: How does DealDash’s net worth compare to similar platforms?
A: DealDash’s net worth is harder to pinpoint than platforms like eBay or Poshmark, which have public disclosures. However, based on revenue estimates ($50–75M annually) and profitability, it sits below Poshmark’s reported $1.8B valuation (2023) but above smaller niche auction sites. The key difference? DealDash’s model is less about reselling used goods and more about driving high-volume, low-margin transactions—a strategy that caps its growth ceiling but ensures steady, predictable earnings.
Q: Could DealDash be acquired in the next 5 years?
A: The possibility exists, but it depends on three factors: 1. A buyer willing to preserve DealDash’s auction model (most acquirers would push for broader e-commerce integration). 2. A shift in consumer behavior toward more auction-based shopping (currently, instant-purchase models dominate). 3. Miller’s exit strategy—if he chooses to sell, the platform’s valuation could spike due to its self-sustaining revenue streams. For now, no major suitors have emerged, and DealDash’s independent trajectory suggests it may remain private for the foreseeable future.
Q: What’s the biggest threat to DealDash’s net worth?
A: The biggest existential threat isn’t competition—it’s user fatigue. DealDash’s model relies on scarcity and urgency, but if bidders perceive the platform as too predictable or overpriced, they’ll migrate to alternatives like Facebook Marketplace or TikTok’s resale trends. Additionally, fraud risks (e.g., bid manipulation, chargebacks) could erode trust if not managed carefully. Unlike social commerce platforms that benefit from network effects, DealDash’s net worth depends on maintaining the illusion of exclusivity—a delicate balance in an era of hyper-competitive discounts.
