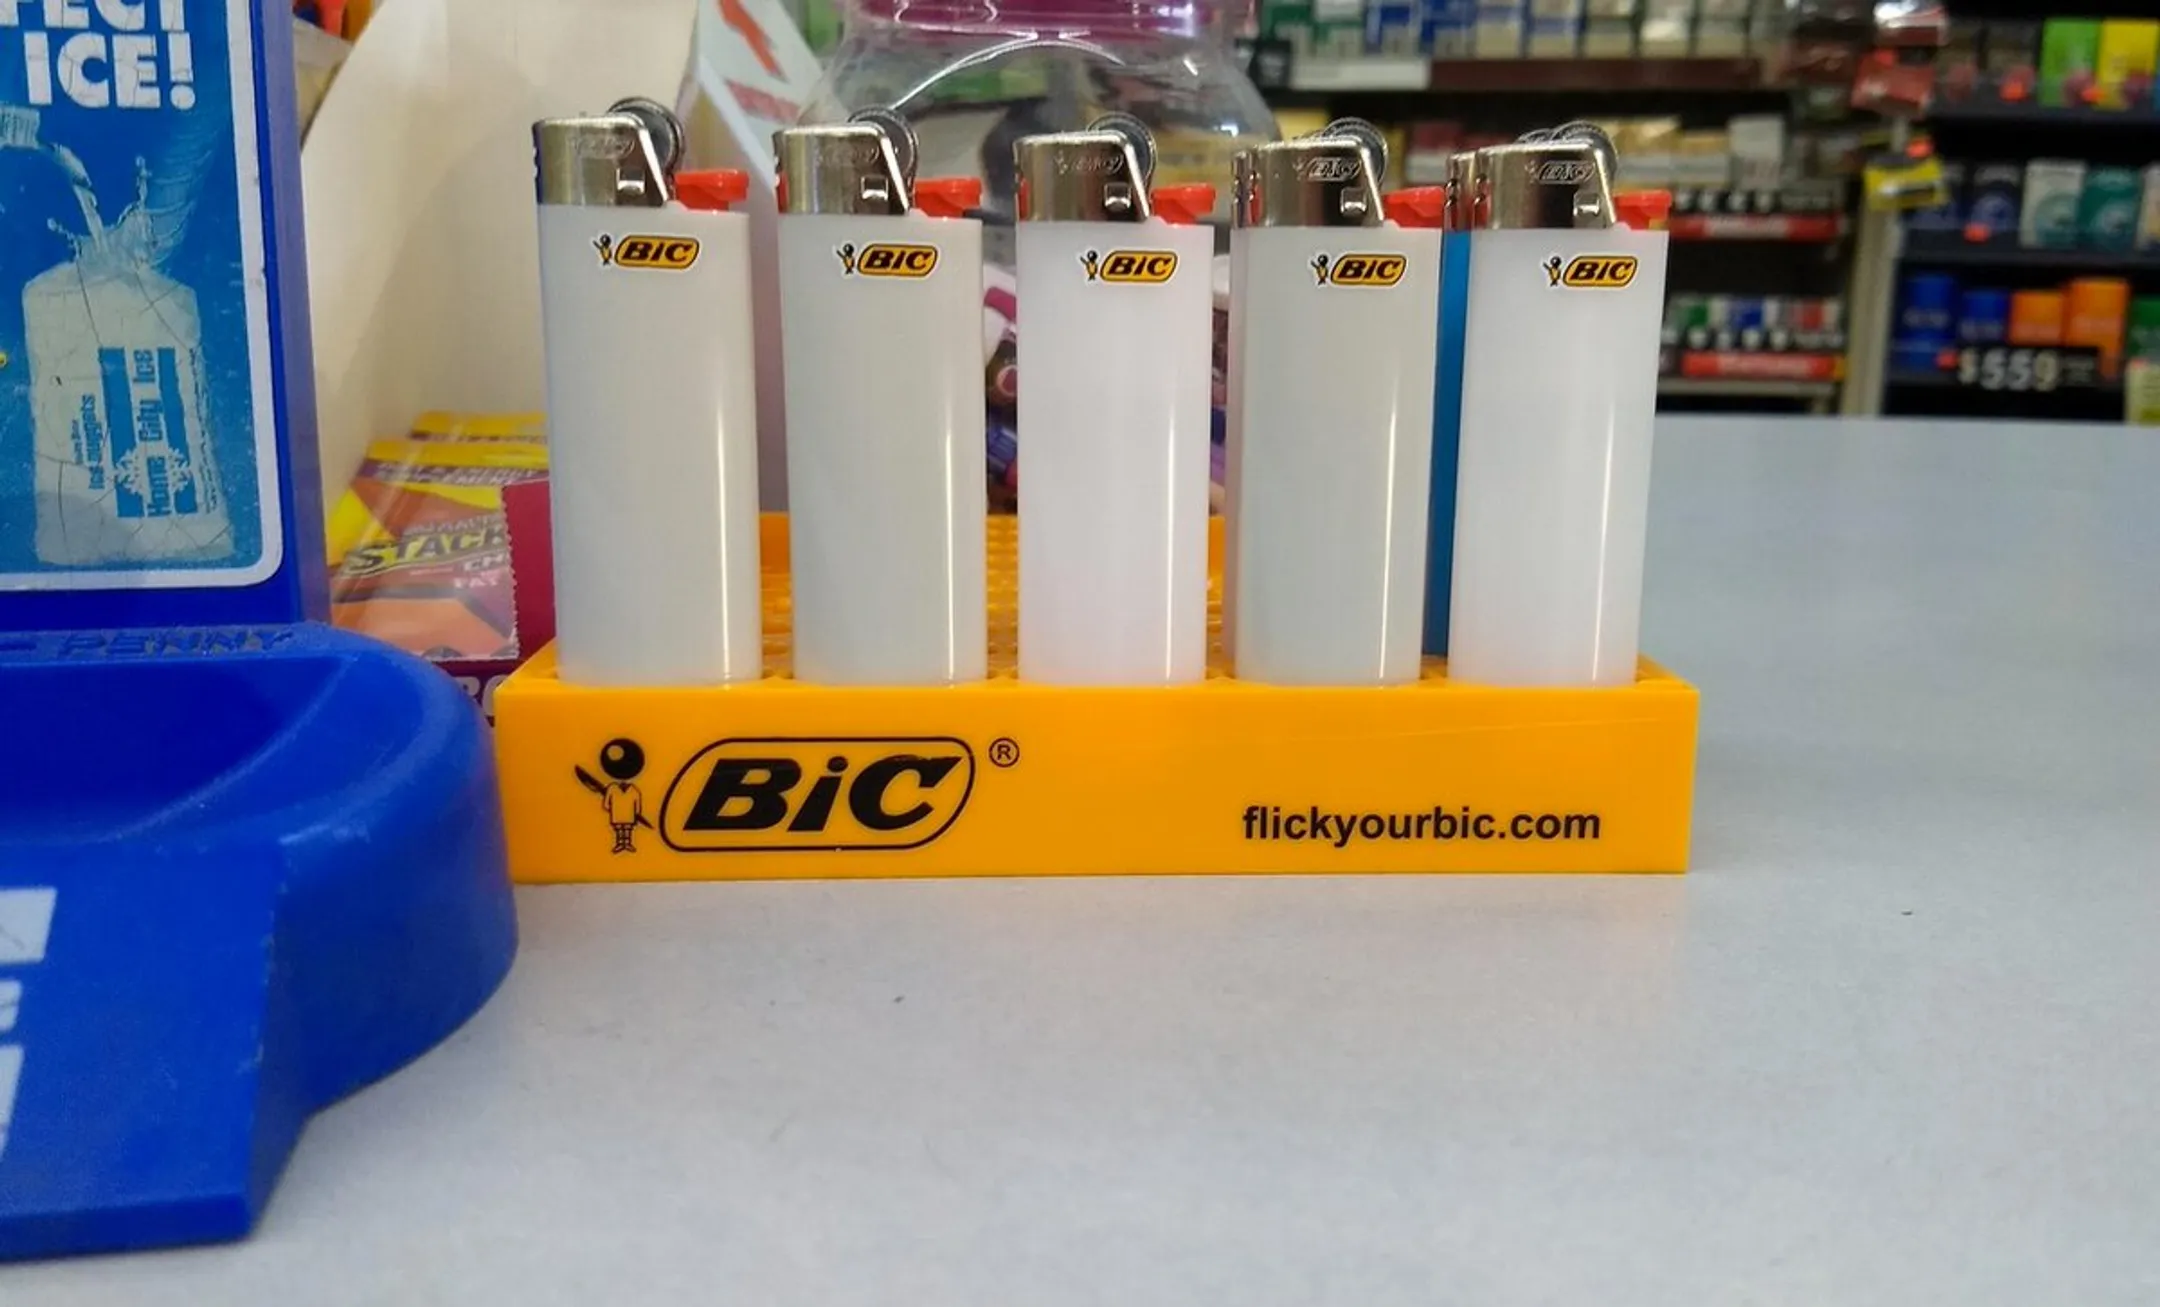
6 Things Worth Knowing About BIC Lighter’s Financial Empire
The BIC lighter’s financial story is a mix of brilliant engineering, ruthless business strategy, and family control. Unlike tech startups with transparent valuations, BIC operates in the shadows of corporate France, where lighters are just one piece of a $3 billion annual revenue puzzle. Here’s what the numbers—and the lack of them—reveal.1. The Lighter Division’s Revenue: A Hidden Fortune
BIC’s lighter division generates hundreds of millions annually, though exact figures are never disclosed. The company’s 2022 financial report lists "lighters and similar products" under a broader category, making it impossible to isolate the lighter’s earnings. However, industry estimates suggest the division contributes $300–500 million yearly, with 80% of global disposable lighter sales. This dominance isn’t just about volume—it’s about profit margins. A single BIC lighter sells for $3–$7, while production costs hover around $0.20. That 3,500% markup funds BIC’s expansion into razors, pens, and even disposable vape devices. The lighter’s profitability is further amplified by bulk discounts. Retailers like Walmart or Costco buy BIC lighters in millions at a time, locking in long-term contracts that ensure steady revenue. Unlike premium brands that rely on luxury pricing, BIC’s strategy is sheer volume. The company’s ability to sell 6 billion lighters a year—more than one for every two people on Earth—means even small per-unit profits add up to hundreds of millions annually. This is why BIC lighter net worth is often discussed in terms of market share, not just dollars.2. The Family Dynasty Behind the Flame
BIC was founded in 1945 by Marcel Bich, a French industrialist who saw an opportunity in mass-producing disposable razors and lighters. Today, the company is controlled by the Bich family, with Brunello Cucinelli (a former BIC executive) and André Bich’s descendants holding significant stakes. The family’s private ownership means no public stock sale—unlike competitors like Zippo, which trades on the NYSE. This opacity extends to BIC lighter net worth, which is never broken down in public filings. The family’s influence is subtle but profound. BIC’s no-frills approach—relying on functionality over design—reflects Marcel Bich’s philosophy: "The simpler, the better." This mindset extends to finance. The company reinvests profits rather than pay dividends, ensuring growth over short-term gains. The lighter division, in particular, benefits from this long-term strategy. While competitors chase premium markets, BIC doubles down on affordability, ensuring its lighters remain the default choice for billions. This consistency is why BIC lighter net worth isn’t just about current sales—it’s about decades of brand loyalty.3. Manufacturing Secrets: Why BIC’s Lighters Are Unbeatable
BIC’s lighter dominance isn’t just about marketing—it’s about engineering. The company holds over 1,000 patents related to lighter technology, including butane ignition systems and safety mechanisms. These innovations allow BIC to produce lighters at scale, with 99% reliability—a figure unmatched by competitors. The lighter’s $0.20 production cost is a result of vertical integration: BIC owns factories in France, Germany, and the U.S., controlling everything from butane supply to metal stamping. This supply chain control is a major reason why BIC lighter net worth is harder to replicate. Competitors like Zippo rely on outsourced manufacturing, driving up costs. BIC, meanwhile, cuts out middlemen, ensuring consistent quality and pricing. The lighter’s modular design—where parts are interchangeable—further reduces costs. This efficiency is why BIC can sell lighters for less than competitors while maintaining higher profit margins. The result? A self-sustaining business that doesn’t need flashy marketing—just sheer volume.4. The Lighter’s Global Monopoly: Why No One Can Touch It
BIC controls 80% of the global disposable lighter market, a figure that hasn’t budged in decades. This monopoly isn’t accidental—it’s the result of aggressive pricing, supply chain dominance, and cultural penetration. In emerging markets, where disposable incomes are low, BIC’s $1–$3 lighters outsell premium brands. Even in developed economies, the lighter’s ubiquity—found in gas stations, supermarkets, and even airplane safety kits—ensures steady demand. The lighter’s global reach is another factor in its financial resilience. BIC operates in 160 countries, with localized production to avoid tariffs. This decentralized manufacturing means the company can adapt to regional demand without losing efficiency. For example, Asia accounts for 40% of BIC’s lighter sales, while Europe and North America contribute another 30%. This geographic diversification ensures that BIC lighter net worth isn’t dependent on any single market. Even during economic downturns, lighters remain a staple purchase, making the division recession-proof.5. The Dark Side of BIC’s Empire: Lawsuits and Controversies
BIC’s financial success hasn’t been without legal challenges. The company has faced lawsuits over patent infringement, counterfeit markets, and even safety recalls. In 2018, BIC settled a $10 million lawsuit in the U.S. over defective lighters that allegedly caused fires. While these incidents are rare, they erode trust—something BIC can’t afford given its $10 billion brand value. The lighter division, in particular, is highly scrutinized due to its global distribution. Another issue is counterfeiting. BIC estimates that 30% of lighters sold in some markets are fakes, cutting into legitimate revenue. The company has cracked down on counterfeiters in China and Southeast Asia, but the problem persists. These unauthorized sales don’t just hurt profits—they dilute the brand’s premium positioning. For a company where BIC lighter net worth is tied to perceived quality, counterfeits are a double-edged sword: they drive down prices but also undermine trust.6. The Future: Can BIC’s Lighter Empire Last?
BIC’s lighter division faces two major threats: electronic alternatives and regulatory crackdowns. E-cigarettes and USB lighters are gaining traction, particularly among younger consumers. While BIC has entered the vaping market, its disposable lighter dominance is under pressure. Additionally, stricter butane regulations in some countries could increase production costs, squeezing margins. Yet BIC’s adaptability is its greatest asset. The company has expanded into razors, pens, and even disposable cameras, diversifying revenue streams. The lighter, meanwhile, remains a cash cow—one that funds innovation in other areas. Analysts predict that BIC lighter net worth will remain stable for decades, thanks to brand loyalty and global demand. However, if electronic lighters become mainstream, BIC may need to reinvent itself—something it’s done before.
How These Facts Connect
BIC’s lighter empire isn’t just about selling flames—it’s about controlling an industry. The company’s vertical integration, family ownership, and global monopoly create a self-sustaining financial machine. While competitors like Zippo rely on niche markets, BIC dominates through sheer scale. This is why BIC lighter net worth is often discussed in terms of market share, not just dollars: the lighter’s $0.20 production cost and $5 retail price ensure hundreds of millions in annual profits, even without flashy growth. The lighter’s cultural and economic power is unmatched. It’s cheaper than a coffee, yet more reliable than a match. This duality—being both a daily necessity and a status symbol—makes it immune to economic cycles. Even in post-pandemic austerity, people will always need a lighter. BIC’s ability to reinvest profits rather than pay dividends ensures long-term dominance. The result? A financial fortress where the lighter remains the cornerstone of BIC’s empire.| Key Factor | Impact on BIC Lighter Net Worth | Industry Comparison |
|---|---|---|
| Global Market Share (80%) | Hundreds of millions in annual revenue | Zippo: ~5% market share |
| Vertical Integration (Own Factories) | Low production costs ($0.20 per lighter) | Competitors outsource, increasing costs |
| Family Ownership (No Public Disclosure) | No pressure to break down lighter division profits | Zippo’s public filings show razor-thin margins |
| Cultural Ubiquity (Default Choice) | Recession-proof demand | Premium lighters (e.g., Storm) see cyclical sales |

Conclusion
BIC’s lighter isn’t just a product—it’s a financial ecosystem. The brand’s $10 billion valuation is built on centuries of engineering, ruthless efficiency, and global dominance. While BIC lighter net worth remains partially obscured by corporate secrecy, its hundreds of millions in annual profits speak for themselves. The lighter’s $0.20 production cost and $5 retail price create a self-funding machine, one that outlasts trends. Yet the real story isn’t just about dollars and cents—it’s about control. BIC owns its supply chain, dominates its market, and reinvests profits rather than chase short-term gains. This long-term strategy is why the lighter remains untouchable, even as electronic alternatives rise. For now, BIC’s flame burns brighter than ever—and its financial empire shows no signs of fading.Comprehensive FAQs
Q: How much is the BIC lighter division worth on its own?
BIC’s lighter division is never disclosed separately in financial reports. Industry estimates suggest it could be worth hundreds of millions independently, given its $300–500 million in annual revenue and 80% global market share. However, the true figure is buried within BIC’s consolidated financials, making an exact valuation impossible.
Q: Does BIC make more money from lighters or razors?
While razors and pens contribute significantly to BIC’s $3 billion annual revenue, the lighter division remains one of its most profitable. Razors benefit from subscription models (like Gillette), but lighters rely on sheer volume—selling 6 billion units yearly at 3,500% margins. Exact comparisons are difficult, but lighters are likely more stable due to universal demand.
Q: Why doesn’t BIC disclose the lighter division’s profits?
BIC is a privately controlled family business, meaning it doesn’t need to break down divisions like public companies. The Bich family’s ownership allows for opaque financial reporting, particularly for core products like lighters. This secrecy is common in European conglomerates, where long-term strategy often takes precedence over shareholder transparency.
Q: Are there any competitors that could challenge BIC’s lighter monopoly?
Several brands compete in niche markets, but none threaten BIC’s global dominance. Zippo holds ~5% market share with premium pricing, while Storm appeals to collectors. However, electronic lighters (like USB models) are the biggest long-term threat. BIC has entered this space, but its disposable lighter empire remains largely untouched for now.
Q: How does BIC’s lighter pricing compare to competitors?
BIC’s $3–$7 price point is far below premium brands (like Zippo’s $20–$50) but higher than generic knockoffs. The $0.20 production cost allows BIC to underprice competitors while maintaining higher profit margins. This affordability is a key reason for its 80% market share—people choose BIC for reliability, not luxury.
Q: What’s the biggest threat to BIC’s lighter business?
The rise of electronic lighters is the most immediate challenge, particularly among younger consumers. However, BIC’s global supply chain and brand loyalty make it resilient. A bigger long-term risk is regulatory crackdowns on butane—if production costs rise, margins could shrink. For now, though, no single threat appears capable of dethroning BIC’s lighter empire.
