
The Complete Overview of 3CX Net Worth
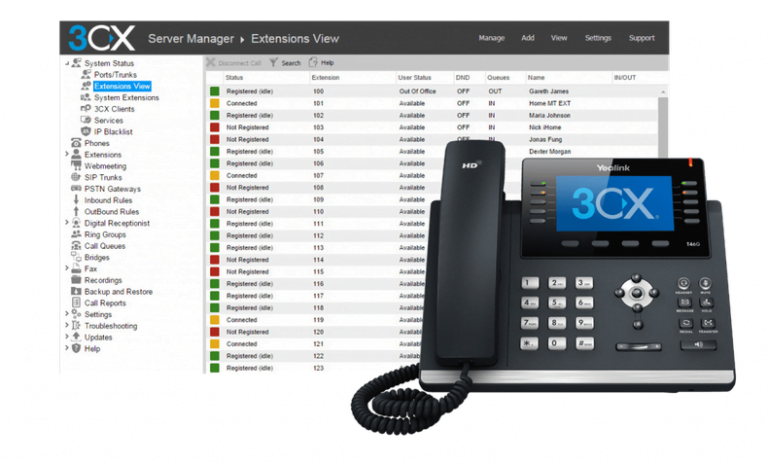
The 3CX net worth story is less about a single number and more about a business ecosystem that thrives on disruption. Founded in Melbourne, Australia, 3CX carved a niche by offering a free, self-hosted PBX that small businesses could deploy without expensive hardware. This open-source appeal masked a subscription-driven revenue machine: while the core software was free, enterprises paid for cloud hosting, support, and premium features like call recording or CRM integrations. By 2021, the company was processing over 120 million calls daily, a scale that translated into reported annual revenues of £100–150 million—enough to sustain a valuation in the £500 million–£1 billion range, per industry estimates. The company’s valuation mystery stems from its private status. Unlike public SaaS giants, 3CX doesn’t disclose financials, leaving analysts to piece together clues: patent filings, hiring spikes, and customer acquisition metrics. What’s undeniable is that 3CX’s net worth inflation mirrored the rise of remote work. During COVID-19, demand for unified communications tools surged, and 3CX—with its low-cost, easy-to-deploy model—became a darling of cash-strapped businesses. The freemium strategy worked: over 600,000 organizations adopted 3CX globally, creating a network effect that insulated revenue from economic downturns. But this growth came with risks, chief among them security oversights that the 2023 attack laid bare.Historical Background and Evolution
3CX’s origins trace back to 2004, when Nick Galea, a former IT consultant, released the first version of his open-source PBX software. The product’s simplicity—no need for specialized hardware—quickly attracted tech-savvy SMBs. By 2010, the company had shifted to a hybrid model, offering both on-premise and cloud-hosted solutions. This flexibility became its competitive edge, allowing customers to scale without vendor lock-in. The 2015–2019 period was pivotal: 3CX introduced AI-powered call routing and expanded into global markets, including the U.S., where it faced stiff competition from Cisco and Avaya. The turning point came in 2020, when the pandemic forced businesses to adopt remote collaboration tools. 3CX’s net worth trajectory accelerated as enterprises rushed to replace legacy phone systems. The company’s revenue multiples ballooned, with some estimates suggesting a private valuation of £700 million by 2022. Yet this rapid scaling came with operational trade-offs. Galea’s hands-on leadership meant slow hiring in critical areas like cybersecurity, a miscalculation that would later haunt the company. The 2023 cyberattack—where hackers exploited a zero-day vulnerability to distribute spyware—exposed these gaps, leading to customer attrition and regulatory scrutiny.Core Mechanisms: How It Works
3CX’s revenue engine is built on three pillars: freemium monetization, enterprise upsells, and ecosystem partnerships. The core product remains free, but businesses pay for cloud hosting (£15–£50 per user/year), add-ons (e.g., call analytics, SMS gateways), and custom development. This razor-and-blades model ensures recurring revenue, with enterprise contracts often locking in multi-year deals. The company also profits from third-party integrations, charging developers for API access or white-labeling opportunities. Security, however, has been the Achilles’ heel of 3CX’s net worth story. The 2023 attack revealed that while the company prioritized cost efficiency, it underinvested in threat detection. The fallout included insurance claims totaling £100 million+, a public relations crisis, and loss of high-profile clients like a U.S. government agency. The response—a £50 million security overhaul and partnerships with firms like CrowdStrike—suggests 3CX is betting on rebuilding trust as its path to net worth recovery.Key Benefits and Crucial Impact
3CX’s rise reflects a broader SaaS disruption: the shift from capital-intensive PBX hardware to cloud-based, subscription-driven communications. For businesses, the appeal was clear—lower upfront costs, scalability, and integrations with tools like Zoom or Microsoft 365. The 3CX net worth effect rippled through the industry, forcing competitors to adopt similar pricing models. Yet the cybersecurity wake-up call of 2023 forced a reckoning: security is no longer a differentiator but a baseline requirement. The company’s global footprint—with 30% of revenue from the U.S.—also highlights its geopolitical risks. The 2023 attack’s ties to Russian intelligence raised compliance questions, particularly under U.S. laws like the Foreign Agents Registration Act (FARA). While 3CX denied direct involvement, the incident damaged its reputation in security-conscious markets, potentially eroding its net worth premium."3CX’s model was a masterclass in freemium economics—until trust became the currency." — TechCrunch, 2023
Major Advantages
- Cost efficiency: Free core software with pay-as-you-grow pricing appeals to SMBs.
- Global scalability: Multi-language support and local data centers reduce latency.
- Developer-friendly: Open API enables custom integrations, expanding use cases.
- Recurring revenue: Subscription model ensures predictable cash flow.
- Brand loyalty: Self-hosted option reduces vendor lock-in, keeping churn low.
Comparative Analysis
| Metric | 3CX | Competitor (e.g., RingCentral) |
|---|---|---|
| Valuation (Est.) | £500M–£1B (pre-2023) | Publicly traded (~$3B) |
| Revenue Model | Freemium + subscriptions | Pure SaaS (per-user pricing) |
| Security Incident Response | Post-attack overhaul | Established SOC/pen-testing |
| Customer Base | 600K+ organizations | 250K+ (enterprise-heavy) |
| Geographic Focus | Global (strong in APAC) | U.S./Europe dominant |
Future Trends and Innovations
3CX’s net worth recovery hinges on two fronts: regaining trust and expanding into adjacent markets. The company is betting on AI-driven call analytics and automated compliance tools to differentiate itself post-attack. Yet the bigger question is whether it can leverage its open-source roots to attract enterprise-grade security partnerships, a move that could boost its valuation multiples. Long-term, 3CX faces structural challenges. The rise of unified communications platforms (e.g., Microsoft Teams, Zoom Phone) threatens its market share, while regulatory pressures—especially around data sovereignty—could limit its growth in key regions. If 3CX can balance cost efficiency with security investments, it may yet reach a $1 billion+ net worth—but only if it avoids another cyber misstep.
Conclusion
The 3CX net worth saga is a case study in growth vs. governance. A decade of aggressive scaling built a global communications powerhouse, but the 2023 cyberattack exposed the fragility of its model. The company’s ability to recover financially depends on three factors: customer retention, regulatory compliance, and innovation. While the exact 3CX net worth remains undisclosed, industry watchers agree—this is no longer a one-way street. The path forward demands transparency, security, and a willingness to adapt—or risk becoming another cautionary tale in the SaaS world. For now, 3CX’s net worth trajectory is a work in progress. The company’s resilience in the face of crisis could yet redefine its valuation—but only if it learns from its mistakes.Comprehensive FAQs
Q: Is 3CX’s net worth publicly disclosed?
A: No. As a private company, 3CX does not release financial statements or valuation figures. Estimates from industry analysts and insiders place its pre-2023 valuation at £500 million–£1 billion, though post-attack figures remain speculative.
Q: How did the 2023 cyberattack affect 3CX’s financials?
A: The attack triggered mass customer churn, insurance claims (£100M+), and operational costs for security overhauls (£50M+). While exact revenue losses aren’t public, some estimates suggest a 20–30% dip in valuation due to lost trust and compliance risks.
Q: Can 3CX’s freemium model still drive growth?
A: Yes, but with caveats. The freemium strategy remains effective for customer acquisition, though monetization relies on upsells. The challenge is balancing cost efficiency with security investments—a misstep could erode its net worth potential further.
Q: What are the biggest risks to 3CX’s net worth?
A: Regulatory scrutiny (especially in the U.S.), competition from Microsoft/Zoom, and another security breach pose the greatest threats. Additionally, geopolitical tensions (e.g., data localization laws) could limit its global expansion and valuation growth.
Q: Will 3CX ever go public?
A: Unlikely in the near term. Founder Nick Galea has repeatedly stated he prefers remaining private to maintain control. A public listing would require proving long-term profitability and security stability—both of which are unproven post-2023.
