
Where It All Began
The origins of net present worth vs e trace back to the 1960s, when the first NPV models were weaponized by corporate raiders and government planners. The theory was elegant: discount future cash flows to today’s dollars, and you’d know whether an investment was worth pursuing. But the models assumed markets were frictionless, people were rational, and time moved in a straight line. In practice, none of these held. The first cracks appeared in the 1970s, when economists like Robert Merton began documenting how real-world decisions deviated from theoretical expectations. Yet the gap between NPV’s promise and its performance remained invisible to most practitioners—until the 1990s, when hedge funds started treating e as a tradable variable. The early signs were subtle. A 1995 study in the Journal of Finance noted that private equity firms consistently overpaid for assets by 12–18% when using NPV alone, yet still delivered outsized returns. The explanation? They weren’t just chasing NPV; they were betting on e—the ability to exploit regulatory arbitrage, manipulate earnings forecasts, or outlast competitors in a zero-sum game. The problem wasn’t the math. It was that the math had a blind spot.The Early Signs
By the late 1990s, the net present worth vs e tension had seeped into mainstream finance. BlackRock’s early risk models, for instance, included a "behavioral decay" adjustment—essentially an e term—to explain why some high-NPV projects failed while others, with lower NPV scores, succeeded. The dot-com bubble exposed the flaw in its most brutal form: companies with negative NPV (by traditional metrics) were trading at stratospheric valuations because investors believed in the e of network effects and first-mover advantage. When the bubble burst, the question shifted from whether to account for e to how to quantify it. The real turning point came in 2005, when a group of ex-Goldman Sachs quants, frustrated by the firm’s reliance on NPV for M&A, began publishing papers under pseudonyms. Their argument? NPV was a tool for static markets. In dynamic ones—where power shifts, technologies disrupt, and emotions drive decisions—the e factor dominated. The memo that went viral in 2008 wasn’t just a critique. It was a manual for how to weaponize e."NPV is the language of accountants. e is the language of empire. You can’t build the future with the past’s grammar." — Anonymous quant, 2008 internal memo (leaked to Risk.net)
The Turning Point
The financial crisis didn’t resolve the net present worth vs e debate—it made it personal. Banks that had relied on NPV to justify toxic assets suddenly found themselves holding worthless paper, while firms that had bet on e (e.g., distressed debt arbitrageurs) thrived. The crisis revealed that e wasn’t just a correction term. It was the operating system of modern finance. By 2012, private equity firms were openly discussing e-adjusted IRRs in pitch books, and sovereign wealth funds began hiring behavioral economists to stress-test NPV models for e exposure. The shift wasn’t just tactical. It was philosophical. Traditional finance treated e as noise. The new orthodoxy treated it as the signal. The question was no longer how much does e distort NPV? but what does e tell us that NPV can’t?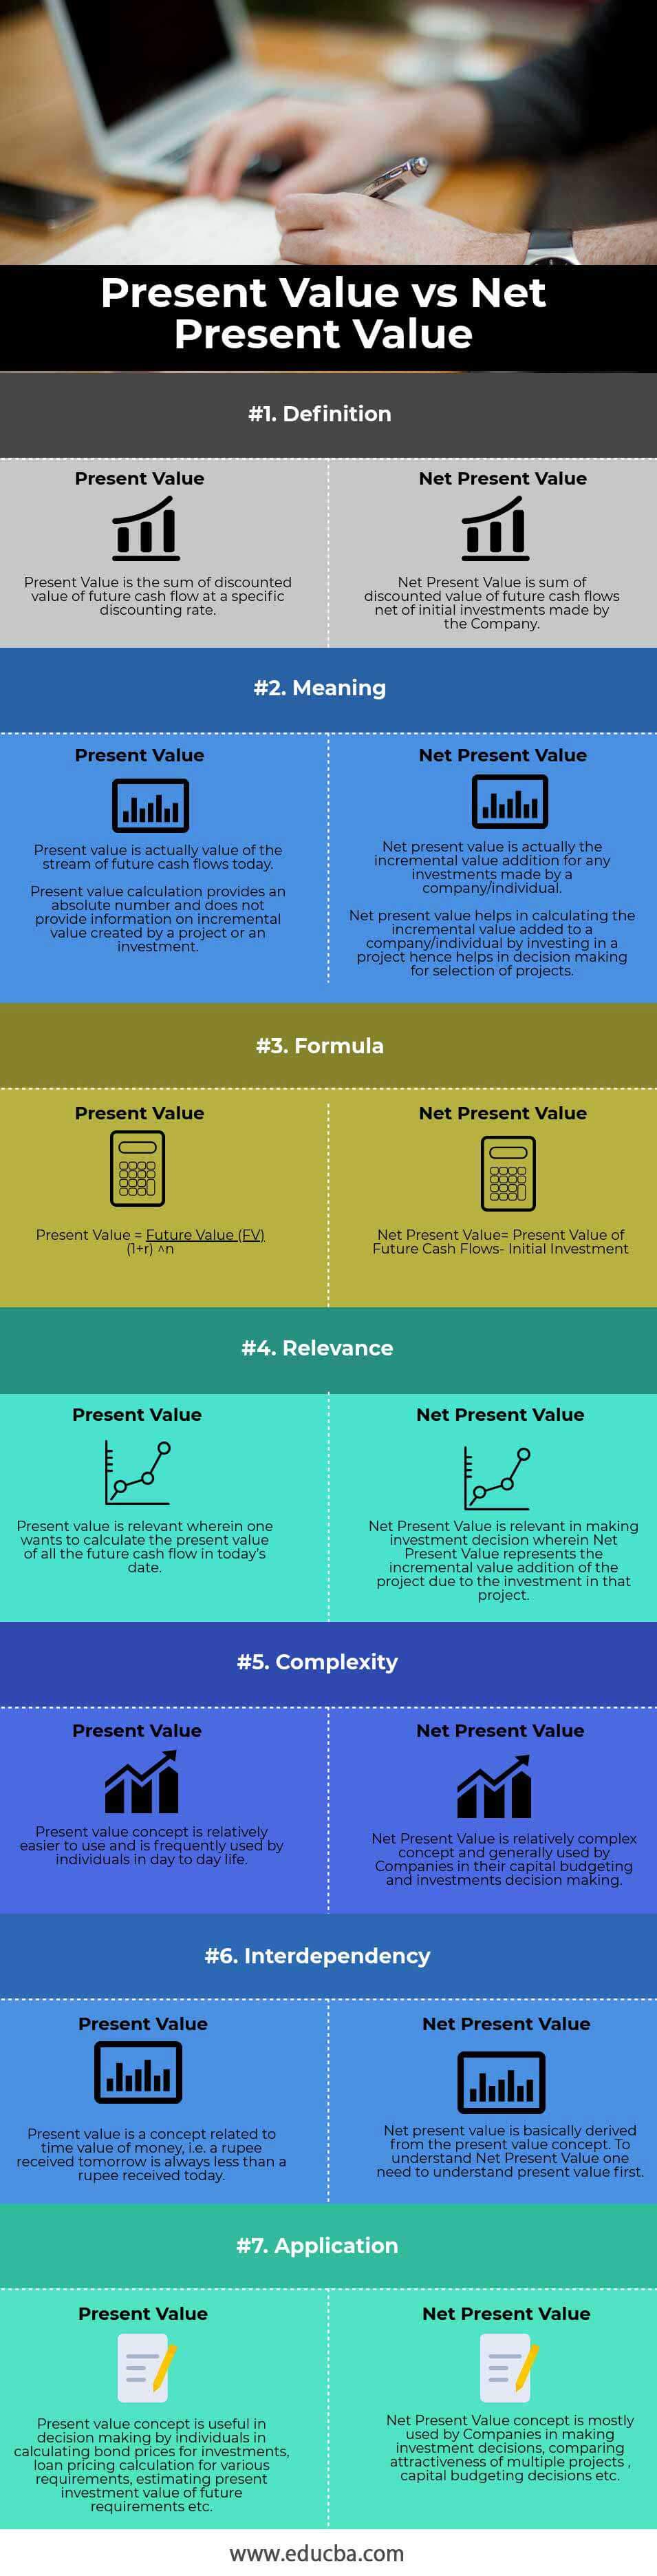
The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 1960s–1970s | NPV becomes the dominant valuation tool in corporate finance. Early critiques (e.g., Merton’s work on incomplete markets) note gaps but are dismissed as niche. |
| 1990s | Hedge funds and private equity firms begin treating e as a strategic variable. Behavioral finance gains traction, but e remains implicit in models. |
| 2000–2008 | Dot-com bubble and crisis expose NPV’s fragility. The e factor is retroactively blamed for mispricing. Quants start modeling e explicitly. |
| 2010–Present | e becomes a formal part of risk-adjusted return calculations. Regulatory arbitrage and ESG factors are reframed as e drivers. NPV is now a subset of a broader "net present worth" framework. |
Lessons From the Journey
- NPV was never neutral. It was designed for stable environments. e thrives in chaos.
- The more complex the system, the harder e is to isolate—but the more it matters.
- Institutions that ignore e don’t fail because of bad math. They fail because they misunderstand power.
- e isn’t just a correction. It’s the mechanism by which value is created (or destroyed) in the real world.
Where Things Stand Today
The net present worth vs e debate has evolved into a three-way tug-of-war. On one side are the purists—academics and traditional asset managers who still treat NPV as the gold standard, arguing that e is unmeasurable noise. On the other are the pragmatists: hedge funds, sovereign wealth funds, and family offices that now run dual models, one NPV-based and one e-adjusted. The third camp, still growing, are the disruptors—firms like Bridgewater or AQR—that have folded e into their core valuation frameworks, treating it as a tradable premium. The result? A finance industry where the most successful players aren’t just optimizing for NPV. They’re optimizing for net present worth—a hybrid metric that accounts for both the predictable and the unpredictable. The catch? There’s no consensus on how to measure e. Some use Monte Carlo simulations with behavioral overlays. Others rely on historical stress-test data. A few still treat it as an art, not a science.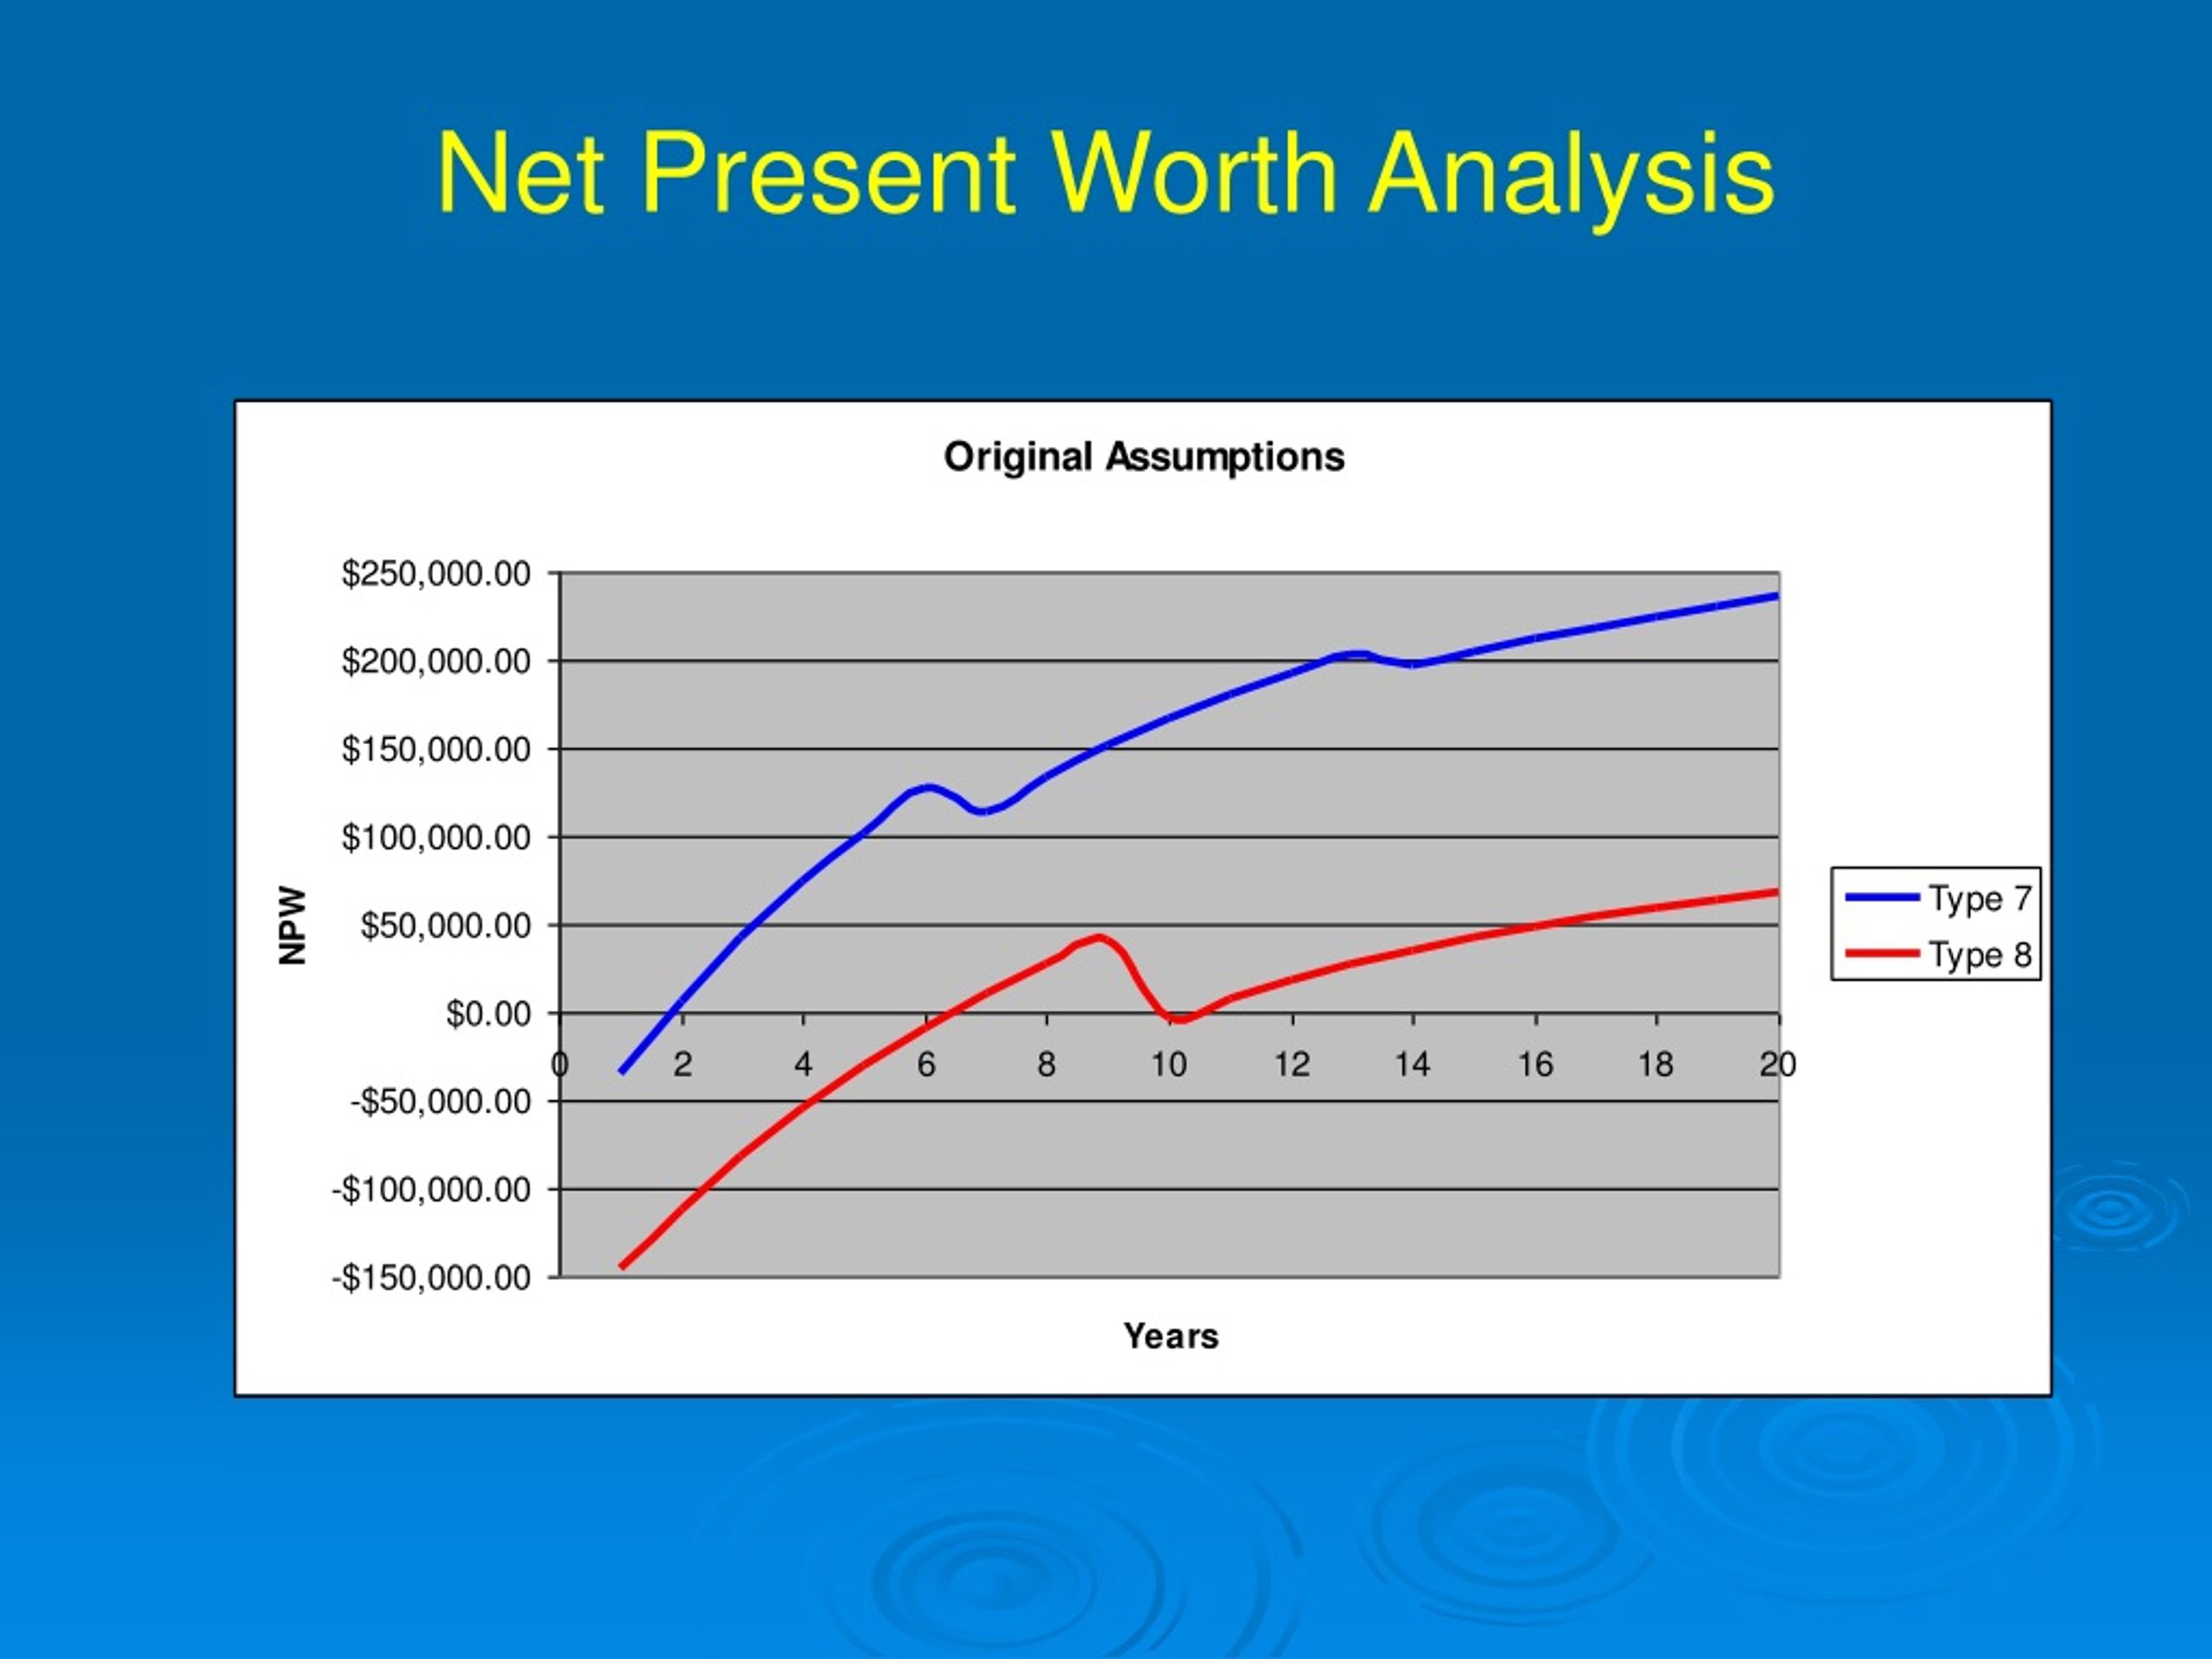
Conclusion
The net present worth vs e divide isn’t going away. If anything, it’s deepening. The reason? Because the gap between theory and practice has never been wider. NPV gives you a destination. e tells you whether you’ll arrive—and what you’ll find when you do. The firms that win in the next decade won’t be the ones with the best NPV models. They’ll be the ones who understand that e isn’t a bug. It’s the feature that separates the visionaries from the followers. The irony? The more e dominates, the more NPV’s limitations become obvious. But the more NPV’s limitations become obvious, the harder it is to escape its gravitational pull. The debate isn’t about which side is right. It’s about who’s willing to bet on the future—even when the numbers don’t add up.Comprehensive FAQs
Q: Is e just another name for "risk premium"?
A: Not exactly. A risk premium accounts for known uncertainties (e.g., volatility, liquidity). e captures unknowns—regulatory shifts, cultural trends, or even the whims of a single decision-maker. Think of it as the premium for operating in a world where the rules aren’t just unclear, but actively being rewritten.
Q: Can e be quantified?
A: Partially. Some firms use historical e factors (e.g., the average deviation between NPV projections and actual outcomes) to backtest models. Others employ scenario analysis with behavioral economics inputs. The challenge is that e is path-dependent—its impact changes based on market regime, power dynamics, and even the time of day a trade is executed.
Q: Why do traditional asset managers ignore e?
A: Three reasons: (1) Regulatory comfort: NPV is auditable; e is not. (2) Cultural inertia: Many firms’ compensation structures reward NPV alignment over e awareness. (3) Short-termism: e’s effects are often long-term, while quarterly earnings reports demand immediate answers. Ignoring e is a feature, not a bug, for firms optimized for stability over disruption.
Q: Are there industries where e matters more than others?
A: Yes. In private equity, e dominates because control allows firms to shape outcomes beyond NPV. In tech, e is critical due to network effects and regulatory uncertainty. In commodities, e is often tied to geopolitical risk. Traditional industries like utilities see e as less relevant—but that’s because they’ve already priced it into their cost structures as "strategic reserves."
Q: How do hedge funds use e in practice?
A: Most don’t call it e. They might refer to it as "tail-risk exposure," "regime-shift arbitrage," or "optionality." A distressed debt fund, for example, might use NPV to price a bond but bet on e—the chance of a government bailout, a legal loophole, or a competitor’s collapse—to amplify returns. The key is treating e as a lever, not a hedge.
Q: Can e be negative?
A: Absolutely. Negative e occurs when systemic drag—regulatory overreach, cultural backlash, or even bad luck—erodes value faster than NPV predicts. A classic example is the collapse of Enron, where e (in the form of accounting fraud and hubris) turned a high-NPV play into a zero-sum game. Negative e is why some "can’t-lose" investments still fail spectacularly.
Q: Is net present worth just NPV + e?
A: In theory, yes. In practice, no. Net present worth is a framework, not a formula. It forces practitioners to ask: What does NPV assume that isn’t true? and Where does e hide in the system? Some firms treat it as a single metric; others use it to build a decision matrix. The goal isn’t to replace NPV but to acknowledge that e is the variable that turns good decisions into great (or terrible) outcomes.
Q: What’s the biggest misconception about e?
A: That it’s only relevant for "high-risk" investments. The truth? e is most dangerous in "low-risk" ones—where its absence lulls decision-makers into false confidence. A municipal bond with a pristine NPV can still fail if e (e.g., pension liabilities, political corruption) isn’t accounted for. The higher the conviction in the NPV, the harder the e shock when it hits.
