7 Things Worth Knowing About Annual Income vs Liquid Net Worth
The two metrics don’t just coexist; they often contradict. Understanding their dynamics redefines how you assess wealth—and how others perceive it.1. Annual income is a snapshot; liquid net worth is a reservoir
A paycheck represents income in transit, subject to taxes, deductions, and volatility. Liquid net worth, by contrast, is the sum of cash, easily tradable assets, and low-illiquidity holdings you can convert within 90 days. The former fluctuates with market cycles, career shifts, or industry downturns; the latter reflects your ability to weather those shocks. A surgeon earning $500,000 annually might have a liquid net worth of $200,000 after student loans, malpractice insurance, and a mortgage—while a retired teacher on a $60,000 pension could have $1.2 million in liquid assets from decades of frugality. The disconnect becomes stark in crises. During the 2008 financial collapse, high earners with illiquid assets (like real estate or private equity) faced foreclosures or forced sales, while those with diversified liquid portfolios simply rode out the storm. Income doesn’t protect you from illiquidity—only assets do.2. Liquidity determines survival; income determines lifestyle
You can live on a salary. You can’t survive without liquidity. A $200,000 annual income might fund a penthouse in Manhattan, but if your net worth is tied to a single property or a struggling business, a 20% market correction could evaporate your security overnight. Conversely, a $100,000 income with $500,000 in cash, bonds, and low-correlation investments offers financial autonomy—the ability to pause, pivot, or endure without selling soul. This is why billionaires like Warren Buffett and Jeff Bezos—despite earning "only" $100 million annually in recent years—remain among the most liquid individuals on Earth. Their wealth isn’t in paychecks; it’s in assets they can deploy instantly. The lesson? Income buys options; liquidity buys freedom.3. The wealth gap isn’t just about earnings—it’s about extraction
High earners often underestimate how much of their income is extracted before it ever hits their bank account. A $300,000 salary in New York City might yield $200,000 after taxes, student loans, childcare, and healthcare premiums—leaving little for liquid asset accumulation. Meanwhile, someone earning $120,000 in Texas with no debt could save $80,000 annually and invest it systematically. The result? Over a decade, the lower earner might build a liquid net worth 3x higher than the higher earner, despite taking home less. This isn’t just math; it’s structural. Wealth extraction—through taxes, fees, and lifestyle inflation—disproportionately targets high earners who lack liquid buffers. The solution isn’t earning more; it’s optimizing what you keep.4. Illiquid assets can be wealth traps
A $5 million home isn’t liquid wealth—it’s a liability disguised as an asset. Selling it costs 6% in commissions, capital gains taxes, and moving expenses. A private business stake, art collection, or rental property might appreciate on paper, but converting them to cash requires time, expertise, and often a fire sale. The ultra-wealthy understand this: Liquid net worth isn’t about owning more; it’s about owning what you can access. Consider the case of a Silicon Valley executive who cashed out a tech IPO for $20 million—only to see 40% tied up in illiquid venture capital holdings. When the market corrected, he faced a choice: sell at a loss or watch his lifestyle erode. The lesson? Paper wealth doesn’t feed you.5. The "liquidity premium" explains why some rich people act poor
A hedge fund manager with a $10 million annual bonus might drive a used car and live in a modest home—while a public school teacher with a $70,000 salary takes annual cruises. The difference? Liquidity allocation. The manager’s income is volatile; his spending must be conservative. The teacher’s income is stable; her liquid net worth allows for discretionary spending without risk. This isn’t irrationality—it’s rational liquidity management. High earners with illiquid portfolios often appear frugal because they can’t afford to miscalculate. Low earners with liquid buffers can afford spontaneity because they’ve already secured their foundation.6. Financial independence hinges on liquidity, not income
You’re "financially independent" when your passive income covers your expenses. But if that income relies on illiquid assets (like rental properties or private equity), a single bad tenant or market shift can unravel years of planning. True financial independence requires liquidity-backed income streams—dividends, interest, or business cash flow that doesn’t depend on selling assets. A retiree with $3 million in stocks and bonds can generate $120,000 annually without touching principal. A retiree with $3 million in a single commercial property might face eviction or a forced sale if the market turns. The first is secure; the second is vulnerable. Income without liquidity is a house of cards.7. The social perception gap is a myth
Most people assume high earners are wealthier. Reality? Liquid net worth often correlates more with social mobility than income. A doctor with a $400,000 salary and $1 million in student loans may appear affluent but is financially constrained. A plumber with a $90,000 income and $500,000 in liquid assets can retire early, buy a business, or weather job loss without stress. This disconnect fuels resentment. High earners with low liquidity resent those who "waste" money on experiences; low earners with high liquidity are dismissed as "lucky." The truth? Wealth visibility is a function of liquidity, not income.
How These Facts Connect
The tension between annual income vs liquid net worth isn’t just numerical—it’s philosophical. Income measures your participation in the economy; liquid net worth measures your autonomy from it. One reflects your role in the system; the other reflects your ability to exit it on your terms. The data reinforces this: across income brackets, those with higher liquid net worth relative to their income enjoy lower stress, greater opportunity, and more resilience. High earners with illiquid assets are hostages to market cycles; low earners with liquid buffers are free agents. The key isn’t earning more—it’s controlling what you earn. | Metric | Annual Income | Liquid Net Worth | |--------------------------|--------------------------------------------|--------------------------------------------| | Primary Function | Funds current spending/lifestyle | Provides emergency cushion & opportunity | | Risk Exposure | Vulnerable to job loss, inflation, taxes | Resilient to market volatility | | Social Perception | Often overestimates wealth | Often underestimates security | | True Measure Of | Participation in economy | Freedom from economic dependence | | Critical Threshold | Enough to cover expenses | Enough to cover 12–24 months of expenses |
Conclusion
The obsession with annual income obscures the harder truth: wealth is liquidity in disguise. You can earn millions and still be broke; you can earn modestly and be rich in options. The distinction matters more than most financial advice acknowledges. The solution isn’t to chase higher salaries—it’s to optimize for liquidity. That means minimizing debt, diversifying assets, and ensuring a portion of your wealth is always accessible. It’s the difference between being a participant in the economy and its master.Comprehensive FAQs
Q: How do I calculate my liquid net worth?
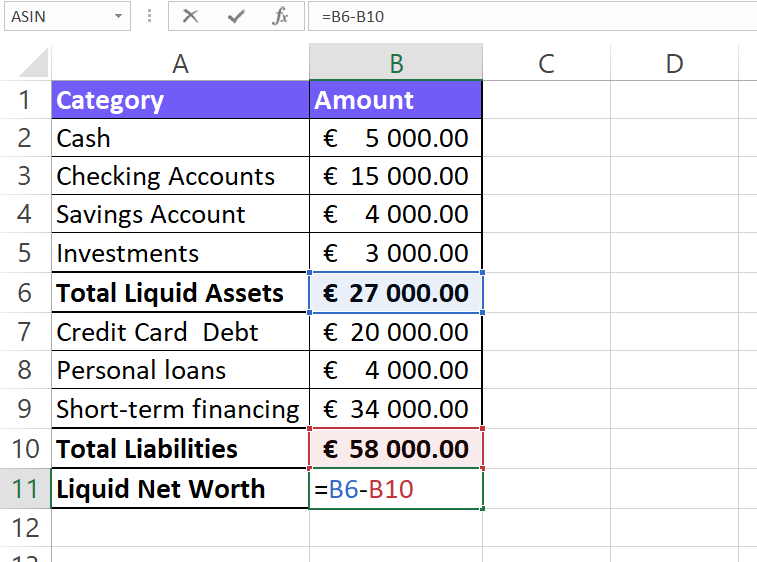
Add up cash, savings, money market funds, publicly traded stocks/bonds, and any assets you can sell within 90 days (e.g., a car, jewelry, or a rental property if the market is active). Subtract all liabilities that aren’t tied to illiquid assets (e.g., credit card debt, but not a mortgage on your primary home). The result is your liquid net worth.
Q: Can I have a high income but negative liquid net worth?
Absolutely. High earners with significant debt (student loans, mortgages, business liabilities), high living expenses, or illiquid investments (like a single property or private equity) often find their liquid net worth eroded despite six-figure incomes. This is common in industries like law, medicine, or tech startups, where upfront costs are high.
Q: Is it better to focus on increasing income or building liquid net worth?
Both matter, but liquidity is the foundation. A 10% increase in income is meaningless if your liquid net worth is negative. Prioritize reducing debt, building cash reserves, and investing in liquid assets before aggressively pursuing higher earnings. Once you have a stable liquid base, income becomes a tool for scaling wealth—not survival.
Q: How much liquid net worth should I aim for?
Financial advisors often recommend 3–6 months of living expenses as a minimum for basic security. For early retirement or true financial independence, aim for 25x your annual expenses in liquid assets (the "Trinity Study" benchmark). However, the exact number depends on your risk tolerance, lifestyle, and income volatility.
Q: Why do some high earners struggle with liquidity despite their income?
Three reasons: (1) Lifestyle inflation—spending rises with income, leaving little for savings; (2) Illiquid investments—assets like real estate or private equity require time/cost to liquidate; (3) Tax and fee drag—high earners often face higher marginal tax rates, investment fees, and mandatory expenses (e.g., alimony, child support). Without discipline, income becomes a treadmill.
Q: Can liquid net worth replace the need for a high income?
Yes, but it requires strategic planning. If your liquid net worth generates enough passive income (dividends, interest, rental yields) to cover your expenses, you can reduce or eliminate earned income. This is the principle behind "FIRE" (Financial Independence, Retire Early). However, it demands frugality, tax efficiency, and a willingness to live below your peak earning potential.
Q: How do I improve my liquid net worth if my income is stagnant?
Focus on asset allocation over income growth:
- Reduce debt—especially high-interest debt like credit cards or personal loans.
- Increase cash flow—cut discretionary spending, negotiate bills, or pursue side income.
- Invest in liquid assets—index funds, ETFs, or short-term bonds offer better liquidity than real estate or private equity.
- Avoid lifestyle creep—when income rises (even modestly), allocate increases to liquid savings first.
Q: Is liquid net worth more important than total net worth?
It depends on your goals. Total net worth matters if you’re measuring long-term wealth accumulation (e.g., retirement planning). Liquid net worth matters if you need flexibility, security, or the ability to act quickly. For most people, both matter—but liquidity is the difference between wealth and vulnerability.
