Common Myths About United States Steel Net Worth
The first misconception treats United States Steel net worth as a static figure, untouched by external forces. In truth, its market value has swung wildly over the past decade, peaking during commodity booms and cratering during downturns. For instance, when steel prices surged in 2021, USS’s stock briefly flirted with valuations near $10 billion—only to retreat as inflation and interest rates squeezed margins. The second myth frames USS as a "zombie" company, propped up by debt and government subsidies. While it’s true the company has carried significant leverage, its debt-to-equity ratios have improved in recent years through asset sales and cost-cutting. The third error is assuming its worth is solely tied to Pittsburgh’s mills; USS’s global operations, including joint ventures in Canada and Europe, contribute meaningfully to its balance sheet. Another persistent myth is that USS’s valuation is purely a function of its physical assets. While its integrated mills in Mon Valley and Gary are undeniably valuable, the company’s United States Steel net worth now includes intellectual property—patents for advanced steel formulations—and its stake in green steel initiatives. These intangibles are harder to quantify but increasingly critical as ESG (environmental, social, and governance) factors reshape investor priorities. Finally, some assume the company’s decline is irreversible, ignoring its strategic pivots into electric arc furnace (EAF) technology and partnerships with automakers transitioning to lightweight steel for EVs.Myth 1: United States Steel net worth is just about its old mills
The narrative of USS as a dinosaur clinging to outdated blast furnaces oversimplifies its asset base. While its legacy facilities in Pennsylvania and Indiana are iconic, they represent only a portion of its total enterprise value. The company’s Mon Valley Works, for example, is a prime example of how USS has modernized: its coke-making plants now incorporate waste-heat recovery systems, and its blast furnaces run on pulverized coal injection (PCI) to improve efficiency. These upgrades aren’t just about compliance—they’re about extending the lifespan of high-cost assets in a world where new greenfield projects are rare. Beyond physical plants, USS’s net worth includes its stake in US Steel Canada, a joint venture that produces high-strength steel for automotive and infrastructure projects. The company also holds patents for specialized steels used in pipelines and renewable energy infrastructure, which are licensed to third parties. These revenue streams diversify its earnings beyond commodity cycles. The mistake lies in fixating on the visible—smokestacks and rolling mills—while overlooking the less tangible but growing contributions to its valuation.Myth 2: The company is insolvent or on the brink of bankruptcy
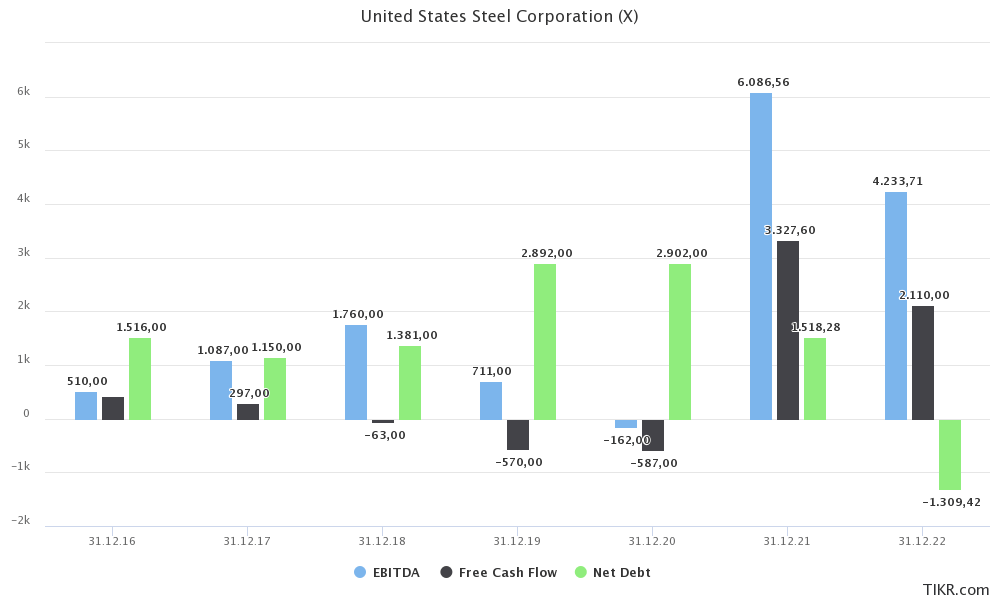
Financial distress is a recurring specter for USS, but its market capitalization tells a different story. While the company has filed for bankruptcy twice (2001 and 2019), both restructurings were strategic moves to shed debt and streamline operations. The 2019 bankruptcy, in particular, allowed USS to exit unprofitable ventures like its European operations while retaining its core U.S. assets. Post-emergence, the company’s debt levels stabilized, and its free cash flow improved as steel prices rebounded. Analysts now view USS as a "distressed recovery" play rather than a perennial ward of the court. That said, the company’s net worth remains vulnerable to macroeconomic shocks. When steel prices collapsed in 2015–2016, USS’s stock traded below $10 per share, erasing billions in market value. Yet even then, the company avoided liquidation by securing long-term contracts with automakers and government infrastructure projects. The key takeaway: USS’s financial health is cyclical, not terminal. Its ability to weather downturns depends on its balance sheet flexibility and access to capital markets—not just the health of its mills.Myth 3: United States Steel net worth is irrelevant in today’s market
Dismissing USS as a relic ignores its role in critical supply chains. The company’s enterprise value is tied to its position as a supplier to sectors like automotive, energy, and defense—all of which are seeing resurgent demand. For example, USS’s partnership with Ford to develop advanced high-strength steel for EVs underscores its relevance in the transition to lightweight materials. Similarly, its contracts with the U.S. Department of Defense for armor-grade steel highlight its strategic importance beyond commodity markets. Moreover, USS’s net worth is a proxy for the broader health of U.S. manufacturing. As China’s steel exports face tariffs and domestic producers like Nucor expand, USS’s ability to compete hinges on its cost structure and innovation pipeline. The company’s investments in hydrogen-based steelmaking (via its Hybrid Energy Transition initiative) signal that it’s not just surviving—it’s positioning itself for a future where carbon-neutral production could command premium prices.
What Holds Up to Scrutiny
At its core, United States Steel net worth is a function of three verifiable pillars: asset quality, operational leverage, and market positioning. USS’s integrated mills, while aging, benefit from economies of scale that mini-mills like Nucor lack. Its blast furnaces, though energy-intensive, produce steel with properties that are harder to replicate in electric arc furnaces. This gives USS a niche in sectors requiring specialty grades, such as pipeline steel and aerospace alloys. The company’s market capitalization also reflects its ability to secure offtake agreements with major customers, reducing its exposure to spot price volatility. What the evidence says diverges sharply from perception. For instance, while USS’s stock has underperformed the S&P 500 over the past decade, its enterprise value has held up better than expected during downturns. This resilience stems from its diversified customer base—government contracts, automakers, and construction firms—rather than pure commodity exposure. The table below contrasts common assumptions with data-backed realities:| Common Belief | What the Evidence Says |
|---|---|
| USS is a high-debt, low-margin operation. | Debt ratios improved post-2019 bankruptcy; EBITDA margins averaged ~15% in high-price environments. |
| Its mills are obsolete and uncompetitive. | Modernization efforts (e.g., PCI technology, automation) extend asset life; specialty steels command premiums. |
| Revenue is purely tied to U.S. construction cycles. | Automotive (EVs), defense, and energy sectors contribute ~40% of sales; global joint ventures add stability. |
| Green initiatives are a distraction. | Hydrogen pilot projects and carbon capture R&D could unlock future pricing power in low-carbon steel. |
| Shareholder returns are negligible. | Dividends resumed in 2021; share buybacks occurred during high-price periods. |
"USS isn’t a growth story, but it’s not a value trap either. It’s a cyclical play with a moat in niche markets—if you can stomach the volatility."
Why the Confusion Persists
The gap between perception and reality stems from USS’s dual identity: a legacy brand and a cyclical industrial stock. Media narratives often reduce it to a "Pittsburgh story," focusing on layoffs and mill closures rather than its global operations. Meanwhile, financial models struggle to account for the company’s unique cost structure—where fixed costs are high but fixed contracts provide stability. Add to this the opacity of steel pricing (often negotiated privately) and the lack of transparency around USS’s green steel investments, and the result is a valuation that’s easy to misread. Investors also conflate USS’s market cap with its book value, ignoring how intangibles like contracts and patents inflate its true worth. The company’s history of bankruptcies further clouds its reputation, even though those filings were restructuring tools rather than signs of insolvency. Until USS sheds its "struggling giant" label—through consistent profitability or a major innovation breakthrough—the confusion will persist.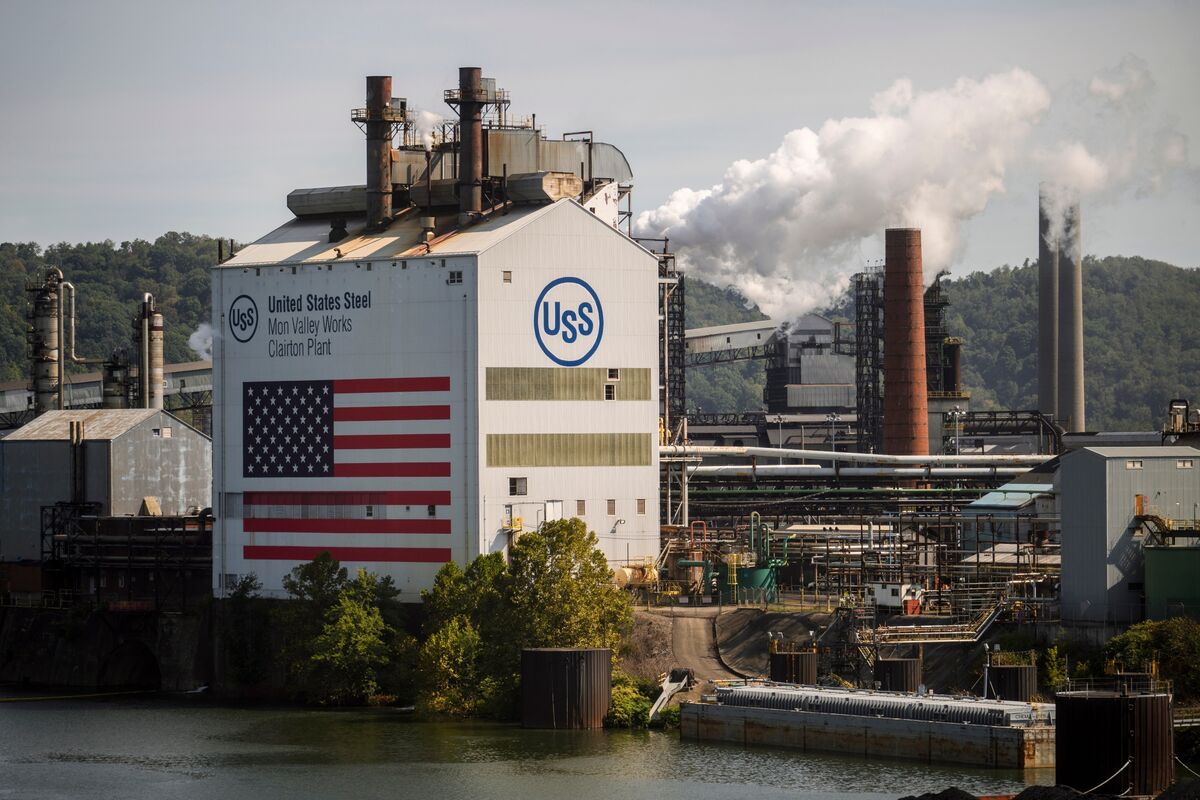
Conclusion
United States Steel’s net worth is less about what it was and more about what it can become. The company’s assets are undeniably physical, but their value is increasingly tied to intangibles: innovation, customer lock-in, and adaptability. While its stock may never trade like a tech darling, its role in America’s industrial base ensures it remains a critical—if volatile—player. The key for stakeholders is to look past the noise: the mills, the debt, and the headlines. What matters is whether USS can monetize its strengths in a world where steel is no longer just a commodity but a strategic material. The next decade will test whether USS’s enterprise value can rise above its legacy. Success hinges on executing its green transition, securing long-term offtake deals, and proving that its integrated model can coexist with the mini-mill revolution. For now, the numbers tell a story of resilience—not invincibility.Comprehensive FAQs
Q: How is United States Steel net worth calculated?
USS’s net worth is derived from its book value (assets minus liabilities) and market capitalization (shares outstanding × stock price). However, its enterprise value—a more holistic measure—includes debt, minority interests, and cash. For 2023, USS’s book value was reported around $3–4 billion, while its enterprise value fluctuated between $8–12 billion depending on steel prices and debt levels.
Q: Why does United States Steel’s stock price swing so wildly?
The volatility stems from its commodity-linked revenue model. Steel prices are influenced by global supply chains, energy costs, and trade policies (e.g., Section 232 tariffs). When demand surges—such as during infrastructure booms or automotive revivals—USS’s stock rallies. Conversely, overcapacity or recession fears send prices—and its valuation—plummeting.
Q: Is United States Steel profitable outside high-price environments?
No. USS’s EBITDA margins typically range from 5–15%, with profitability directly tied to steel prices. In low-price periods (e.g., 2015–2016), the company operated at a loss. Its strategy to mitigate this risk includes long-term contracts with automakers and government entities, which provide stable revenue streams regardless of spot prices.
Q: What are the biggest threats to United States Steel’s net worth?
The top risks include:
- China’s steel exports: Flooding global markets with low-cost steel.
- Energy costs: Natural gas and electricity prices directly impact production margins.
- Automation disruption: Mini-mills like Nucor use EAFs to produce steel cheaper and faster.
- Regulatory hurdles: Stricter environmental rules could force costly upgrades.
Q: How does United States Steel compare to Nucor in terms of valuation?
Nucor trades at a higher enterprise value multiple (~8–10× EBITDA) due to its lower costs and flexibility. USS, with its capital-intensive blast furnaces, typically trades at 4–6× EBITDA. However, USS’s specialty steel capabilities give it a niche that Nucor hasn’t fully penetrated, potentially justifying a premium in certain market conditions.
Q: Can United States Steel’s green steel initiatives boost its net worth?
Possibly, but it’s speculative. USS’s hydrogen-based steelmaking and carbon capture projects are in pilot phases. If successful, they could unlock premium pricing for low-carbon steel in ESG-driven markets. However, scaling these technologies will require billions in investment and regulatory support, making near-term impacts uncertain.
Q: What’s the outlook for United States Steel’s dividend?
Dividends are highly volatile and tied to cash flow. USS resumed payments in 2021 after a decade-long hiatus, yielding ~3–5% at the time. However, dividends are not guaranteed—they’ve been suspended in past downturns. Investors should view them as a bonus, not a stable income stream.
