The Complete Overview of National Auto Care Gap Insurance
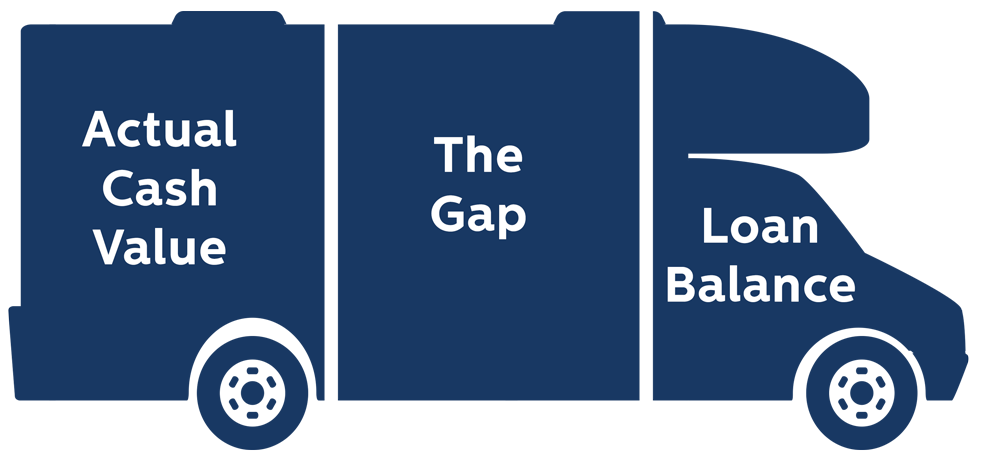
National auto care gap insurance operates as a supplementary layer to standard auto policies, specifically targeting the repair cost gap that arises when an insured loss exceeds the depreciated value of the vehicle. Unlike traditional gap insurance—which is typically sold by lenders to cover the difference between a car’s loan balance and its resale value—this variant is not loan-dependent. Instead, it focuses on the disparity between what an insurer pays out for a total loss or major repair and the actual cost to restore the vehicle to a drivable state. For example, if a policyholder’s car is deemed a total loss with an ACV payout of £8,000 but the cost to replace the engine alone is £12,000, the gap insurance would cover the £4,000 difference. The rise of national auto care gap insurance can be traced to two parallel trends: the increasing complexity of modern vehicles and the erosion of insurer payouts due to inflation and supply chain disruptions. As cars become more reliant on electronics and advanced materials, repair costs have climbed while insurers have tightened their ACV calculations. This mismatch has created a void that gap insurance now fills, particularly for drivers who can’t afford to replace their vehicle outright. The coverage isn’t universal—it’s often bundled with premium auto service plans or sold as an add-on by insurers specializing in high-value or older vehicles—but its adoption is growing as drivers recognize the limitations of standard policies.Historical Background and Evolution
The concept of gap insurance emerged in the 1990s as a response to the ballooning loan-to-value ratios on new cars. Lenders, facing higher risks of upside-down loans, pushed for gap coverage to protect their interests. However, this early form of gap insurance was loan-centric, meaning it only applied if the vehicle was financed. The shift toward national auto care gap insurance began in the 2010s, driven by two key factors: the proliferation of pay-as-you-go (PAYG) insurance models and the growing prevalence of telematics-based coverage. Insurers realized that drivers without loans still faced significant repair gaps, particularly for cars with high-tech components that depreciated rapidly. The evolution accelerated with the rise of direct-to-consumer auto service plans, where companies like National Auto Care (NAC) and others began offering gap protection as part of comprehensive maintenance packages. These plans often include perks like 24/7 roadside assistance, diagnostic credits, and extended warranty coverage, making gap insurance a more attractive proposition. Today, the market for national auto care gap insurance is fragmented, with offerings ranging from standalone policies to embedded protections within extended warranties. The growth has been particularly notable in regions with high repair costs, such as urban centers where older vehicles are more common.Core Mechanisms: How It Works
At its core, national auto care gap insurance functions as a cost-reimbursement tool for repair expenses that exceed an insurer’s payout. The process begins when a policyholder files a claim for a covered loss—whether due to an accident, mechanical failure, or theft. The primary insurer evaluates the claim and determines the ACV of the vehicle. If the repair cost (or replacement cost for a total loss) surpasses this value, the gap insurer steps in to cover the difference, up to the policy’s limit. For instance, if a policyholder’s car is totaled and the insurer offers £10,000 but the cost to replace the vehicle is £15,000, the gap insurance would cover the £5,000 shortfall. What sets national auto care gap insurance apart from traditional gap coverage is its flexibility in application. It isn’t tied to a loan, meaning it can benefit cash buyers, leaseholders, and even drivers with paid-off vehicles. Some policies also extend beyond total losses to cover major non-collision repairs, such as engine failures or transmission replacements, which are often excluded from standard comprehensive policies. The premiums vary widely—typically ranging from £50 to £200 annually—depending on the vehicle’s age, value, and the insurer’s underwriting criteria. Higher-end models or vehicles with expensive repair histories may require additional underwriting, but the coverage remains a critical safeguard against financial strain.Key Benefits and Crucial Impact
The primary appeal of national auto care gap insurance lies in its ability to eliminate the financial shock of unexpected repair costs. For drivers who’ve invested heavily in their vehicles—whether through customizations, modifications, or simply emotional attachment—the prospect of being forced to sell a car for a fraction of its repair cost is devastating. Gap insurance mitigates this risk by ensuring that policyholders aren’t left with a non-functional vehicle and a depleted bank account. This is particularly relevant in an era where auto repair costs have outpaced inflation, with labor and parts prices rising faster than insurer payouts. Beyond the immediate financial relief, national auto care gap insurance offers peace of mind in an industry where surprises are the norm. Drivers who opt for this coverage often report feeling more secure when facing mechanical issues, knowing that a catastrophic failure won’t derail their finances. The impact is most pronounced among older drivers, small business owners, and families who rely on their vehicles for daily commutes or livelihoods. For these groups, the ability to restore a car to working condition without a second mortgage is invaluable."The gap between what insurers pay and what repairs actually cost is a ticking time bomb for most drivers. National auto care gap insurance isn’t just a policy—it’s a financial lifeline for people who can’t afford to gamble on their next breakdown." — Mark Reynolds, Senior Automotive Analyst, Consumer Reports
Major Advantages
- Covers non-collision repairs: Many policies extend beyond accidents to include mechanical failures, which standard insurance often excludes.
- No loan requirement: Unlike traditional gap insurance, this coverage is available to cash buyers and leaseholders.
- Customizable limits: Policyholders can adjust coverage amounts based on their vehicle’s value and repair history.
- Potential for bundled savings: Some insurers offer discounts when pairing gap insurance with service plans or extended warranties.

Comparative Analysis
| Traditional Gap Insurance | National Auto Care Gap Insurance |
|---|---|
| Tied to auto loans; covers difference between loan balance and ACV. | Available to all drivers; covers repair costs exceeding insurer payouts. |
| Primarily for new/leased vehicles. | Applicable to older vehicles, cash purchases, and high-mileage cars. |
| Limited to total loss scenarios. | May cover major non-collision repairs (e.g., engine replacements). |
| Offered by lenders or dealerships. | Sold by insurers, auto service providers, or as part of maintenance plans. |
Future Trends and Innovations
The next frontier for national auto care gap insurance lies in telematics and predictive analytics. Insurers are increasingly using real-time vehicle data to assess risk and tailor gap coverage dynamically. For example, a policyholder with a history of engine issues might receive a premium adjustment—or even a coverage upgrade—based on their driving habits and maintenance records. This shift toward personalized gap insurance could make the product more affordable for high-risk drivers while reducing fraudulent claims. Another emerging trend is the integration of gap insurance with ride-sharing and gig economy policies. As more drivers use their vehicles for commercial purposes, the gap between personal and commercial insurance payouts is widening. Insurers are exploring hybrid gap policies that bridge this divide, offering coverage for both personal and work-related vehicle damage. Additionally, the rise of subscription-based auto services—where drivers pay monthly for maintenance and repairs—may lead to embedded gap protection as part of these plans, further blurring the lines between insurance and vehicle care.
Conclusion
National auto care gap insurance represents a practical solution to a growing financial vulnerability in the auto industry. As repair costs climb and insurer payouts stagnate, drivers who once viewed gap coverage as an unnecessary expense are now recognizing its value. The coverage isn’t a panacea—it requires careful selection of policies and an understanding of its limitations—but for those who qualify, it offers a critical layer of protection against the unexpected. The future of auto care gap insurance will likely be shaped by technology, with data-driven underwriting and integrated service plans making the product more accessible and responsive to individual needs. For now, the message is clear: assuming standard insurance will cover all repair costs is a gamble most drivers can’t afford. National auto care gap insurance isn’t just a policy—it’s a strategic tool for maintaining financial stability in an era of rising automotive expenses.Comprehensive FAQs
Q: Is national auto care gap insurance worth the cost?
It depends on your vehicle’s value and repair history. If your car’s ACV is significantly lower than its repair cost—particularly for high-mileage or luxury models—gap insurance can save thousands. For newer cars with full coverage, the cost may not justify the premium. Always compare the annual premium against potential out-of-pocket expenses.
Q: Can I add national auto care gap insurance to an existing policy?
In most cases, yes. Many insurers allow you to upgrade or add gap coverage to an existing auto policy, either online or through a customer service representative. Some providers also offer it as part of bundled service plans, so check with your insurer or a specialized auto care provider.
Q: Does this coverage apply to leased vehicles?
Yes, but the terms may vary. Leaseholders often have gap coverage built into their lease agreements, but a standalone national auto care gap insurance policy can provide additional protection if the lease’s gap coverage is insufficient. Always review your lease terms to avoid overlaps or exclusions.
Q: Will gap insurance cover modifications or aftermarket parts?
It depends on the policy. Some insurers exclude modifications unless they’re part of a manufacturer-approved package. Others may cover aftermarket parts if they’re deemed essential for the vehicle’s operation. Always clarify with your provider before purchasing coverage.
Q: How quickly can I get reimbursed for a repair under gap insurance?
Reimbursement timelines vary by insurer, but most national auto care gap insurance policies process claims within 14 to 30 days after the primary insurer’s payout. Some providers offer advance payments for urgent repairs, particularly for high-value vehicles.
Q: What happens if my car is a total loss but I still owe money on it?
If you have a loan, traditional gap insurance will cover the difference between the ACV and your loan balance. However, national auto care gap insurance would cover the difference between the ACV and the cost to replace the vehicle (or repair it). In this scenario, you might need both types of coverage to fully protect your investment.
Q: Are there any exclusions I should know about?
Yes. Common exclusions include:
- Intentional damage or fraudulent claims.
- Repairs not approved by the primary insurer.
- Vehicles used for commercial purposes (unless specified in the policy).
- Pre-existing conditions or mechanical failures from lack of maintenance.
