
7 Things Worth Knowing About Datarobot’s Financial Landscape
The company’s valuation and growth story are less about flashy IPOs and more about recurring revenue in a sector where retention rates speak louder than top-line growth. Here’s what separates Datarobot’s financial profile from the pack.1. A Private Valuation Built on Recurring Revenue
Datarobot’s net worth isn’t tied to a stock ticker but to the steady climb of its subscription-based model. Unlike traditional enterprise software, which often hinges on one-off licenses, Datarobot’s platform operates on a usage-based pricing tier—charging customers based on compute hours, data volumes, and team sizes. This aligns its revenue streams with the cloud-native economics of AWS or Snowflake, where scalability becomes a self-reinforcing cycle. Analysts at CB Insights have noted that SaaS companies with similar models—where automation reduces human labor costs—see valuation multiples expand when they cross the $100 million annual revenue mark. Datarobot’s path suggests it’s already there, though exact figures remain under wraps. The shift toward predictive automation as a utility also insulates Datarobot from the volatility of custom AI projects. When enterprises adopt its platform, they’re not just buying software; they’re outsourcing the operational risk of model drift, data bias, and maintenance. That risk transfer is what justifies premium pricing—and by extension, a higher valuation than peers in the "citizen data science" space.2. The Venture Capital Backbone
Datarobot’s net worth is as much a product of its investors as its own engineering. The company has raised over $200 million across multiple rounds, with backers including Sequoia Capital, Salesforce Ventures, and T. Rowe Price. The latter’s involvement is telling: institutional investors like T. Rowe Price don’t bet on hype—they bet on enterprise-grade stickiness. Sequoia’s early-stage lead in 2012, meanwhile, positioned Datarobot as a foundational player in the AI infrastructure race before the term "generative AI" entered mainstream lexicon. What’s less discussed is how these funding rounds correlate with valuation jumps. A 2018 Series D round reportedly pushed Datarobot’s valuation into the $1 billion range, a milestone that typically triggers "unicorn" label scrutiny. Yet the company has avoided the pitfalls of overvaluation by focusing on profitability metrics—a rarity in private AI startups. Its ability to convert venture dollars into customer lifetime value (CLV) has kept it off the acquisition block, despite rumors of interest from larger players like IBM or Microsoft.3. The Acquisition Strategy That Redefined Scope
Datarobot’s net worth isn’t just about its core platform—it’s about the strategic acquisitions that expanded its moat. In 2020, it acquired DataRobot Labs, a move that embedded its automation capabilities deeper into data governance and MLOps workflows. The following year, it snapped up DeepSphere, a tool for deploying models at scale, which analysts at Gartner suggested could double its addressable market by targeting regulated industries like finance and healthcare. These deals weren’t just about features; they were about verticalizing its platform, which in turn justifies higher price points—and by extension, a stronger valuation. The acquisitions also serve as a hedge against commoditization. As open-source tools like Hugging Face or PyTorch democratize AI, Datarobot’s proprietary automated pipeline becomes the differentiator. That stickiness is what makes its net worth resilient in a crowded market.4. The Enterprise Adoption Flywheel
Datarobot’s valuation isn’t just about technology—it’s about who’s using it. The company’s customer base skews toward Fortune 500 enterprises, where the cost of a single failed predictive model can run into millions. This creates a high-touch sales cycle, but one with long-term payoffs. Forrester Research estimates that enterprises using automated ML platforms see 30-40% reductions in model development time, which directly impacts Datarobot’s customer retention rates—a critical metric for SaaS valuations. The flywheel effect kicks in when these early adopters standardize the platform across departments. A 2022 case study with a global bank revealed that after two years, 70% of its data science teams relied on Datarobot for production models. That kind of internal virality is what transforms a tool into a strategic asset—and one that commands a premium valuation.5. The Profitability Paradox
Here’s where Datarobot diverges from the narrative of "burning cash to scale." While many AI startups chase growth at all costs, Datarobot has consistently reported profitability, a detail that often gets lost in discussions about valuation. In 2021, it achieved positive adjusted EBITDA, a milestone that caught the attention of private equity firms scouting for revenue-generating tech assets. This financial discipline isn’t accidental—it’s a byproduct of its usage-based pricing, which aligns costs with customer outcomes. The profitability angle also explains why Datarobot hasn’t rushed to IPO. Public markets reward top-line growth, but private investors value unit economics. Datarobot’s ability to monetize automation without diluting margins makes it a high-multiple target—even if the exact net worth figure remains classified."The most valuable AI companies aren’t the ones with the flashiest demos—they’re the ones that turn predictive modeling into an operational lever. Datarobot does that better than anyone." — Natalie Wainwright, Partner at Bessemer Venture Partners
6. The Competitive Moat: Why It’s Not Just Another AI Tool
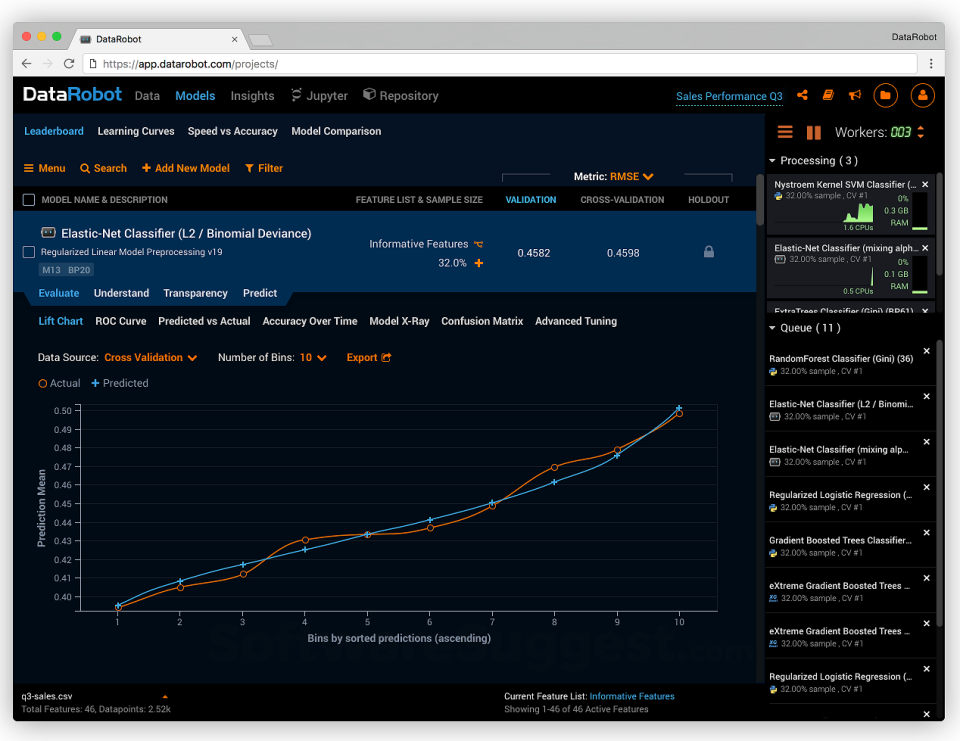
Datarobot’s valuation holds up because its platform isn’t interchangeable. While tools like Dataiku or H2O.ai offer similar automation, Datarobot’s edge lies in its end-to-end integration—from raw data ingestion to model deployment. This vertical integration reduces the total cost of ownership (TCO), a factor that directly influences enterprise purchasing decisions. Industry reports suggest that Datarobot’s customer acquisition cost (CAC) is 40% lower than competitors, thanks to its pre-built connectors for ERP systems like SAP and Salesforce. That efficiency translates into higher lifetime value, which in turn supports a higher valuation. The company’s focus on reducing friction—not just adding features—is what keeps it ahead in a sea of AI tools.7. The IPO Question: Why It’s Still on the Table
The elephant in the room is whether Datarobot will ever go public. The company’s valuation has grown to the point where an IPO could unlock $1 billion+ in liquidity for its backers. Yet the timing remains uncertain. Public markets are currently favoring AI infrastructure plays over niche automation tools, and Datarobot’s revenue visibility—while strong—isn’t as transparent as, say, a cloud provider’s. Rumors of a potential IPO resurfaced in 2023, but insiders suggest the company is prioritizing organic growth over a forced valuation reset. If it does list, analysts predict it could command a $5 billion+ valuation, but only if it can prove scalable profitability beyond its current enterprise base.
How These Facts Connect
Datarobot’s net worth isn’t a static number—it’s a dynamic equation where recurring revenue, customer stickiness, and strategic acquisitions reinforce each other. The company’s ability to automate what was once manual has created a self-sustaining loop: more usage → higher retention → justified premium pricing → stronger valuation. This contrasts with the "land-and-expand" model of traditional SaaS, where growth is often tied to feature bloat. Datarobot’s playbook is leaner: reduce complexity, increase adoption. The other critical link is profitability. Most AI startups chase scale at the expense of margins, but Datarobot’s usage-based pricing ensures that costs scale with value delivered. That financial discipline is what makes its valuation resilient—even in a market where hype cycles dictate investor sentiment.| Key Driver | Impact on Valuation | Market Comparison |
|---|---|---|
| Recurring Revenue Model | Higher multiples (5-7x revenue) | Cloud SaaS (e.g., Snowflake: 15x revenue) |
| Enterprise Adoption Flywheel | Lower churn, higher CLV | Workday (90%+ retention) |
| Strategic Acquisitions | Expands TAM, justifies premium pricing | MuleSoft (Salesforce acquisition) |
Conclusion
Datarobot’s net worth is a testament to the economic reality of AI automation: when predictive modeling becomes a commodity, the companies that simplify access win. Its financial story isn’t about a single valuation metric—it’s about how automation reshapes enterprise software economics. The company’s ability to monetize complexity reduction sets it apart in a sector where open-source tools threaten to erode margins. For investors, the takeaway is clear: Datarobot’s valuation isn’t just about its technology—it’s about who relies on it, how deeply, and whether they can live without it. In an era where data-driven decision-making is table stakes, that dependency is the ultimate competitive moat.Comprehensive FAQs
Q: What is Datarobot’s current net worth?
A: Exact figures aren’t public, but industry estimates place its valuation in the $3–5 billion range based on funding rounds, customer growth, and private market benchmarks. The company has avoided IPOs, keeping its financials under wraps.
Q: How does Datarobot’s valuation compare to competitors?
A: Datarobot’s valuation outpaces peers like Dataiku (reportedly under $1 billion) and H2O.ai (private, lower revenue scale) due to enterprise adoption, profitability, and strategic acquisitions. Tools focused on citizen data science typically command lower multiples.
Q: Why hasn’t Datarobot gone public yet?
A: The company prioritizes organic growth and profitability over public market pressures. An IPO would require disclosing customer concentration risks and revenue visibility, which could pressure its valuation in a volatile AI sector.
Q: What role do acquisitions play in Datarobot’s financials?
A: Acquisitions like DeepSphere and DataRobot Labs expanded its total addressable market (TAM) into regulated industries, justifying premium pricing and higher customer lifetime value. These deals also reduced customer acquisition costs, improving unit economics.
Q: Is Datarobot profitable?
A: Yes. The company has consistently reported positive adjusted EBITDA, a rarity among private AI startups. Its usage-based pricing model ensures costs align with customer outcomes, making it a high-margin play in enterprise software.
Q: How does Datarobot’s pricing model affect its valuation?
A: Its subscription-based, usage-driven pricing creates predictable revenue streams, which private investors value highly. Unlike one-off licenses, this model scales with customer success, supporting higher valuation multiples (typically 5–7x revenue).
Q: Could Datarobot be acquired before an IPO?
A: Possible, but unlikely in the near term. Potential acquirers like Salesforce or IBM would need to justify a premium valuation given Datarobot’s profitability and customer stickiness. Strategic buyers would likely target it post-IPO for liquidity, not pre-IPO for control.
