Breaking Down the Numbers
The Federal Reserve’s triennial survey remains the gold standard for answering what is the median net worth of an American, but its limitations are telling. The most recent data, from 2022, paints a picture of a nation where wealth is concentrated in the hands of older, white, homeowning households. Median net worth for families headed by someone under 35? $12,200. For those 65 and older? $266,400. The gap isn’t just generational—it’s racial. A white family’s median net worth is $188,200; for a Black family, it’s $48,900. These aren’t outliers; they’re the rules. The median itself is a fragile benchmark. A single market crash, a job loss, or a medical emergency can push millions across the threshold. In 2020, the COVID-19 pandemic erased a decade of wealth gains for the bottom 50% of Americans, while the top 1% saw their net worth swell by $2.9 trillion. The median net worth of an American isn’t just a reflection of economic health; it’s a stress test of resilience.The Verified Baseline
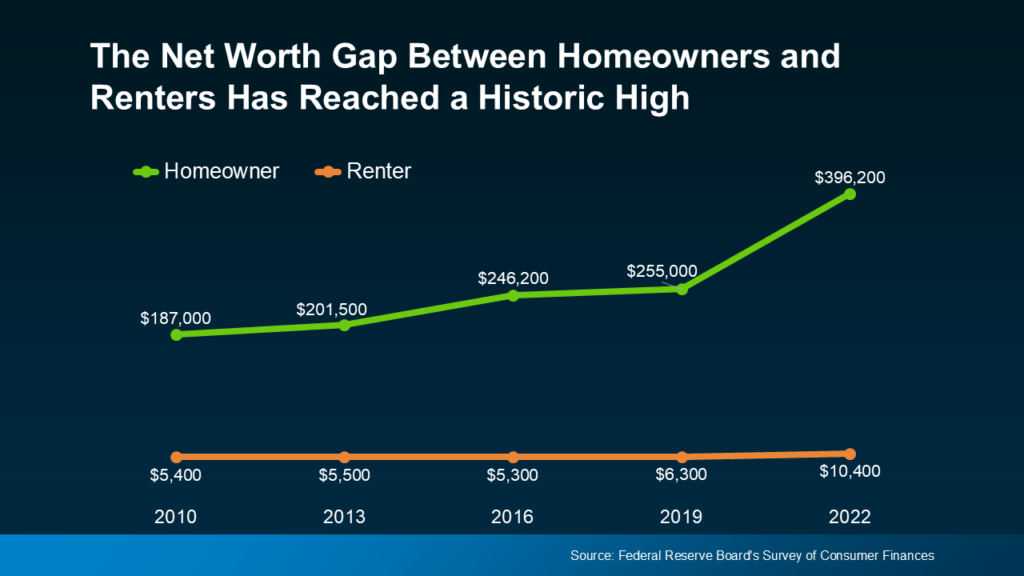
The Federal Reserve’s numbers are the only nationally representative, peer-reviewed source for what the median net worth of an American looks like in aggregate. Their 2022 survey, published in 2023, sampled 6,000 households and adjusted for inflation using the Consumer Price Index. Key takeaways: - Homeownership is the single largest driver of wealth. Nearly 70% of wealth for the median household comes from primary residences. Renters? Their median net worth is $8,300. - Debt drags down the numbers. Student loans, credit cards, and auto debt collectively subtract $16,000 from the median net worth. - Retirement accounts are the wild card. The median 401(k) balance for all workers is $65,000, but for those 55–64, it jumps to $205,000. What’s missing? The survey doesn’t track cryptocurrency, side-hustle income, or informal wealth like inherited assets. These omissions matter—especially for younger cohorts where gig work and digital assets are increasingly relevant.What the Estimates Suggest
Beyond the Fed’s data, other estimates attempt to fill the gaps. The Brookings Institution’s analysis of 2023 data suggests the median net worth of an American may have dipped slightly—to around $180,000—due to rising interest rates and stock market volatility. Meanwhile, the Urban Institute projects that by 2030, the median could stagnate unless policies like expanded child tax credits or student debt relief are enacted. Then there are the speculative models. Some economists argue that if current trends continue, the median net worth of an American could halve by 2050 for younger generations, thanks to housing unaffordability and wage stagnation. Others counter that technological disruption—think AI-driven productivity gains—could lift the median higher. The consensus? The median is more volatile than it appears.
Case Study: A Closer Look
Consider the Smiths of Toledo, Ohio—a middle-class family of four where the breadwinner earns $75,000 annually. Their net worth, at $190,000, sits just above the national median. But peel back the layers: - Their $250,000 home (mortgaged at $120,000) is their largest asset. - A $15,000 401(k) balance means retirement is a distant hope. - $30,000 in student debt for the parents’ degrees offsets their equity. For the Smiths, the median isn’t a milestone—it’s a tipping point. One job loss, one medical bill, and they’d fall below it. Their story isn’t exceptional; it’s the American norm."The median net worth of an American isn’t about how much you have—it’s about how little you need to lose before you’re broke." — Lisa Dettling, financial sociologist at Ohio State University
| Factor | Estimated Impact on Net Worth |
|---|---|
| Homeownership status | Owners: +$150,000 vs. renters: -$140,000 |
| Age of household head | Under 35: $12,200 | 65+: $266,400 |
| Student debt burden | Debtors: -$25,000 vs. debt-free peers |
| Retirement savings | Median 401(k): $65,000 (but <50% have any) |
What This Means Going Forward
The median net worth of an American is a lagging indicator. It tells us where we’ve been, not where we’re headed. But the trends are clear: without structural changes—like expanding the Earned Income Tax Credit or reforming zoning laws to boost homeownership—the median will continue to favor the old over the young, the white over the Black, the homeowner over the renter. The real question isn’t what is the median net worth of an American today, but whether future generations will even recognize the concept. If current trajectories hold, the median could become a relic—a statistical artifact of an economy that no longer functions for the majority.
Conclusion
Numbers alone won’t solve the wealth divide. But understanding what the median net worth of an American really represents—the precarious balance between security and instability—is the first step. The median isn’t a target to hit; it’s a warning sign. Ignore it, and the gap widens. Address it, and the conversation shifts from how much to how to share. The next time you hear the median net worth cited, ask: Who’s missing from that average? The answer will tell you everything you need to know about America’s economic future.Comprehensive FAQs
Q: How often is the median net worth of an American updated?
The Federal Reserve’s Survey of Consumer Finances, the most reliable source, is published every three years. The most recent data (2022) was released in September 2023, with the next update expected in late 2025. Other estimates, like those from the Urban Institute or Brookings, may use annual or rolling data but aren’t as comprehensive.
Q: Does the median net worth include business assets?
No. The Federal Reserve’s survey excludes privately held business equity unless the business is incorporated or publicly traded. This omission undercounts wealth for self-employed individuals, who represent 10% of the workforce but often hold significant unrecorded assets.
Q: How does the median net worth of an American compare to other countries?
According to OECD data, the U.S. median net worth (adjusted for purchasing power) ranks mid-tier among developed nations. Canada’s median is slightly higher ($200,000), while Germany’s is lower ($120,000). However, the U.S. leads in wealth inequality—its Gini coefficient for net worth is 0.8, compared to 0.6 in Sweden.
Q: Why does the median net worth matter for policymakers?
Because it’s a proxy for economic mobility. A stagnant or declining median signals that the middle class isn’t growing—meaning fewer people can afford homes, education, or retirement. Policies like the Child Tax Credit (which lifted 40% of children out of poverty in 2021) directly impact the median by boosting household assets.
Q: Can the median net worth of an American ever reach $250,000?
Only if structural barriers fall. Historical data shows the median has never exceeded $190,000 in inflation-adjusted terms since the 1980s. To hit $250,000, the U.S. would need massive increases in homeownership, wage growth, and retirement savings participation—none of which are guaranteed.
Q: How does student debt affect the median net worth?
Student loans depress the median by $25,000 on average. Borrowers under 40 see their net worth 30% lower than peers with similar incomes. The debt isn’t just a personal burden; it’s a systemic drag on wealth accumulation, as younger households delay home purchases and retirement savings.
Q: What’s the difference between median and mean net worth?
The mean (average) net worth is $138,000—far higher than the median because it’s skewed by billionaires. The median splits the population in half: 50% have less, 50% have more. The mean, however, is pulled upward by the top 1%, whose wealth can double the average.
Q: Are there regional disparities in the median net worth?
Yes. The median net worth in Maryland ($250,000) is 35% higher than the national average, thanks to high home values and tech jobs. In Mississippi, it’s $80,000—57% below the median. These gaps reflect housing costs, wage levels, and historical redlining policies.
