
Where It All Began
The 401k’s origins trace back to a tax loophole, not a grand social policy. In 1974, Congress passed Section 401(k) of the Internal Revenue Code as a fringe benefit for highly compensated employees at AT&T and other corporations. The idea was simple: let executives defer part of their salaries into tax-advantaged accounts. It wasn’t until 1981, under President Reagan’s Economic Recovery Tax Act, that the rules were expanded to include rank-and-file workers. The shift was seismic. Suddenly, millions of Americans had a way to save for retirement without the hassle of managing individual investments. But the early years were messy. Employers adopted 401k plans at wildly different rates, and participation remained low—often below 20%—because the responsibility fell entirely on employees to opt in and contribute. The real inflection point came in the late 1980s, when companies like Johnson & Johnson and IBM began offering automatic enrollment in their 401k plans. The move was a gamble: if employees were signed up by default, they’d save more, even if just by inertia. The strategy worked. Participation rates climbed, and with them, the average balance of a 401k began to inch upward. Yet the early adopters were still a privileged few. Most workers—especially those in blue-collar jobs or at smaller firms—had no access to a 401k at all. The system’s promise of universal retirement savings was still years away.The Early Signs
By the mid-1990s, the cracks in the 401k’s foundation were visible. The stock market’s boom-and-bust cycles exposed how vulnerable retirement balances were to external forces. The 1987 crash and the dot-com bubble’s collapse in 2000 left many workers staring at balances that had shrunk overnight. Meanwhile, employers were cutting back on matches and increasing contribution limits, shifting more risk onto employees. The average balance of a 401k during this era was less a reflection of financial health and more a snapshot of market timing. For those who’d invested heavily in tech stocks in the late ’90s, their balances soared. For others, the losses were devastating. The other silent killer was inflation. Even as 401k balances grew in nominal terms, the purchasing power of those dollars eroded. A $50,000 balance in 1995 might as well have been $30,000 by 2005. Yet most employees had no way of knowing how their savings stacked up against future needs. The lack of transparency around fees, investment options, and employer contributions meant that what is the average balance of a 401k told only part of the story. The rest was hidden in fine print—or worse, in the decisions employees never got to make.The Turning Point
The Pension Protection Act of 2006 was supposed to fix what was broken. Congress mandated automatic enrollment for new 401k plans, required better disclosure of fees, and pushed employers to offer low-cost investment options. The goal was to democratize retirement savings, ensuring that even low-wage workers could build meaningful balances. For the first time, the average balance of a 401k became a national conversation, not just a corporate HR metric. But the law arrived too late for many. The Great Recession of 2008 hit just two years later, wiping out trillions in retirement savings and resetting the game for a generation. The recession exposed the fragility of the 401k system. Balances that had taken decades to grow vanished in months. Workers who’d relied on their 401ks as a safety net found themselves staring at account values that barely covered a year’s expenses. The average balance of a 401k in 2010 was a fraction of what it had been in 2007, and the recovery was slow. Employers, facing their own financial struggles, slashed matches or eliminated plans altogether. The turning point wasn’t just legislative—it was psychological. Trust in 401ks as a reliable retirement tool cracked, and the question what is the average balance of a 401k became a proxy for broader anxieties about economic security.“Before 2008, people thought a 401k was a guaranteed path to retirement. Afterward, they realized it was just another gamble—one where the house always wins.” — Aria Rafinejad, retirement policy analyst at the Urban Institute
The Build-Up, Year by Year
The evolution of the average balance of a 401k can be broken into four key periods, each shaped by economic shifts, policy changes, and employer behavior.| Period | Key Developments |
|---|---|
| 1980s–1990s | Early adoption by large corporations; low participation (under 20%); balances skewed toward high earners. The average balance of a 401k was often below $10,000 for rank-and-file workers. |
| 2000–2007 | Automatic enrollment spreads; tech boom inflates balances for some, but dot-com crash and 2008 recession devastate others. By 2007, the median balance was around $20,000, but the mean was distorted by outliers. |
| 2010–2015 | Slow recovery post-recession; employers cut matches, fees remain opaque. The average balance of a 401k stagnates, with younger workers saving almost nothing. |
| 2016–Present | Rise of robo-advisors and target-date funds; more employers offer matches, but gig economy workers lack access. The median balance now sits around $30,000, but the gap between top and bottom earners widens. |
Lessons From the Journey
The history of the average balance of a 401k reveals six hard truths about retirement savings: - Employer matches are the great equalizer—or divider. Workers who contribute enough to get a full match (often 3–5% of salary) see their balances grow exponentially faster than those who don’t. - Market timing is luck, not strategy. Those who retired during bull markets saw their balances swell; those who retired in downturns faced severe cuts to their income. - Fees eat silently. High-expense funds can shave hundreds of thousands off a balance over 30 years—yet most employees never see the exact cost. - Inflation is the silent thief. A $100,000 balance in 2023 might buy what $60,000 could in 2000, but few adjust their savings rates accordingly. - Access isn’t universal. Over 30 million Americans lack access to a workplace retirement plan, and gig workers often have no option but to save on their own. - Behavior matters more than policy. Automatic enrollment helps, but without financial literacy, many workers still misallocate contributions or panic-sell during downturns.Where Things Stand Today
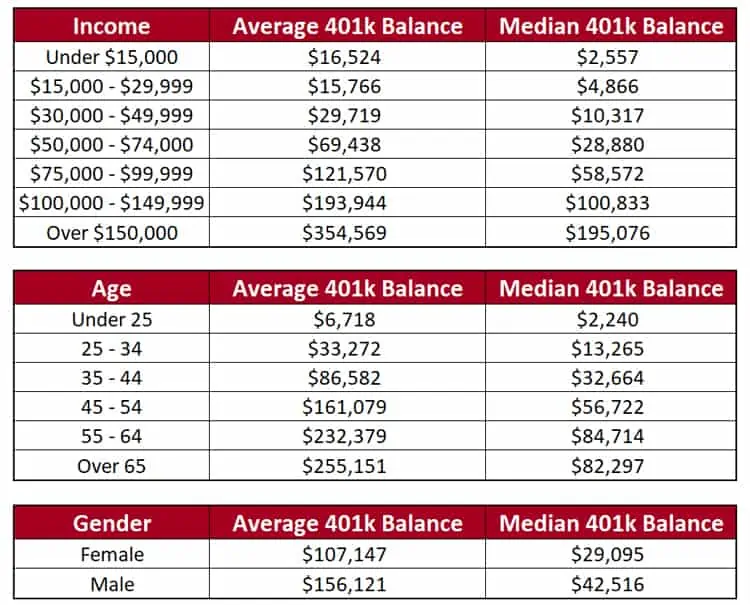
As of 2024, the average balance of a 401k is a moving target, but the numbers tell a familiar story: inequality. According to the latest data from the Federal Reserve and Vanguard’s How America Saves report, the median 401k balance for all participants is roughly $30,000, while the mean balance—distorted by high earners—hovers around $120,000. The gap between the two is a stark reminder that averages lie. For workers under 35, the median balance is closer to $6,000, while those near retirement (ages 55–64) have balances around $180,000. The system rewards longevity, but not all workers have the luxury of staying in one job for decades. What’s changed in recent years? More employers now offer automatic escalation—gradually increasing contribution rates unless the employee opts out—and default investments in low-cost target-date funds. Yet progress is uneven. Workers at large firms with generous matches (think tech or finance) see their balances grow faster than those at small businesses or in public-sector jobs. The average balance of a 401k is also a reflection of demographic shifts: younger workers, saddled with student debt and stagnant wages, save far less than previous generations did at the same age. Meanwhile, the rise of mega-backdoor Roth contributions and solo 401ks for self-employed individuals has created a two-tiered retirement landscape—one where the wealthy optimize tax-advantaged accounts while the middle class struggles to keep up.
Conclusion
The average balance of a 401k isn’t just a number—it’s a symptom of a larger problem: a retirement system that works for some but leaves others behind. The history of these accounts mirrors the broader economy’s swings: booms that inflate balances, crashes that reset them, and policies that promise fairness but often deliver favors to those who already have the most. The question what is the average balance of a 401k forces us to confront uncomfortable truths: that saving for retirement is less about discipline and more about access, luck, and structural support. And yet, for all its flaws, the 401k remains the closest thing most Americans have to a retirement safety net. The path forward isn’t simple. It requires employers to offer better matches, governments to close the coverage gap for gig workers, and individuals to demand transparency about fees and performance. But the first step is understanding the reality behind the averages—because the average balance of a 401k isn’t a benchmark to aspire to. It’s a warning sign that the system is broken, and fixing it starts with knowing exactly how broken it is.Comprehensive FAQs
Q: What is the average balance of a 401k for someone in their 20s?
The median balance for workers under 35 is estimated at $6,000 to $10,000, though this varies widely by income and employer. Many in this age group are still paying off student loans or saving for down payments, leaving little for retirement contributions.
Q: How does a 401k match affect the average balance?
An employer match can double or triple an employee’s contributions, significantly boosting the average balance of a 401k over time. For example, contributing 5% of a $50,000 salary with a 3% match adds $1,500 annually—money the employee wouldn’t otherwise save.
Q: Why is the median balance lower than the average?
The average balance of a 401k is skewed by high earners and long-tenured employees. The median (middle value) is far more representative of typical workers, which is why financial planners focus on it when discussing retirement readiness.
Q: Can I have a 401k if I’m self-employed or a gig worker?
Yes, but options vary. Freelancers can open a Solo 401k or SEP IRA, while gig workers may rely on IRAs. The lack of employer matches makes saving harder, which is why the average balance of a 401k for these groups tends to be much lower.
Q: What’s the biggest mistake people make with their 401k?
Cash-out penalties (taking distributions before age 59½) and ignoring fees are top offenders. High-expense funds can cost retirees hundreds of thousands over time, directly impacting the average balance of a 401k at retirement.
Q: How does inflation affect my 401k balance?
Inflation erodes purchasing power. A $500,000 balance might feel secure until you realize it buys what $300,000 could 20 years earlier. Adjusting contribution rates and diversifying investments can help mitigate this risk.
Q: Is the average balance of a 401k enough for retirement?
No—not by a long shot. Financial advisors recommend having 10–12 times your annual income saved by retirement. The median average balance of a 401k ($30,000) would generate just $1,200–$1,500/month in Social Security-equivalent income, leaving most retirees dependent on other savings.
