The Short Answers
- Median net worth for U.S. retirees hovers around $250,000, but half have less than $100,000 in liquid assets.
- Top 10% of retirees hold over 50% of all retirement wealth, skewing averages upward.
- Home equity accounts for 60-70% of retiree wealth, making housing markets a critical factor.
- Regional differences are extreme—retirees in Massachusetts or New York average $500,000+, while those in Mississippi or West Virginia often have under $150,000.
- Healthcare costs can erode savings fast: A couple retiring at 65 may spend $300,000+ on medical expenses over their lifetime.

Deep Dive: The Full Picture
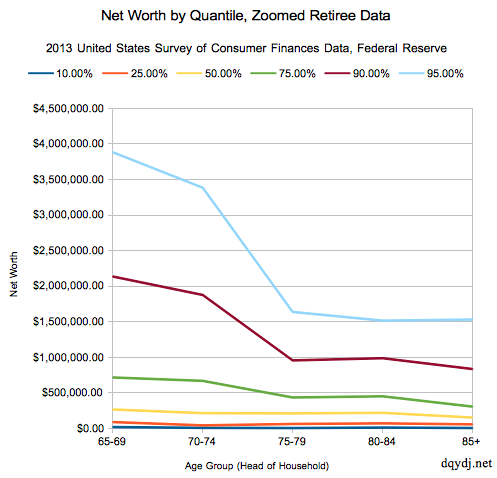
The what is average net worth of retirees question is often answered with a single number, but that number is a distortion. The Federal Reserve’s data shows that median net worth (the midpoint where half have more, half have less) is far lower than the mean (which is inflated by ultra-high-net-worth retirees). For example, while the mean net worth for retirees aged 65-74 is $1.2 million, the median is closer to $280,000. This gap highlights how wealth concentration distorts perceptions of financial security in retirement. International comparisons further complicate the picture. In Canada, the median retiree net worth is estimated at $300,000 CAD, but homeownership rates drop sharply for those without pensions. In Western Europe, state pensions provide a floor, but private savings vary wildly—German retirees average €500,000, while Greeks often rely on family support or part-time work. The what is average net worth of retirees in Japan, meanwhile, is skewed by ultra-low interest rates and a cultural reluctance to discuss financial struggles, making precise figures elusive.The Context You Need
Understanding what is average net worth of retirees requires peeling back layers of economic history. The 1980s and 1990s saw the rise of 401(k)s as the dominant retirement vehicle, shifting risk from employers to individuals. This transition coincided with stagnant wage growth and rising healthcare costs, creating a perfect storm for financial vulnerability. Today, only 16% of private-sector workers have access to a traditional pension, compared to 60% in the 1980s. The result? A retirement system where savings success hinges on market performance, not employer guarantees. Geography plays an outsized role. Retirees in high-cost coastal cities (San Francisco, Boston, Miami) often deplete savings faster due to housing and healthcare expenses. Meanwhile, those in low-cost states like Mississippi or Arkansas can stretch savings further—but may lack access to quality healthcare or cultural amenities. The what is average net worth of retirees in rural America is frequently understated because traditional metrics don’t account for informal support networks or barter economies that supplement cash flow.The Mechanics
The mechanics of retirement wealth are less about how much you save and more about how you save it. Home equity is the single largest asset for most retirees, comprising 60-70% of total net worth. However, reverse mortgages—once seen as a lifeline—are now less accessible due to stricter lending standards post-2008. Stock market exposure is another wild card: retirees who timed withdrawals poorly during the 2000 dot-com crash or 2008 financial crisis saw portfolios shrink by 20-30% before recovery. Tax policy also shapes retirement wealth. Roth IRAs and 401(k)s offer tax-free growth, but required minimum distributions (RMDs) force retirees to convert traditional accounts to taxable income—often at higher marginal rates. Meanwhile, Social Security benefits replace only 40% of pre-retirement income for average earners, leaving a gap that must be filled by savings or part-time work. The what is average net worth of retirees in high-tax states like California or New York is further eroded by state income taxes on withdrawals, pushing some to relocate or downsize to preserve capital.Details That Change the Picture
The what is average net worth of retirees narrative shifts dramatically when you factor in healthcare, longevity, and unexpected expenses. A retiree with $1 million in assets might still face bankruptcy risk if hit by a $200,000 medical bill or a long-term care need. According to Fidelity, a 65-year-old couple retiring today has a 78% chance of needing some form of long-term care, with costs averaging $100,000+ per year for assisted living. Another critical detail: retirement is no longer a single phase. Many retirees return to the workforce—either by choice or necessity. Nearly 20% of retirees aged 65-74 are still employed, often in part-time or gig work, to supplement savings. This trend is even more pronounced among women and minorities, who face longer career interruptions and lower lifetime earnings. The what is average net worth of retirees in these groups is frequently underreported because traditional surveys don’t capture informal income sources."Retirement planning isn’t about numbers—it’s about resilience. A retiree with $500,000 might feel secure, but a single unexpected expense can derail that. The real measure isn’t net worth; it’s cash flow flexibility." — Dr. Teresa Ghilarducci, Director of the Schwartz Center for Economic Policy Analysis
| Factor | Impact on Retirement Net Worth |
|---|---|
| Homeownership Status | Owners: 60-70% higher net worth than renters. Non-owners rely on Social Security + part-time work. |
| Pension Coverage | With pension: Median net worth +$300,000. Without: Reliance on 401(k)s, often depleted faster. |
| Healthcare Costs | Couple retiring at 65: $300,000+ lifetime medical expenses. Single retiree: $150,000+. |
| Market Timing | Retired in 2008? Portfolio losses of 20-30%. Retired in 2020? Rebound gains, but sequence risk remains. |
| Geographic Location | High-cost cities (NYC, SF): Savings deplete 30% faster. Low-cost states (MS, WV): Stretch further, but fewer services. |

Conclusion
The what is average net worth of retirees question reveals more about economic inequality than personal finance. While headlines focus on median figures, the reality is that retirement wealth is a pyramid—a few at the top with millions, a broad middle struggling with modest savings, and a growing bottom facing precarious security. The data also underscores a systemic failure: employer pensions are vanishing, healthcare costs are rising, and longevity is extending, yet retirement planning remains reactive rather than strategic. For most retirees, financial security isn’t about hitting a target number—it’s about managing risk, healthcare, and lifestyle inflation. The what is average net worth of retirees in 2024 is less about how much you have and more about how you protect it. That means diversifying income streams, planning for long-term care, and adapting to an economy where traditional retirement no longer exists. The numbers may be cold, but the choices they force are deeply personal.Comprehensive FAQs
Q: How does Social Security factor into the average retiree’s net worth?
Social Security isn’t counted as net worth (since it’s an annuity, not an asset), but it replaces 30-40% of pre-retirement income for average earners. Without it, median net worth would drop by 20-30%. However, delaying benefits to 70 can increase monthly payouts by 8% per year, effectively boosting long-term cash flow without touching savings.
Q: Why do retirees in some states have significantly lower net worth?
States with lower home values, weaker pension systems, and higher poverty rates (e.g., Mississippi, West Virginia) see retirees with net worth under $150,000. Conversely, states with strong public pensions (California, New York) or high home equity (Florida, Texas) have retirees with $500,000+. Tax policies also play a role—states with no income tax (Texas, Florida) attract retirees who preserve savings, while high-tax states see outmigration of retirees to lower-cost areas.
Q: Can retirees with average net worth afford healthcare?
Medicare covers 80% of medical costs, but gaps (dental, vision, long-term care) can drain savings fast. A 65-year-old couple needs $300,000+ for healthcare in retirement, per Fidelity. Medigap policies cost $1,500–$4,000/year, and long-term care insurance (if affordable) can protect against $100,000+/year costs. Without planning, average retirees risk depleting savings within 5-10 years due to medical expenses.
Q: How does divorce affect retirement net worth?
Divorce slashes net worth for women in particular—studies show divorced women over 65 have 45% less wealth than married peers. Asset division, spousal support obligations, and re-entry into the workforce (often at lower pay) erode savings. Men, while less affected, may also see retirement timelines pushed back due to higher living costs post-divorce. Prenuptial agreements and post-divorce financial planning are critical for protecting retirement assets.
Q: What’s the biggest mistake retirees make with their net worth?
Withdrawing too much too soon—following the 4% rule (annual withdrawals) is safer than liquidating assets aggressively. Another mistake: ignoring inflation—a $1 million portfolio loses 30% of purchasing power over 10 years with 3% inflation. Overestimating life expectancy (assuming 85 when you’re 65) can deplete savings early. Finally, not accounting for long-term care—70% of retirees will need it, but only 15% plan for it.
Q: How does inflation impact the real value of retiree net worth?
Inflation erodes purchasing power faster than retirees realize. A $500,000 portfolio in 2024 may buy the same as $350,000 in 2034 with 3% annual inflation. Fixed incomes (pensions, bonds) lose value over time, while stocks and real estate can hedge against inflation—but require active management. Retirees with heavy bond allocations (e.g., 60%+) risk outliving their savings in high-inflation decades. Tactical asset allocation (shifting to dividend stocks or TIPS) is key for preserving real wealth.
