
Common Myths About the Average Net Worth in USA 2024
The average net worth in USA 2024 is frequently misrepresented as a universal measure of prosperity. Many assume that if the mean net worth is rising, most Americans are thriving. In truth, this figure is a statistical artifact, dragged upward by the top 1% while the bottom 50% see little growth. Another persistent myth is that homeownership alone guarantees wealth—ignoring the fact that mortgage debt now exceeds the total value of U.S. stocks. Finally, the idea that younger generations will outpace their parents in net worth overlooks student loan debt, which has ballooned to over $1.7 trillion, effectively transferring wealth from the future to existing creditors. The confusion stems from how net worth is calculated. It includes assets like homes, stocks, and retirement accounts but subtracts liabilities such as mortgages and loans. For a homeowner with a $400,000 house and a $300,000 mortgage, their net worth might appear modest—yet they’re often considered "wealthy" in public perception. Meanwhile, a renter with $50,000 in savings and no debt might be financially secure but invisible in these statistics. The average net worth in USA 2024 thus becomes a moving target, shifting with housing markets, stock performance, and policy changes—none of which reflect individual effort or systemic fairness.Myth 1: The Average Net Worth Means Most Americans Are Wealthy
The average net worth in USA 2024 is a mean calculation, meaning it’s heavily influenced by outliers. If one household has $10 million and another has $10,000, the average is $5,050,000—yet 99% of the population falls below that. The median net worth, at $138,000, tells a different story: half of U.S. households have less than this amount. For context, the median net worth for Black households is $24,100, compared to $188,200 for white households. This disparity isn’t just about individual choices; it’s the result of centuries of policy, from redlining to unequal access to education and capital. Even when the average net worth in USA 2024 ticks upward, the gains aren’t distributed evenly. The top 10% hold 70% of all wealth, while the bottom 50% collectively own just 2.6%. The Federal Reserve’s data shows that wealth inequality has worsened since the 2008 financial crisis, with the richest 1% capturing nearly all post-recession growth. The myth persists because media often highlights aggregate numbers without breaking them down by demographic or asset class. Without this context, the average net worth in USA 2024 becomes a smokescreen for deeper economic divides.Myth 2: Owning a Home Guarantees Wealth Accumulation
Homeownership is frequently touted as the primary driver of the average net worth in USA 2024, but this ignores the role of mortgage debt. A 2023 study by the Urban Institute found that homeowners with mortgages have $250,000 in median net worth, while those without mortgages sit at $315,000. The difference? Debt. For renters, the path to wealth is even steeper: they must save aggressively while paying someone else’s mortgage. Meanwhile, the housing market’s volatility—from the 2008 crash to today’s affordability crisis—means home equity isn’t the stable asset it’s often portrayed as. The average net worth in USA 2024 also obscures the fact that many homeowners are "house poor," with little disposable income beyond their mortgage. In cities like San Francisco or New York, home prices have outpaced wage growth for decades, leaving owners with little liquid wealth. The Federal Reserve’s data shows that 40% of Americans couldn’t cover a $400 emergency expense without borrowing. Thus, while homeownership may boost net worth on paper, it doesn’t translate to financial security for millions.Myth 3: Younger Generations Will Outperform Their Parents
Millennials and Gen Z are often dismissed as financially struggling, but the average net worth in USA 2024 suggests a more nuanced picture. Younger cohorts entered the workforce during the Great Recession and its aftermath, facing stagnant wages, gig economy instability, and skyrocketing education costs. However, data from the Federal Reserve shows that millennials aged 35–44 have a median net worth of $120,000, up from $92,000 a decade ago. Yet this progress is offset by student debt: the average Class of 2023 graduate owes $38,000, a burden that delays homeownership and retirement savings. The narrative that younger generations will surpass their parents in net worth ignores structural barriers. The average net worth in USA 2024 for Gen X (ages 45–54) is $250,000, nearly double that of millennials—despite both groups working in similar economic conditions. The gap stems from generational wealth transfers, lower housing costs for older cohorts, and the fact that Gen X benefited from the dot-com boom and housing bubble. Without policy changes—such as student debt relief or wealth-building incentives—the average net worth in USA 2024 will continue to favor those who inherited advantages over those who must build from scratch.
What Holds Up to Scrutiny
The average net worth in USA 2024 is most reliable when examined through median figures and asset class breakdowns. The Federal Reserve’s Survey of Consumer Finances remains the gold standard, though its triennial updates mean real-time data is scarce. What’s clear is that liquid net worth—cash, stocks, and retirement accounts—has become the new benchmark for financial health, especially as homeownership rates decline among younger adults. This shift reflects a broader trend: Americans are increasingly relying on investment portfolios rather than brick-and-mortar assets to build wealth. The data also reveals that education and location are the strongest predictors of net worth. A college degree correlates with higher earnings and asset accumulation, but the cost of that education often cancels out the benefit. Geographically, coastal cities and tech hubs skew net worth upward, while rural and Southern states lag. The average net worth in USA 2024 thus varies wildly by ZIP code—proof that opportunity, not just effort, determines financial outcomes."Wealth isn’t just about income; it’s about access. If you’re born into a family that owns a home, has savings, and can afford good schools, you start miles ahead. The numbers don’t lie, but they don’t tell the whole story either." — Darrick Hamilton, economist and director of the Institute on Assets and Social Policy
| Common Belief | What the Evidence Says |
|---|---|
| The average net worth in USA 2024 means most Americans are wealthy. | The median net worth is $138,000, but the bottom 50% hold just 2.6% of total wealth. The mean is skewed by the top 1%. |
| Homeownership alone builds wealth. | Homeowners with mortgages have $250,000 in median net worth, but debt reduces liquidity. Renters with savings often outperform leveraged owners. |
| Younger generations will surpass their parents’ net worth. | Gen X’s median net worth is $250,000; millennials’ is $120,000. Student debt and housing costs create a $130,000 gap at similar life stages. |
Why the Confusion Persists
The average net worth in USA 2024 remains a moving target because wealth is no longer static. The rise of alternative assets—cryptocurrency, NFTs, and private equity—complicates traditional measurements. A 2023 study by the Brookings Institution found that 40% of ultra-high-net-worth individuals hold significant portions of their wealth in illiquid or volatile assets, which don’t appear in standard net worth calculations. Meanwhile, the gig economy’s growth means many workers lack employer-sponsored retirement plans, relying instead on self-directed investments that fluctuate with market sentiment. Political rhetoric also distorts perceptions. Policymakers and media often frame wealth disparities as individual failures rather than systemic issues. The average net worth in USA 2024 is frequently cited in debates over tax policy, Social Security, and housing affordability, but these discussions rarely address how wealth compounds over generations. Without addressing inheritance, education costs, and access to capital, the average net worth in USA 2024 will continue to reflect—and reinforce—inequality rather than mobility.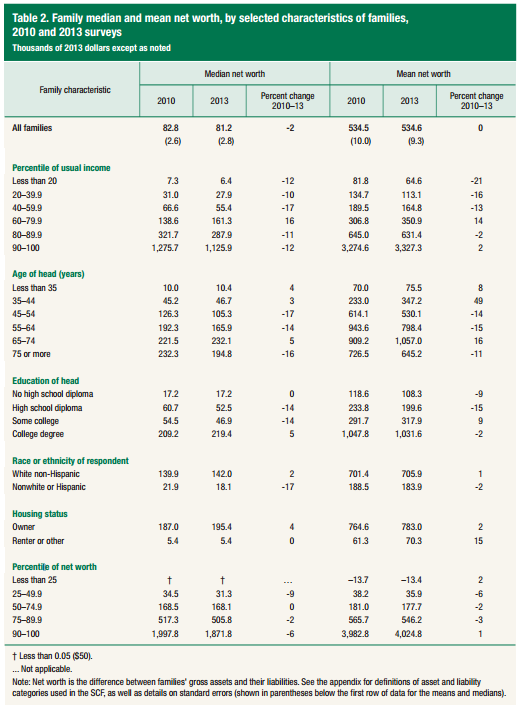
Conclusion
The average net worth in USA 2024 is less about personal success and more about structural advantage. While the numbers may show growth, the reality is one of polarized prosperity: a small group reaps the rewards of asset inflation, while the majority struggles with debt and stagnant wages. The solution isn’t to dismiss the data but to interpret it critically. Understanding that the average net worth in USA 2024 is a median of extremes—where a single billionaire can skew the mean—reveals the true state of American finance. For individuals, this means focusing on liquid net worth and financial literacy, not just homeownership. For policymakers, it demands reforms that address the root causes of inequality: student debt, inheritance gaps, and unequal access to opportunity. The average net worth in USA 2024 isn’t just a statistic; it’s a report card on whether the economy works for everyone—or just the fortunate few.Comprehensive FAQs
Q: How is the average net worth in USA 2024 calculated?
The average net worth in USA 2024 is derived from the Federal Reserve’s Survey of Consumer Finances, which surveys households on assets (homes, stocks, retirement accounts) minus liabilities (mortgages, loans, credit card debt). The mean (average) is sensitive to outliers, while the median (middle value) provides a truer picture of typical wealth.
Q: Why does the average net worth in USA 2024 seem so high when most people feel poor?
The average net worth in USA 2024 is inflated by the top 1%, whose wealth skews the mean. The median net worth ($138,000) is more representative, but even this hides regional and demographic disparities. Many Americans feel poor because wages haven’t kept pace with housing, healthcare, and education costs—despite rising asset values.
Q: Does the average net worth in USA 2024 include cryptocurrency or NFTs?
No. The Federal Reserve’s survey does not account for alternative assets like cryptocurrency or NFTs, which are held by a small but wealthy subset of the population. If included, the average net worth in USA 2024 could appear even higher—though these assets are highly volatile and illiquid.
Q: How does student debt affect the average net worth in USA 2024?
Student debt reduces net worth by increasing liabilities without immediately boosting assets. The average Class of 2023 graduate owes $38,000, delaying homeownership and retirement savings. This drags down the average net worth in USA 2024 for younger cohorts, even if they earn comparable salaries to older generations.
Q: Is the average net worth in USA 2024 higher for minorities?
No. The median net worth for white households ($188,200) is 7.8 times higher than for Black households ($24,100) and 5.5 times higher than for Hispanic households ($36,100). This gap is driven by historical discrimination, unequal access to education, and wealth-building opportunities.
Q: Can the average net worth in USA 2024 be improved without higher wages?
Yes, but it requires asset-building strategies. Reducing student debt, expanding access to retirement accounts (like IRAs), and investing in liquid assets (stocks, ETFs) can boost net worth independently of wage growth. However, systemic changes—such as wealth taxes or inheritance reforms—are needed to address the root causes of inequality.
