The Complete Overview of the Average 401k Balance
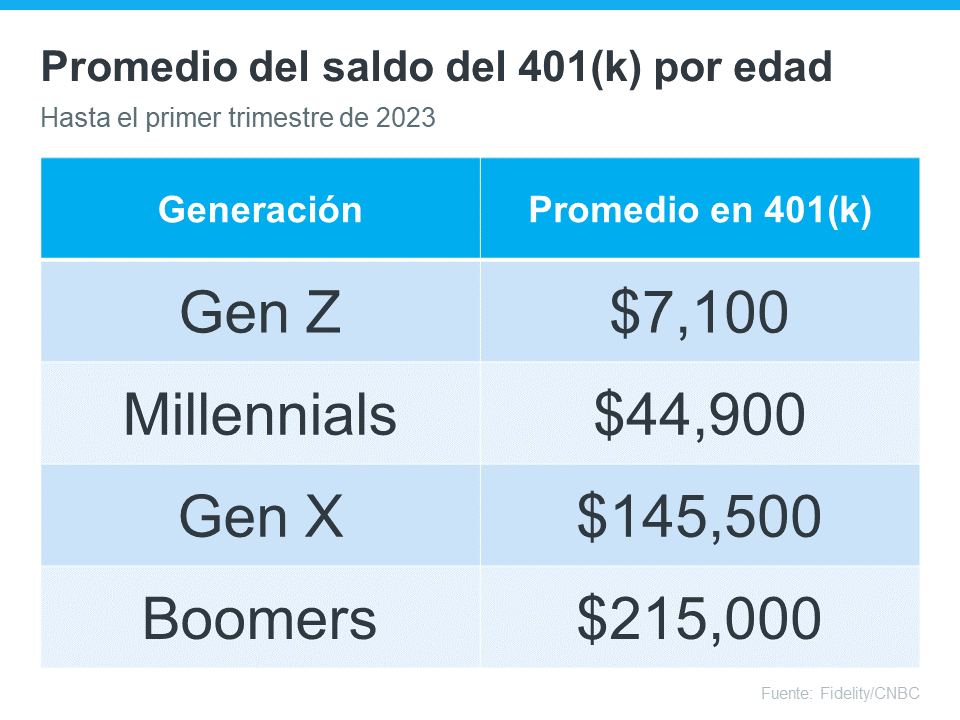
The average 401k balance isn’t static; it’s a moving target influenced by age, income, and participation rates. According to the latest data from the Federal Reserve and retirement plan providers, balances hover around $120,000 for all workers, but this masks critical disparities. For those in their 20s, the figure is closer to $20,000, while near-retirees in their 60s see balances climb to $250,000 or more. The discrepancy underscores a harsh reality: time in the market matters more than any single contribution. Employers with automatic enrollment and matching programs see higher participation, but even these systems fail to close the racial or generational wealth gaps. What’s less discussed is how the average 401k reflects systemic issues. Workers at small businesses or in low-wage sectors often lack access to plans altogether, while high earners leverage catch-up contributions and tax-advantaged strategies to supercharge growth. The COVID-19 pandemic further exposed fragility: early withdrawals and loan defaults during 2020–2021 erased years of progress for some, while others rode market rebounds to new highs. The result? A retirement landscape where the average 401k is less a benchmark and more a starting point for a much harder conversation: What does it take to retire comfortably?Historical Background and Evolution
The 401k’s origins trace back to 1978, when the IRS first allowed tax-deferred retirement savings under Section 401(k) of the Internal Revenue Code. Designed as a supplement to pensions—then the gold standard—it became the default as companies shifted from defined-benefit to defined-contribution plans. By the 1990s, employers began offering matching contributions, turning the average 401k from a side savings tool into a cornerstone of retirement strategy. The Pension Protection Act of 2006 further incentivized participation with automatic enrollment defaults, which studies show boosted savings rates by 10–15%. Yet the evolution hasn’t been linear. The 2008 financial crisis revealed vulnerabilities: balances plummeted as markets crashed, and recovery took years. More recently, the average 401k has been reshaped by technological shifts—mobile apps, robo-advisors, and lifetime income options—giving workers more control but also more responsibility. The rise of part-time and contract labor has also fragmented participation, with nearly half of private-sector workers missing out on employer-sponsored plans entirely. The history of the average 401k isn’t just about numbers; it’s about how economic upheavals and policy changes have redefined what retirement security means.Core Mechanisms: How It Works
At its core, a 401k operates on three pillars: pre-tax contributions, employer matching, and tax-deferred growth. Employees contribute a portion of their paycheck before taxes, reducing their taxable income. Employers may match contributions—often up to 3–5% of salary—effectively offering free money that compounds over time. The average 401k grows through investments in mutual funds, stocks, or bonds, with earnings taxed only upon withdrawal in retirement. For high earners, Roth 401k options allow after-tax contributions with tax-free withdrawals, adding another layer of flexibility. The mechanics extend beyond contributions. Plan providers set investment menus, which can range from conservative bond funds to aggressive growth stocks. Fees—often hidden in expense ratios—erode returns, particularly for smaller accounts. Employers also determine vesting schedules, dictating when employees fully own matched funds. For the average 401k, these details matter: a 1% higher fee on a $50,000 balance costs roughly $500 annually, a sum that adds up over decades. Understanding these levers is critical, as small adjustments to contribution rates or asset allocation can dramatically alter long-term outcomes.Key Benefits and Crucial Impact
The average 401k isn’t just a savings vehicle—it’s a tool for wealth accumulation that leverages time, tax advantages, and employer support. For the 35-year-old contributing 6% of a $60,000 salary with a 3% match, the plan becomes a forced savings habit, with compounding turning modest deposits into a substantial nest egg. The tax deferral alone can save workers thousands annually, especially in high-income brackets. Even for those who switch jobs frequently, 401k portability rules allow rollovers to IRAs or new employer plans, preserving growth potential. Yet the impact isn’t uniform. The average 401k fails to address structural inequities: women, minorities, and low-wage workers consistently save less due to career interruptions, pay gaps, and limited access. A 2023 study by the Economic Policy Institute found that Black and Hispanic households hold 30–40% less in retirement accounts than white households, a gap that widens with age. The plan’s benefits, while significant, are only as strong as the systems that support—or exclude—participants.“A 401k is a marathon, not a sprint. The real winners aren’t those with the highest balances today, but those who started early and stayed disciplined through every market cycle.” — Ted Benna, architect of the Roth IRA and pioneer of 401k design
Major Advantages
- Tax efficiency: Pre-tax contributions reduce current taxable income, deferring payments until retirement when tax brackets may be lower.
- Employer matching: Free money from employers acts as an instant return on investment, often doubling contributions.
- Compound growth: Decades of tax-deferred compounding turn small, regular contributions into substantial sums over time.
- Portability: Rules allow transfers between jobs or to IRAs, ensuring savings aren’t stranded when employment changes.
- Flexibility: Hardship withdrawals (with penalties) and loans provide liquidity in emergencies, though they risk long-term growth.
- Automatic enrollment: Default participation in plans has increased savings rates, particularly among younger workers who might otherwise opt out.
Comparative Analysis
| Factor | Average 401k vs. IRA |
|---|---|
| Contribution Limits (2024) | 401k: $23,000 ($30,500 for 50+); IRA: $7,000 ($8,000 for 50+) |
| Employer Matching | 401k: Common (3–5% of salary); IRA: Never |
| Income Restrictions | 401k: None; IRA: Phase-outs at $146k (traditional) or $161k (Roth) |
Future Trends and Innovations
The average 401k is evolving beyond traditional boundaries. Automatic escalation—where contribution rates increase annually unless the employee opts out—is gaining traction, nudging workers toward higher savings without friction. Meanwhile, lifetime income options let retirees convert 401k balances into guaranteed payouts, addressing longevity risk. Fintech integration is also reshaping the landscape, with apps like Betterment and Fidelity offering AI-driven portfolio management tailored to retirement goals. Demographic shifts will further test the model. Millennials, now the largest 401k participant group, prioritize flexibility and may demand more investment options aligned with ESG (environmental, social, and governance) principles. Employers are responding with student loan repayment matches and healthcare FSA integrations, expanding the plan’s role beyond retirement. Yet challenges remain: rising healthcare costs and longer lifespans may outpace even robust savings. The average 401k of tomorrow will need to adapt—not just as a savings tool, but as a holistic financial lifeline.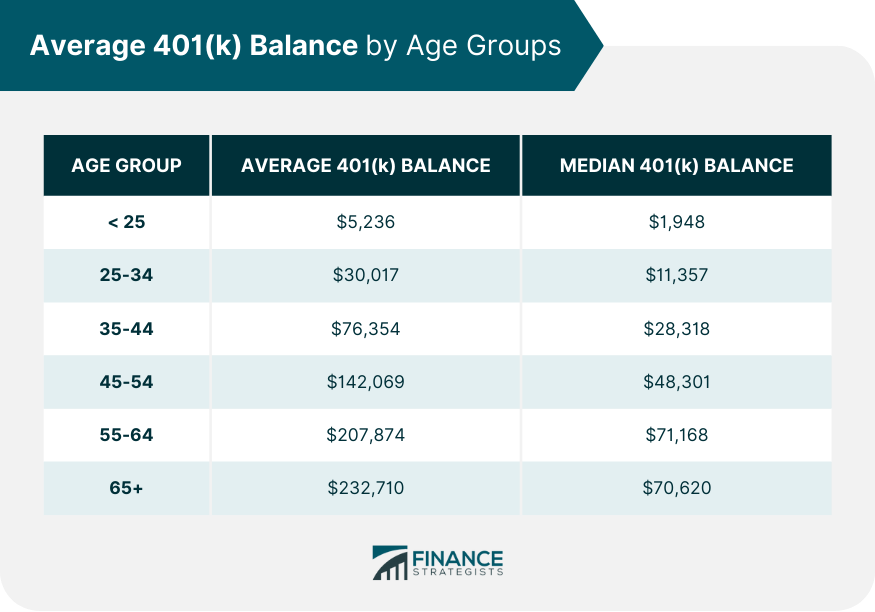
Conclusion
The average 401k balance is more than a number; it’s a reflection of economic participation, policy design, and personal discipline. For millions, it’s the primary vehicle for retirement security, but its limitations—fees, market risk, and systemic inequities—demand attention. The data shows that early, consistent contributions yield the best outcomes, yet too many workers are left behind by gaps in access or education. As the workforce diversifies and retirement expectations stretch longer, the average 401k will need to evolve from a static account into a dynamic, adaptive system. The conversation around retirement savings can’t stop at balances. It must address how to make the average 401k work for everyone—from the entry-level employee to the self-employed freelancer. The future isn’t just about growing larger balances; it’s about redefining what retirement security looks like in an era of uncertainty. For now, the numbers tell a clear story: the average 401k is a start, but the work of building true financial resilience has just begun.Comprehensive FAQs
Q: What is the average 401k balance by age group?
The latest data shows approximate balances by age:
- 20s: $20,000–$30,000
- 30s: $60,000–$80,000
- 40s: $120,000–$150,000
- 50s: $180,000–$220,000
- 60s+: $250,000+
Q: How does employer matching affect the average 401k?
Employer matching can double or triple effective contribution rates. For example, contributing 5% of a $70,000 salary ($3,500) with a 3% match adds $2,100—a 60% instant return. Over 30 years, this can add $200,000+ to a balance, assuming 7% annual growth. Workers who max out matches see the biggest boost to their average 401k growth.
Q: Can I have multiple 401k accounts?
Yes, but consolidating them is often wise. If you change jobs, you can roll over old 401k balances into a new employer’s plan or an IRA. Keeping multiple accounts can complicate management and may increase fees. The IRS allows contributions to multiple 401k plans, but the $23,000 annual limit applies across all employer-sponsored accounts.
Q: What happens to my 401k if I leave my job?
You have four options:
- Leave it with the former employer (if allowed).
- Roll it into your new employer’s 401k (if accepted).
- Transfer to an IRA (tax-free if rolled correctly).
- Cash it out (subject to taxes and a 10% penalty if under 59½).
Q: How do 401k loans impact my average balance?
Taking a 401k loan (up to $50,000 or 50% of your balance) reduces your account value immediately. You repay with interest, but missed contributions and market losses during repayment can permanently shrink your average 401k growth. If you leave your job while repaying, the loan may become a taxable distribution. Use loans only for true emergencies.
Q: Are Roth 401k contributions better than traditional?
It depends on your tax bracket now vs. in retirement. Roth contributions are made after tax, but withdrawals are tax-free—ideal if you expect higher taxes later. Traditional 401ks reduce taxable income now, benefiting those in higher brackets today. Many plans allow both, letting you split contributions strategically. For the average 401k, a mix often balances flexibility and tax efficiency.
Q: What’s the best investment mix for a 401k?
There’s no one-size-fits-all, but a common rule is:
- Ages 20–30: 80–90% stocks (growth focus).
- Ages 30–50: 60–70% stocks, 30–40% bonds.
- Ages 50+: 40–60% stocks, 40–60% bonds (conservative).
