
7 Things Worth Knowing About Median Net Worth American by Age
The data on median net worth American by age isn’t just numbers—it’s a mirror held up to America’s economic contradictions. From the racial wealth gap to the homeownership divide, these figures force a reckoning with who gets to build wealth and who gets left behind. Here’s what the numbers actually reveal.1. The Zero-to-$120K Leap (Ages 25–35)
Between 25 and 35, the median net worth American by age typically rises from near $0 to around $120,000—but this masks a brutal reality. For white households, this jump often comes from home equity, inheritance, or family investments. For Black and Hispanic households, the same period might see net worth stagnate or even decline due to higher student debt loads and lower asset accumulation. The Federal Reserve’s 2022 data shows that by age 32, white households hold $95,000 in median wealth, while Black households hold just $36,000—a gap that persists for decades. What’s less discussed is how this early advantage compounds. A home purchased at 28 with a $50,000 down payment (assisted by family) becomes a $200,000 asset by 35. Without that head start, renting for a decade means missing out on forced savings through equity. The median net worth American by age at 35 isn’t just about discipline; it’s about who gets the keys to the front door first.2. The Student Debt Tax (Ages 25–40)
Student loan balances now exceed $1.7 trillion, and their impact on median net worth American by age is undeniable. A 2023 Brookings Institution study found that borrowers under 40 with $50,000 in student debt have 40% less wealth than their debt-free peers. The effect isn’t just immediate—it ripples through life. Those who delay homebuying or starting families because of loan payments see their median net worth American by age suppressed for years. Even after repayment, the lost decade of compounded savings (from missed 401(k) contributions or home equity) can’t be recouped. The worst hit? Black borrowers, who carry $25,000 more in student debt on average than white borrowers by age 30, yet earn $17,000 less annually. This isn’t an accident—it’s the result of predatory lending practices targeting minority students and the erosion of public higher education funding over 40 years.3. The Homeownership Divide (Ages 35–50)
By age 40, homeownership becomes the single biggest driver of median net worth American by age. The Federal Reserve estimates that home equity accounts for 60% of total wealth for white households, compared to 40% for Black households. The gap isn’t just about prices—it’s about who gets approved for mortgages. A 2022 Urban Institute report found that Black and Hispanic borrowers are denied mortgages at twice the rate of white borrowers, even with identical credit scores. This isn’t historical—it’s happening today. For renters, the math is brutal. A 2023 Harvard Joint Center for Housing Study found that renters in their 40s accumulate $120,000 less wealth than homeowners by age 50. That’s not just lost equity—it’s lost leverage for future loans, lost tax benefits, and lost stability in an economy where housing costs now consume 30% of the average American’s income.4. The Retirement Cliff (Ages 55–65)
The median net worth American by age at 65 is where the cracks in the system become visible. While the national median hovers around $280,000, the reality is far more segmented. Households headed by someone over 65 with a college degree have $300,000 in median wealth; those without a degree have $150,000. The difference? Decades of wage stagnation, employer pension losses, and the shift from defined-benefit to defined-contribution plans. Social Security replaces only 40% of pre-retirement income for average earners—leaving a gap that retirement savings rarely close. What’s often overlooked is the longevity risk. Someone retiring at 65 today has a 75% chance of living to 85, meaning their savings must stretch 20 years longer than their parents’ did. Inflation erodes purchasing power at 3% annually, while healthcare costs rise at 6%. The median net worth American by age after 75 drops by 20% as savings are depleted, revealing how fragile retirement security really is.5. The Gender Wealth Gap (All Ages)
Women’s median net worth American by age is consistently 30% lower than men’s, and the gap widens with age. By 65, single women have $50,000 less in median wealth than single men. The reasons are systemic: the wage gap (women earn 82 cents for every dollar men earn), career interruptions for childbirth, and longer lifespans (women live 5 years longer, depleting savings faster). A 2023 study by the National Women’s Law Center found that 44% of women have no retirement savings at all, compared to 31% of men. The impact of divorce compounds this. Women lose 45% of their wealth in divorce settlements on average, while men gain 10%. By age 50, divorced women’s median net worth American by age is $20,000—half that of married women. This isn’t an individual failure; it’s the result of an economy that undervalues care work and penalizes women for biological realities.6. The Inheritance Advantage (Ages 45–70)
Inheritances now account for 30% of all intergenerational wealth transfers, and their impact on median net worth American by age is disproportionate. The Urban Institute estimates that $68 trillion will change hands over the next 30 years—$28 trillion to the richest 10% of Americans. For the top 1%, inheritances already make up 35% of their wealth. Meanwhile, 60% of Americans receive nothing. This isn’t just about large sums. Even a $50,000 inheritance at age 50 can double a household’s median net worth American by age, allowing them to buy a home, pay off debt, or invest. Without it, the same household would need 15 years of additional savings to reach the same milestone. The result? A wealth pyramid where the top 10% hold 70% of all liquid assets, while the bottom 50% hold 3%.7. The COVID-19 Reset (Ages 25–50)
The pandemic didn’t just disrupt earnings—it permanently altered the trajectory of median net worth American by age. A 2023 Federal Reserve study found that households headed by someone under 40 saw their median net worth drop by 25% between 2019 and 2021. The reasons? Job losses, evictions, and the $2.3 trillion in lost wages for workers without college degrees. Meanwhile, the top 10% saw their wealth increase by 37% during the same period, thanks to stock market gains and home value appreciation. The recovery hasn’t been equal. By 2023, the median net worth American by age 35 had rebounded to $110,000—but only for those who owned homes or stocks. Renters and gig workers saw their median net worth stagnate at $5,000, a level last seen in 2016. The pandemic didn’t create new rules—it exposed the old ones: who owns assets wins, and everyone else loses.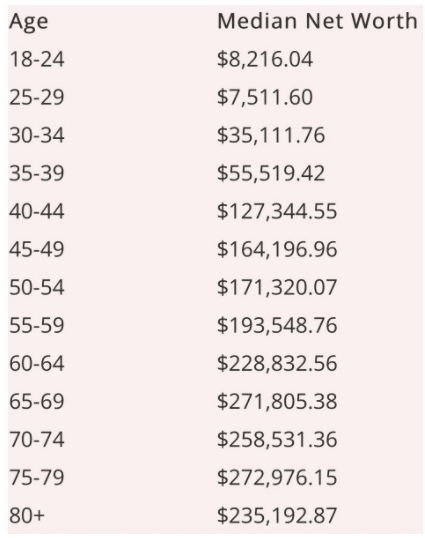
How These Facts Connect
The median net worth American by age isn’t a straight line—it’s a series of staircases, some with handrails, others with sheer cliffs. The data reveals an economy where wealth isn’t just earned; it’s inherited, borrowed against, or blocked by systemic barriers. The homeownership gap at 40 isn’t a personal failing—it’s the result of redlining, predatory lending, and the fact that white families have been building equity for four generations while Black and Hispanic families have been excluded for two. Student debt doesn’t just delay milestones; it reprograms the entire wealth trajectory, turning 20s of saving into decades of catch-up. What’s most striking is how these factors reinforce each other. A woman with student debt who can’t buy a home at 35 will earn less over her lifetime, delay retirement, and rely more on Social Security—only to live longer and deplete her savings faster. A Black borrower denied a mortgage at 40 will rent for another decade, missing out on the $120,000 in forced savings home equity provides. The median net worth American by age isn’t just about age—it’s about who you were born to, where you were born, and what risks you were forced to take. | Factor | Impact on Wealth (Ages 25–65) | Systemic Cause | |--------------------------|-----------------------------------------|--------------------------------------------| | Homeownership | +$300,000 (white) / +$150,000 (Black) | Redlining, mortgage discrimination | | Student Debt | -$120,000 in lifetime savings | Predatory lending, tuition hikes | | Inheritance | +$50K–$500K (top 10%) / $0 (bottom 50%) | Wealth concentration, estate tax loopholes | | Gender | Women: -30% median wealth | Wage gap, care work undervaluation | | COVID-19 | -25% wealth for under-40 households | Job losses, asset price inflation |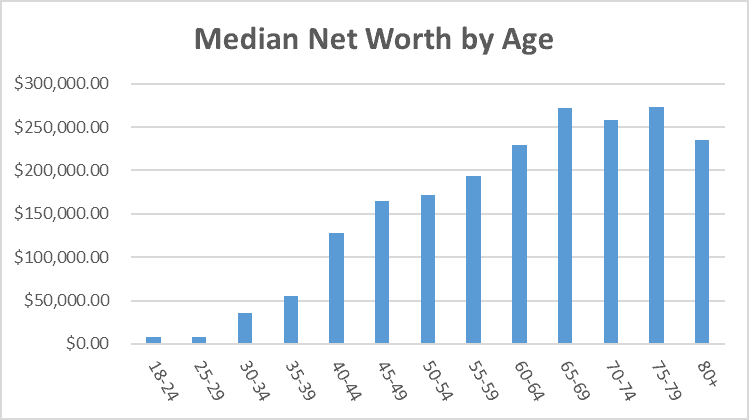
Conclusion
The median net worth American by age isn’t a personal failure—it’s a national ledger of who gets to play by the rules and who gets left holding the debt. The data doesn’t lie: wealth accumulates fastest for those who start with a head start, own assets early, and avoid the financial landmines that trip others. The question isn’t how to "get rich"—it’s how to navigate a system designed to favor some and penalize others. For policymakers, the answer lies in expanding homeownership access, reforming student debt, and closing the racial wealth gap—not through charity, but through structural change. For individuals, the message is clearer: the gap between $120,000 and $36,000 at age 35 isn’t about effort—it’s about opportunity. The good news? The system can be beaten. The bad news? The deck is stacked, and the house always wins.Comprehensive FAQs
Q: Why does the median net worth American by age vary so much by race?
The racial wealth gap is the result of centuries of policy, from slavery to redlining to predatory lending. A 2022 Brookings study found that white families today have 10 times the wealth of Black families—largely because white families received $156,000 in wealth from government policies (like GI Bill benefits, home loans, and tax breaks) over the past 50 years, while Black families received $9,000. Even when controlling for income, Black and Hispanic households accumulate wealth at half the rate of white households.
Q: Can someone with student debt ever catch up to the median net worth American by age?
Yes, but it requires aggressive strategies. The key is prioritizing high-earning careers (STEM, healthcare, law) to outpace debt payments, delaying major purchases (home, car, kids) until debt is cleared, and investing early in tax-advantaged accounts. A 2023 study by the Urban Institute found that borrowers who pay off loans in 5 years instead of 10 can increase their median net worth by $80,000 by age 40. However, this is far harder for low-wage borrowers, who may need public debt relief to break even.
Q: How does divorce affect the median net worth American by age?
Divorce erases decades of wealth accumulation. Women lose 45% of their wealth on average, while men gain 10%. By age 50, divorced women’s median net worth is $20,000—half that of married women. The reason? Alimony is rare (only 10% of divorces include it), child support is often underpaid, and women are more likely to reduce work hours during marriages, leading to lower Social Security benefits. A 2022 study by the National Women’s Law Center found that 60% of divorced women live in poverty within a year of separation.
Q: Why does homeownership matter so much for median net worth American by age?
Home equity is the single largest wealth-building tool in America. A homeowner’s net worth grows 40% faster than a renter’s, even when incomes are identical. The reason? Forced savings (mortgage payments build equity), tax benefits (mortgage interest deductions), and leverage (a $300,000 home can be refinanced for cash). Renters, meanwhile, pay $1,500/month in rent—money that disappears. A 2023 Harvard study found that renters in their 40s accumulate $120,000 less wealth than homeowners by age 50—even if they save 20% of their income.
Q: What’s the biggest myth about median net worth American by age?
The biggest myth is that wealth is purely a product of hard work and discipline. The data shows that 90% of wealth accumulation comes from three factors: inheritance, homeownership, and stock market gains—none of which are equally accessible. A 2022 Federal Reserve study found that parents who receive inheritances are 30% more likely to leave their children wealthier than those who don’t. Meanwhile, 60% of Americans have no retirement savings—not because they’re irresponsible, but because the system doesn’t give them a chance. The median net worth American by age isn’t a personal failure; it’s a structural outcome.
Q: How does inflation affect the median net worth American by age?
Inflation erodes wealth silently. Since 1980, real wages have stagnated, while housing costs have risen 2.5x faster than inflation. This means that a $100,000 net worth at 35 in 1990 would need to be $250,000 today to have the same purchasing power. For retirees, the impact is worse: healthcare costs rise at 6% annually, while Social Security benefits only adjust for inflation. A 2023 AARP study found that 65% of retirees say inflation has delayed retirement or forced them to dip into savings. The median net worth American by age 75 drops by 20% as savings are depleted faster than expected.
Q: Are there any bright spots in the median net worth American by age data?
Yes—two key trends stand out. First, homeownership rates among young Black and Hispanic households are rising, thanks to down payment assistance programs and community land trusts. Second, women’s wealth is growing faster than men’s in some age groups, particularly 30–45, as more women enter high-earning fields and delay marriage to focus on careers. However, these gains are fragile—a single financial shock (job loss, medical debt) can erase years of progress. The real bright spot? Policy changes work. After the Community Reinvestment Act (1977), Black homeownership rates rose 15% in a decade. The question is whether America will repeat that success or double down on the status quo.
