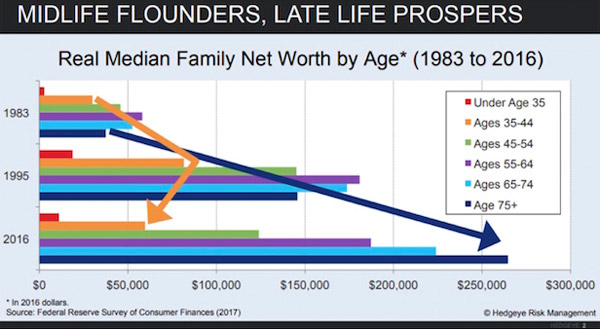
Common Myths About Median Family Net Worth by Age
The first misconception is that these figures represent what’s normal for most people. They don’t. The median is the point where half the population has more and half has less—meaning the "average" family at any given age could be far wealthier or far poorer. For example, a 45-year-old with a $500,000 net worth might seem like a success story, but in a high-cost city, that could still mean struggling to afford healthcare. Conversely, a $200,000 net worth in a low-cost area might be a sign of financial security. The median family net worth by age is a snapshot, not a benchmark. Another persistent myth is that wealth grows linearly with age. The data shows sharp inflection points—particularly around homeownership milestones. A 35-year-old who just bought a home might see their net worth spike, while a 55-year-old whose parents helped with a down payment could appear wealthier than a peer who didn’t. The Fed’s data doesn’t account for these variables, yet they explain why two people the same age can have wildly different financial pictures. Even more glaring is the assumption that early-career debt—student loans, credit cards—is temporary. For many, it’s not. A 2023 study found that 40% of borrowers over 60 still carry student debt, dragging down their median family net worth by age well into retirement. The third myth is that these numbers reflect personal responsibility alone. Structural factors—wage stagnation, healthcare costs, and the rising cost of housing—play a far larger role than lifestyle choices. A 30-year-old in 1990 had a far easier path to homeownership than one today, even with identical incomes. The median family net worth by age isn’t just about saving habits; it’s about the economic rules of the game. Ignoring that leads to simplistic advice like "just save more," which misses the point entirely.Myth 1: "By 40, you should have X amount saved."
This is the most dangerous myth because it’s often tied to financial planning tools that use median figures as targets. The reality? The median net worth at 40 is around $120,000—but that’s before accounting for regional cost of living, family size, or unexpected expenses. A couple in Austin with two kids might need twice that just to break even, while a single person in Detroit could retire comfortably on half. The median family net worth by age is a statistical average, not a personal goalpost. What’s more, the "X amount" in these rules of thumb rarely factors in inflation or the fact that a 40-year-old today faces a housing market that’s 30% more expensive than in 2000, adjusted for wages. The bigger issue is that these targets ignore liquidity. A homeowner’s net worth might look solid on paper, but if their mortgage is still active, their usable wealth is far lower. The Fed’s data lumps home equity into net worth without distinguishing between leveraged and unleveraged assets. A 40-year-old with a paid-off home is in a completely different position than one with a $300,000 mortgage—yet both could have the same reported net worth. This is why financial advisors increasingly argue that net worth alone is a poor measure of financial health. It’s the composition of that wealth—cash reserves, debt levels, and income stability—that matters.Myth 2: "Wealth compounds smoothly after 50."
The narrative that wealth accelerates after 50 is partially true, but it’s also a story of haves and have-nots. The median net worth does climb sharply in the 50s and 60s, but that’s largely because homeownership rates peak and retirees tap into 401(k)s. What it doesn’t show is that many in this age group are still paying off debt—whether it’s student loans, medical bills, or caregiving expenses for aging parents. A 2022 analysis of Fed data revealed that 28% of households headed by someone 55–64 had zero or negative net worth, often due to outstanding loans. The median family net worth by age smooths over these outliers, making it seem like everyone is cruising toward retirement security when, in fact, a significant portion are playing catch-up. Even for those who do accumulate wealth, the trajectory isn’t always upward. The 2008 financial crisis wiped out decades of progress for many near-retirees, and the COVID-19 pandemic did the same in 2020. The Fed’s most recent data shows that net worth for those 65–74 dropped by 12% in 2022 alone, thanks to market volatility and rising living costs. The myth of smooth compounding ignores the fact that wealth isn’t just about saving—it’s about avoiding catastrophic losses. A 60-year-old with a diversified portfolio might see their net worth grow, while a peer who put everything into a single stock or a leveraged home could face a steep decline.Myth 3: "Young people today are worse off than past generations."
This is the generation war myth par excellence. Proponents point to stagnant wages and student debt to argue that median family net worth by age has stalled for Millennials and Gen Z. But historical data tells a different story. Adjusting for inflation, a 30-year-old in 1989 had a median net worth of about $50,000—roughly half of what a 30-year-old has today. The difference? Homeownership rates for young adults have plummeted, from 45% in 1990 to 37% in 2023, thanks to skyrocketing prices. Without home equity, liquid net worth—cash, investments, and retirement accounts—looks far weaker. Yet even here, the comparison is flawed. A 30-year-old in 2023 has access to retirement accounts like 401(k)s and HSAs, which didn’t exist in the 1980s. The median family net worth by age isn’t just about dollars; it’s about the tools available to accumulate them. The real issue is that young people today are entering adulthood later. The average age of first marriage has risen from 23 to 30 for women since 1990, delaying home purchases and family formation—both of which boost net worth. The myth of decline ignores that younger generations are also more likely to invest in assets like index funds and cryptocurrency, which can outpace traditional savings. The median tells us little about these shifts because it’s a static snapshot. What it does reveal is that the traditional path to wealth—homeownership, steady employment, and marriage—is no longer the only path. For many, the journey looks entirely different.
What Holds Up to Scrutiny
The one undeniable truth about median family net worth by age is that homeownership is the single biggest driver of wealth accumulation. The Fed’s data shows that homeowners at every age have net worths five to ten times higher than renters. This isn’t just about the value of the home; it’s about the forced savings mechanism of a mortgage and the equity that builds over time. The problem? Homeownership is increasingly out of reach for younger generations. In 2023, the median home price exceeded $400,000 in over half of U.S. counties, meaning a 20% down payment alone requires $80,000 in savings—something only about 25% of 30-year-olds have. This structural barrier explains why the median net worth gap between homeowners and renters widens with age. What else holds up? The role of inheritance and family transfers. While the Fed’s data doesn’t track this directly, studies estimate that inheritance accounts for 20–30% of wealth for households in the top quartile. For families with modest means, even a small inheritance can push them into a higher net worth bracket. This is why the median family net worth by age looks so different across racial and ethnic groups: wealth is passed down along lines of historical advantage and disadvantage. A Black family’s median net worth is about one-tenth that of a white family at the same income level, largely due to the wealth gap created by redlining, predatory lending, and the inability to build generational equity."Net worth is a lagging indicator of financial health. It tells you where you’ve been, not where you’re going." — Darrick Hamilton, economist and director of the Institute on Assets and Social Policy
| Common Belief | What the Evidence Says |
|---|---|
| "By 35, you should have saved 1x your salary." | The median 35-year-old has a net worth of ~$120,000, but this includes home equity. Excluding homes, liquid savings are far lower—often under $20,000. |
| "Wealth doubles every decade after 40." | For the median household, net worth grows by about 50% between 40 and 50, but this masks stagnation for those with high debt or no homeownership. |
| "Retirees are financially secure." | 20% of households headed by someone 65+ have zero or negative net worth, often due to medical debt or reverse mortgages. |
| "Student debt hurts young people more than older borrowers." | While younger borrowers carry more debt, older borrowers (50+) hold 40% of all student loan debt and are more likely to default. |
| "The median net worth by age is the same across regions." | In San Francisco, a 45-year-old’s median net worth is ~$1.2M; in Mississippi, it’s ~$150,000—a difference driven by housing costs and wage gaps. |
Why the Confusion Persists
Part of the problem is that financial literacy education treats net worth as a personal failing rather than a systemic issue. Most advice focuses on budgeting and investing, ignoring the fact that the median family net worth by age is heavily influenced by factors outside an individual’s control. Housing policy, wage growth, and healthcare costs are determined by macroeconomic forces, yet they shape personal finances more than any 401(k) match or side hustle. Another issue is the way data is reported. The Fed’s survey is conducted every three years, meaning the most recent snapshot might be three years out of date by the time it’s analyzed. In a market as volatile as housing, that lag can obscure critical trends. There’s also the psychological factor: people want to believe in a meritocratic narrative where hard work leads to wealth. The median family net worth by age reinforces this idea—until you dig deeper. The reality is that wealth is sticky. A family that starts with $50,000 in net worth at age 30 is likely to have $200,000 by age 60, even if they earn the same income as a peer who starts at $10,000. The gap doesn’t close; it widens. This is why policies like child tax credits, student debt relief, and down payment assistance—though politically contentious—have such outsized impacts on long-term wealth accumulation. The confusion persists because acknowledging these realities forces a reckoning with structural inequality, and that’s a conversation many would rather avoid.
Conclusion
The median family net worth by age is a useful tool, but it’s a blunt one. It tells us that wealth tends to accumulate with time, that homeownership is the great equalizer (when accessible), and that older generations still hold an edge in asset accumulation. But it also obscures the fact that the rules of the game have changed. A 30-year-old today faces a housing market that’s 10 times more expensive than in 1980, adjusted for wages. A 50-year-old with student debt is in a very different position than one without. The median doesn’t explain why a single mother in Chicago has a net worth 60% lower than a single father in the same city, or why a couple in their 60s might still be paying off a mortgage while their peers have retired. The takeaway isn’t to dismiss the data—it’s to use it wisely. If you’re 35 and your net worth is below the median, that doesn’t mean you’re failing. It might mean you’re renting in a high-cost area, or that you’re paying off student loans, or that you’re supporting aging parents. The median family net worth by age is a starting point, not a verdict. The real question isn’t whether you’re on track, but whether your wealth is working for you—not just growing on paper. For most people, that means diversifying assets, reducing debt, and—when possible—building equity in a home or business. The numbers don’t lie, but they don’t tell the whole story either.Comprehensive FAQs
Q: How accurate is the Federal Reserve’s median net worth data?
The Fed’s Survey of Consumer Finances is the most reliable source, but it has limitations. It’s conducted every three years, uses a rotating sample, and relies on self-reported data, which can be skewed. Additionally, it doesn’t track wealth in certain high-net-worth households due to privacy protections. For trends, it’s gold standard; for personal comparisons, it’s less precise.
Q: Does the median net worth by age vary significantly by race?
Yes. The median net worth for white households is $188,200, compared to $24,100 for Black households and $36,100 for Hispanic households, according to the Fed’s 2022 data. This gap is driven by historical factors like redlining, wealth stripping through predatory lending, and lower homeownership rates among minority groups.
Q: Can I use the median net worth by age to set personal financial goals?
Not directly. The median is a statistical average, not a personal benchmark. A better approach is to compare your net worth to your own past progress or to peer groups with similar incomes and living costs. Tools like the "net worth by age calculator" often use outdated or oversimplified assumptions.
Q: Why does the median net worth drop for some age groups?
This usually happens due to major economic shocks (like the 2008 crash or 2020 pandemic), medical debt, or caregiving expenses. For example, net worth for those 55–64 dropped in 2022 because many were forced to dip into savings to cover healthcare costs or support adult children. It’s not a sign of poor financial management—often, it’s a sign of systemic pressures.
Q: How does student debt affect the median net worth by age?
It delays wealth accumulation. A 2023 study found that borrowers under 30 had 30% lower median net worth than non-borrowers, even after controlling for income. The impact persists: those 40–50 with student debt have net worths 20% lower than peers without it. The longer the debt, the more it compounds against asset-building.
Q: Are there regional differences in median net worth by age?
Massive. In high-cost areas like San Francisco or New York, a 45-year-old’s median net worth can exceed $1.5 million, largely due to home equity. In lower-cost states like Mississippi or West Virginia, it’s closer to $150,000–$200,000. Wage growth, housing markets, and local taxes play a far bigger role than age alone.
Q: Does marriage or having children affect the median net worth by age?
Yes, but the effect varies. Couples typically accumulate wealth faster due to dual incomes, but the cost of raising children can offset this. A 2021 analysis found that parents had 15% lower median net worth than childless peers at the same age, largely due to higher education and healthcare expenses. However, married couples without children often see higher net worth due to shared financial strategies.
Q: Can I improve my net worth trajectory if I’m behind the median?
Absolutely, but the strategies depend on your situation. For renters, prioritizing high-yield savings or index funds can help. For homeowners, refinancing or downsizing to a lower-cost area may free up cash flow. The key is reducing high-interest debt and increasing liquid assets—not just chasing the median. Inheritance or windfalls (like a bonus) can also provide a critical boost.
