Breaking Down the Numbers
The average middle class net worth by age isn’t a single, static number but a series of benchmarks that shift with economic conditions. For decades, researchers have tracked these figures through surveys like the Federal Reserve’s Survey of Consumer Finances, which provides the most granular snapshot of U.S. household wealth. The data shows that by age 35, the median net worth for middle-class households hovers around $92,000, a figure that includes primary residences, retirement accounts, and liquid savings. Yet this average masks critical disparities: Black and Hispanic households at the same age report net worths roughly half that of white households, a divide that widens with each passing decade. What’s often overlooked is how these figures reflect broader structural issues. The post-2008 recovery, for example, didn’t just leave scars on high-net-worth individuals—it reset the baseline for middle-class wealth accumulation. Home values, the single largest asset for most households, took years to rebound, delaying the wealth-building cycle for an entire generation. Meanwhile, the rise of gig economy jobs and the erosion of defined-benefit pensions have forced middle-class families to adopt new strategies for retirement planning, often with mixed results. The average middle class net worth by age isn’t just a personal finance metric; it’s a reflection of how well—or poorly—an economy is equipping its citizens to weather financial volatility.The Verified Baseline
The most reliable data on average middle class net worth by age comes from longitudinal studies, particularly those conducted by the Federal Reserve and the Pew Research Center. According to the Fed’s 2022 report, the median net worth for households headed by someone aged 32–47—peak earning years—is estimated at $120,000, though this includes both homeowners and renters. For homeowners in this age bracket, the figure jumps to $180,000, underscoring how real estate remains the primary wealth multiplier. What’s less discussed is the decline in mobility: younger middle-class households today are less likely to "move up" into higher wealth brackets than previous generations, a trend linked to rising costs of education and healthcare. Publicly available data also highlights the non-linear growth of net worth. A 50-year-old with no college debt and steady employment can see their net worth double from age 35 to 50, but this trajectory is far from universal. The Fed’s data shows that 20% of middle-class households aged 45–54 have net worth below $25,000, often due to medical debt, divorce, or career disruptions. These outliers aren’t anomalies; they’re symptoms of a system where middle-class stability is increasingly fragile.What the Estimates Suggest
Beyond verified benchmarks, industry estimates paint a more nuanced picture of middle-class wealth accumulation by age. Consulting firms like McKinsey and the Urban Institute suggest that by age 60, the average middle-class net worth for homeowners could range between $250,000 and $400,000, depending on regional housing markets and retirement savings contributions. However, these figures assume consistent employment and no major financial setbacks—a scenario that’s become increasingly rare. For renters, the estimates drop sharply, with net worth often stagnating below $50,000 unless they’ve aggressively saved or received intergenerational support. What’s particularly telling is how these estimates diverge by generation. Millennials, now in their 30s and 40s, are entering the wealth-building phase with lower starting net worth than Gen X did at the same age, according to estimates from the Brookings Institution. The gap is attributed to higher education costs, lower homeownership rates, and the delayed life milestones (marriage, children) that historically correlated with wealth accumulation. Even optimistic projections for Gen Z suggest their average middle-class net worth by age 40 will lag behind their predecessors by 15–20%, absent significant policy or economic shifts.
Case Study: A Closer Look
Consider the experience of the Smith family—a middle-class household in Chicago with two incomes, a mortgage, and a 10-year-old child. At age 35, their net worth sits at $110,000, a figure that includes a $200,000 home (with $150,000 remaining on the mortgage), $30,000 in retirement accounts, and $15,000 in liquid savings. Their trajectory follows the verified baseline, but the path hasn’t been smooth. A medical emergency in their mid-30s drained their emergency fund, forcing them to rely on credit cards—a move that added $8,000 in debt. By age 45, their net worth had grown to $220,000, but the increase was slower than expected due to stagnant wages and rising childcare costs. What sets the Smiths apart is their proactive approach to debt management. They refinanced their mortgage at a lower rate, paid off the credit card balance in three years, and increased their 401(k) contributions by 5%. Their story illustrates how small financial adjustments can mitigate the impact of external shocks on middle-class wealth accumulation. Yet it’s also a cautionary tale: had they faced a job loss or a housing market downturn, their progress could have stalled entirely."We thought we were doing everything right—saving, investing, paying down debt. But one bad year can unravel a decade of planning. The system isn’t designed to protect people like us." — Sarah Smith, 47, Chicago
| Factor | Estimated Impact on Net Worth Growth |
|---|---|
| Mortgage Refinancing (Rate Drop) | Added $12,000 in equity over 5 years by reducing monthly payments. |
| Medical Debt (Credit Card Use) | Temporarily reduced net worth by $8,000 but was repaid within 3 years. |
| 401(k) Contribution Increase | Projected to add $45,000 in retirement savings by age 60, assuming 7% annual return. |
What This Means Going Forward
The average middle class net worth by age isn’t just a personal finance issue—it’s a leading indicator of economic resilience. As automation and AI reshape labor markets, middle-class households will need to adapt strategies that were once considered conservative: diversifying income streams, prioritizing liquidity over home equity, and planning for longer retirement phases. The data suggests that the traditional "save-and-invest" model is no longer sufficient; flexibility will be the new currency of financial stability. Policy changes could also reshape these trajectories. Expanded access to affordable childcare, student debt relief, and healthcare reform could accelerate wealth accumulation for younger middle-class families. Conversely, stagnant wages and asset inflation (like soaring home prices) threaten to widen the gap between those who inherit wealth and those who must build it from scratch. The average middle class net worth by age will continue to reflect these broader trends, serving as both a mirror and a warning.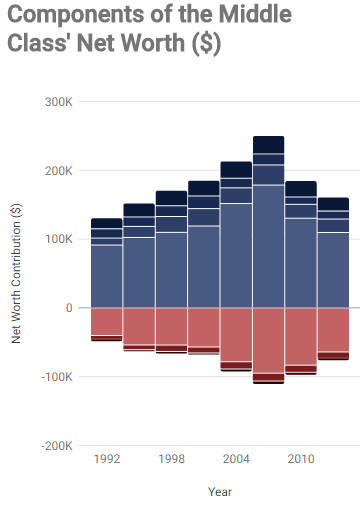
Conclusion
The story of middle-class wealth accumulation by age is one of incremental progress punctuated by sudden setbacks. It’s a narrative of resilience, but also of systemic barriers that too often go unnoticed. The numbers tell us that by age 60, the median middle-class household should have a net worth that provides a measure of security—but only if they’ve navigated the pitfalls of debt, healthcare, and housing volatility. For many, the reality falls short, not due to personal failure, but because the rules of the game have changed. What’s clear is that the average middle class net worth by age can no longer be treated as a fixed benchmark. It’s a dynamic metric, shaped by policy, technology, and global economic forces. The households that thrive will be those who treat financial planning as an ongoing dialogue—not a one-time calculation—between their goals and the realities of an uncertain future.Comprehensive FAQs
Q: How does student debt affect the average middle class net worth by age?
The impact is significant and long-term. Households with student debt report median net worths 40% lower by age 40 compared to those without, according to Federal Reserve data. The burden extends beyond repayment: borrowers are more likely to delay home purchases, retirement savings, and even starting families, all of which suppress long-term wealth growth.
Q: Why do homeowners have such a higher average net worth than renters at the same age?
Homeownership is the single most effective wealth-building tool for middle-class families. A primary residence typically appreciates over time, builds equity through mortgage payments, and provides tax benefits. Renters, meanwhile, lack this asset appreciation and often face rising costs without building transferable wealth. Studies show that homeownership can add $100,000+ to a household’s net worth over 30 years, even after accounting for maintenance and property taxes.
Q: Does marriage or having children significantly alter the average middle class net worth by age?
Yes, but the effect varies. Couples often pool resources, increasing savings rates, but also face higher expenses (housing, childcare, healthcare). Data from the Urban Institute suggests that middle-class households with children see a 10–15% dip in net worth growth in the years immediately after having kids, though this gap narrows as children age. The key factor is whether the additional costs are offset by increased income or shared financial responsibilities.
Q: How do healthcare costs factor into the average middle class net worth by age?
Healthcare is the wild card in middle-class wealth trajectories. A single medical event—such as a cancer diagnosis or chronic illness—can wipe out years of savings. The Kaiser Family Foundation estimates that 25% of middle-class households aged 55–64 have medical debt, which often leads to credit card reliance or reduced retirement contributions. Unlike other expenses, healthcare costs are unpredictable and rarely covered by emergency funds.
Q: Can someone in their 50s still improve their average middle class net worth by age 65?
Absolutely, but the strategies differ from earlier life stages. The most effective levers at this point are debt elimination, Social Security optimization, and downsizing housing costs. For example, refinancing a mortgage or selling a home to downsize can free up cash flow for retirement accounts. The Federal Reserve’s data shows that households aged 55–64 who aggressively pay down debt see net worth growth rates 20% higher than those who don’t, even in the face of stagnant wages.
Q: How does geographic location influence the average middle class net worth by age?
Location is one of the strongest predictors of wealth accumulation. Middle-class households in high-cost areas like California or New York often see slower net worth growth due to housing expenses, while those in lower-cost regions (e.g., Midwest, South) build equity faster. A 2023 study by Zillow found that the median net worth for a 45-year-old homeowner in Dallas is 30% higher than for one in San Francisco, even with similar incomes. This disparity is driven by housing costs, local tax policies, and job market stability.
