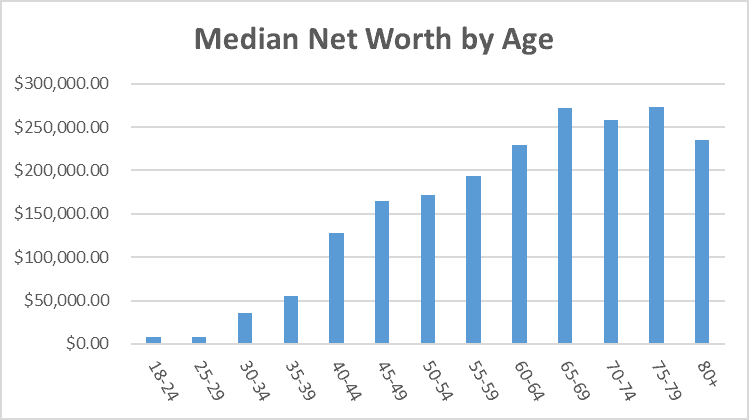
6 Things Worth Knowing About Average Median Net Worth by Age
The average median net worth by age isn’t a straight line—it’s a jagged curve with sharp turns at critical life stages. These six insights cut through the noise to reveal what the data actually shows, not what conventional wisdom claims.1. The First Decade: Where Most People Start at Zero (or Negative)
Between ages 25 and 34, the median net worth by age hovers near $50,000 in the U.S., but the reality is far more polarized. For those with student loans or medical debt, net worth can dip into negative territory. The Federal Reserve’s 2022 report confirms that average net worth by age 30 for the bottom 50% of households is often under $10,000—meaning half of young adults have little to no cushion for emergencies. This isn’t laziness; it’s the cost of higher education, rising rents, and wages that haven’t kept pace with essential expenses. The myth of the "hustle culture" young professional obscures a harder truth: net worth accumulation by age in this bracket is heavily influenced by family support. A 2023 Pew Research study found that 60% of millennials receiving financial help from parents were able to buy a home by 35, compared to just 20% of those who went it alone. The starting line isn’t level—and the gap only deepens with time.2. The 35-44 Window: When Real Estate Becomes the Great Divider
Homeownership is the single biggest accelerator of median net worth by age in this cohort. According to Zillow, homeowners in their late 30s see their average net worth by age surge by 30% annually compared to renters. But here’s the catch: only 65% of Americans under 40 own a home, and for minorities, that rate drops to 45%. The median net worth by age 40 for a white household is nearly double that of a Black household, even when controlling for income—a disparity rooted in redlining, predatory lending, and generational wealth gaps. The data also reveals a geographic split. In high-cost cities like San Francisco or New York, a 40-year-old’s net worth by age may stagnate due to housing costs eating into savings. Meanwhile, in Sun Belt states, the same age group sees their average median net worth by age grow faster thanks to lower entry costs and appreciation. Location isn’t just about opportunity; it’s about who gets to participate in the wealth-building game.3. The 45-54 Pivot: When Investments Outpace Savings
This is the age where net worth by age growth accelerates for those who’ve played the long game. The median jumps from around $160,000 at 45 to $250,000 by 54, but the real story is in the tails. The top 10% see their average median net worth by age in this bracket exceed $1.5 million, thanks to stock portfolios, business ownership, and inherited assets. Yet the bottom 25%? Their median net worth by age remains flat or declines due to caregiving costs, divorce, or market downturns hitting late-career savers hardest. A 2024 study from the Urban Institute found that net worth accumulation by age in this group is heavily skewed by employer retirement plans. Those with access to 401(k) matches or defined-benefit pensions see their average median net worth by age rise 40% faster than peers without such benefits. The message is clear: median net worth by age isn’t just about personal discipline—it’s about the institutions that either propel or abandon you."Wealth isn’t just about how much you earn; it’s about how the system lets you keep what you earn." — Darrick Hamilton, economist and author of Zillionaire$
4. The 55-64 Cliff: When Pensions and Politics Collide
This is where the average median net worth by age curve takes its sharpest turn. For Boomers, Social Security and pensions bridge the gap, pushing median net worth by age 60 to around $280,000. But for Gen Xers, the picture is bleaker: 40% lack retirement savings entirely, and their average net worth by age at 60 sits at just $120,000. The reason? The collapse of defined-benefit plans, the 2008 financial crisis, and the rise of 401(k)s that require individual management—a system that rewards those with financial literacy and penalizes everyone else. Politics plays a hidden role here. States with strong public pension systems (like California or New York) see higher median net worth by age for public-sector workers, while right-to-work states show wider disparities between unionized and non-unionized retirees. The net worth by age gap isn’t just economic; it’s a reflection of who lobbied for policies that protected (or dismantled) collective bargaining and defined benefits.5. 65 and Beyond: The Retirement Paradox
Conventional wisdom says net worth by age 70 should peak, but the data tells a different story. The median jumps to $365,000, but the distribution is bizarre: the top 5% see their average median net worth by age exceed $3 million, while the bottom 20% have less than $50,000. Here’s the paradox: median net worth by age in retirement isn’t just about savings—it’s about longevity and healthcare costs. A 65-year-old in good health with a pension may see their net worth by age grow due to home equity or part-time work, while someone with chronic illness or long-term care expenses can hemorrhage assets in months. The average net worth by age for seniors is also a story of geography. In Florida or Arizona, where retirees flock for lower taxes, median net worth by age can appear higher due to home values—but the trade-off is higher insurance and healthcare costs. Meanwhile, in states with strong Medicaid programs, the net worth by age of low-income seniors declines less sharply because safety nets kick in.6. The Silent Generation’s Legacy: How Wealth Skips Generations
The median net worth by age for those 75+ is a testament to the power of inheritance. The average hovers around $400,000, but the real outlier is the average net worth by age for heirs: 30% of wealth transfers in the U.S. happen at death, and these sums often dwarf what the deceased accumulated in a lifetime. The net worth by age data for this group reveals a brutal truth: median net worth by age isn’t just about individual effort—it’s about who you’re born to. A 2023 study from the Brookings Institution found that average median net worth by age for those with parents in the top 1% is 10 times higher than for peers whose parents were in the bottom 50%. This isn’t just about money left in wills. It’s about the intangibles: the down payment help, the business connections, the "I’ll take care of you" that never appears in balance sheets. The net worth by age gap between those who inherit and those who don’t isn’t a bug in the system—it’s the system itself.
How These Facts Connect
The average median net worth by age isn’t a series of isolated data points—it’s a feedback loop where early advantages compound into later dominance. Homeownership at 35 doesn’t just boost net worth by age; it opens doors to better schools, safer neighborhoods, and tax benefits that further accelerate median net worth by age growth. Skip that milestone, and the dominoes fall: lower credit scores, fewer investment opportunities, and a net worth by age trajectory that flattens by 50. But the system isn’t neutral. The average median net worth by age curve bends upward for those who benefit from employer-sponsored plans, inherited wealth, or low-cost housing—but it’s a cliff for everyone else. The data doesn’t lie: median net worth by age is higher for white households, for urban professionals, for those with college degrees. These aren’t coincidences; they’re the result of policies that subsidize homeownership, tax breaks for capital gains, and a labor market that rewards credentials. The net worth by age gap isn’t a personal failing—it’s a structural one. | Age Bracket | Key Driver of Wealth | Median Net Worth Gap | Systemic Lever | |-----------------|----------------------------------|--------------------------------|----------------------------------| | 25-34 | Student debt vs. parental help | $30,000 (white vs. Black) | Redlining, loan forgiveness | | 35-44 | Homeownership access | $150,000 (owner vs. renter) | FHA loans, zoning laws | | 45-54 | Employer retirement plans | $500,000 (union vs. non-union) | Pension protections | | 55-64 | Pension vs. 401(k) risk | $200,000 (public vs. private) | Defined-benefit phase-out | | 65+ | Inheritance and healthcare | $1M+ (heirs vs. non-heirs) | Estate tax loopholes | The table above isn’t just numbers—it’s a ledger of who gets to play by whose rules. The average median net worth by age isn’t a measure of merit; it’s a measure of access.
Conclusion
The average median net worth by age tells us two things: wealth is a team sport, and the team you’re on depends on where you started. Ignoring this reality—whether as policymakers, financial advisors, or individuals—means accepting a system where luck masquerades as effort. The data doesn’t offer easy fixes, but it does demand honesty: net worth by age isn’t just about budgeting apps or side hustles. It’s about the zip code you were born into, the color of your skin, the stability of your job, and the generosity of your ancestors. For those who’ve seen their median net worth by age grow as planned, the takeaway is simple: average net worth by age is a privilege, not a right. For those who’ve been left behind, the numbers are a wake-up call. The system isn’t broken—it’s working exactly as designed. The question is whether we’ll redesign it.Comprehensive FAQs
Q: How does inflation distort the "average median net worth by age" data?
The average median net worth by age figures are often reported in nominal terms, meaning they don’t account for inflation. For example, a median net worth by age 50 of $250,000 in 1990 would be worth roughly $500,000 today when adjusted for inflation. However, wage stagnation means that net worth by age growth hasn’t kept pace with asset appreciation for most Americans. Real estate and stock markets have outpaced wages, widening the median net worth by age gap between homeowners and renters, or investors and non-investors.
Q: Why does the "average median net worth by age" vary so much by state?
Geography is the single biggest wild card in average median net worth by age calculations. States with high homeownership rates (like South Dakota or West Virginia) see higher median net worth by age for older cohorts because housing equity is a major wealth driver. Conversely, high-cost states like California or New York show lower net worth by age for younger groups due to housing costs eating into savings. Tax policies also play a role: states with no income tax (like Texas) may have higher average median net worth by age for retirees, while progressive tax states (like New Jersey) see wealth concentrated among the top earners.
Q: Can someone in their 30s realistically catch up to the "average median net worth by age" for their cohort?
It’s possible, but the odds are stacked against those starting from scratch. The median net worth by age 35 is around $70,000, but catching up requires aggressive moves: refinancing high-interest debt, maximizing retirement contributions, and—critically—access to low-cost housing or family support. A 2023 study from the St. Louis Fed found that net worth by age growth slows after 40 unless you inherit, receive a windfall, or enter a high-earning profession. For most, the average median net worth by age trajectory is less about effort and more about timing and structural advantages.
Q: How does student loan debt impact the "average median net worth by age"?
Student debt is the ultimate wealth destroyer for younger cohorts. The average median net worth by age 30 for someone with $50,000 in student loans is roughly 40% lower than for a peer with no debt, according to the Federal Reserve. The drag effect persists: borrowers see their net worth by age grow 2-3% slower annually due to higher interest payments and delayed homeownership. Worse, student loans can’t be discharged in bankruptcy, meaning the median net worth by age penalty lasts decades. Policies like income-driven repayment help, but they also extend the debt burden, keeping average net worth by age suppressed for an entire generation.
Q: What’s the biggest myth about "average median net worth by age"?
The biggest myth is that average median net worth by age is a direct reflection of personal responsibility. The data shows that net worth by age is far more influenced by inherited wealth, employer benefits, and access to low-cost housing than by spending habits. For example, two 40-year-olds with identical salaries may have median net worth by age figures that differ by $200,000 simply because one inherited a down payment from parents while the other paid off student loans alone. The average net worth by age narrative often ignores these systemic levers, framing financial struggles as moral failures rather than structural barriers.
Q: How does divorce affect the "average median net worth by age"?
Divorce can derail net worth by age trajectories, especially for women. Studies show that divorced individuals see their median net worth by age drop by 20-30% compared to married peers, with women bearing the brunt due to wage gaps and alimony obligations. The impact is most severe for those in their 40s and 50s, where average median net worth by age is already concentrated in shared assets like homes. Remarriage can help, but the net worth by age penalty often persists because of legal fees, split retirement accounts, and the loss of spousal Social Security benefits. For many, divorce isn’t just a personal crisis—it’s a financial reset that sets back median net worth by age by a decade or more.
Q: Are there any bright spots in the "average median net worth by age" data?
Yes—two stand out. First, net worth by age growth for Black and Hispanic households has accelerated slightly in recent years, thanks to rising home values and targeted financial literacy programs. Second, younger cohorts (Gen Z and younger millennials) are entering the workforce with higher financial awareness, leading to better credit scores and earlier savings habits—though this hasn’t yet translated into higher median net worth by age due to stagnant wages. The brightest spot? Cities with strong rental assistance programs and first-time homebuyer grants are seeing narrower average median net worth by age gaps between racial groups, proving that policy changes can move the needle.
