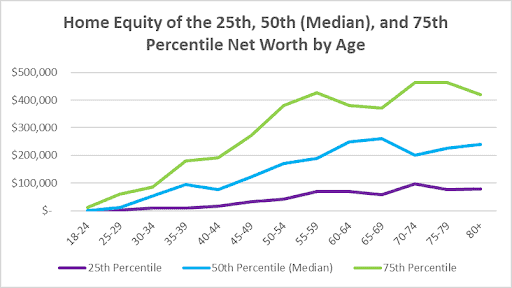
The
chart of net worth in America is a shifting landscape, one that reflects both the country’s economic resilience and its deepening divides. While headlines frequently highlight billionaires and stock market gains, the reality of household wealth is far more nuanced. The median net worth—where half of Americans sit above, half below—has stagnated for decades, while the top 1% amass fortunes that dwarf the collective savings of entire cities. This disconnect isn’t accidental; it’s the result of policy, demographics, and the persistent myth that wealth trickles down evenly.
What the
chart of net worth in America actually shows is a system where access to capital, education, and generational advantage determine who thrives. The Federal Reserve’s triennial Survey of Consumer Finances paints the clearest picture: in 2022, the top 10% held 70% of all wealth, while the bottom 50% shared just 2.6%. Yet public perception lags behind the data. Many still believe homeownership alone builds generational wealth—or that student debt is the sole barrier to prosperity. The truth is more complex, and the chart of net worth in America tells a story of structural inequality masquerading as individual failure.
Common Myths About the Chart of Net Worth in America

The
chart of net worth in America is often reduced to simplistic narratives that obscure its true dynamics. One persistent myth is that wealth is evenly distributed among those who work hard. The reality is that net worth accumulation is heavily front-loaded: inheritance, early-career job placement, and unearned financial gifts play outsized roles. A 2023 study by the Urban Institute found that 40% of wealth transfers—the largest source of intergenerational wealth—come not from wills but from gifts, trusts, and in-kind support, often bypassing those without family networks.
Another misconception is that the
chart of net worth in America is static, a snapshot that changes little year to year. In truth, it’s volatile. The 2008 financial crisis wiped out trillions in household wealth overnight, but recovery was uneven: the top 1% regained losses within three years, while the bottom 90% took a decade. More recently, the COVID-19 pandemic and subsequent stimulus packages temporarily inflated median net worth—but only for those who owned assets. Renters, gig workers, and minorities saw little lasting benefit, reinforcing the chart’s racial and regional disparities.
Finally, many assume that rising home values and stock market performance have lifted all boats. Yet the
chart of net worth in America reveals a stark divide: homeownership rates among Black households remain 20 percentage points lower than white households, and stock ownership is concentrated among the wealthy. The S&P 500’s gains in 2023 added $10 trillion to household wealth, but 90% of that went to the top 10%.
####
Myth 1: Homeownership Alone Creates Generational Wealth
The idea that buying a home is a surefire path to wealth ignores the chart of net worth in America’s cold math. While homeowners do accumulate equity over time, the benefits are highly dependent on location, timing, and initial down payment. A 2022 Brookings Institution report found that only 30% of homeowners see their property as a primary wealth-building tool—most use it as a stable housing solution. Meanwhile, those who inherit homes or buy in high-appreciation markets (like coastal cities) see outsized returns, while first-time buyers in stagnant markets often struggle to build equity.
The
chart of net worth in America also exposes racial disparities in homeownership. Black families have one-tenth the wealth of white families, partly because redlining and discriminatory lending practices limited their access to mortgages for generations. Even today, Black homebuyers face higher interest rates and stricter approval processes. Without policy interventions—like down payment assistance or tax reforms—the chart of net worth in America will continue to reflect these historical inequities.
####
Myth 2: Student Debt Is the Main Barrier to Wealth
Student loans are often framed as the villain of the chart of net worth in America, but the data tells a different story. While $1.7 trillion in student debt is a crisis, its impact on wealth varies wildly. A 2023 Federal Reserve analysis found that borrowers with advanced degrees (who earn higher salaries) often see debt as an investment, not a burden. The real drag comes from default rates among community college and for-profit school graduates, who enter low-paying fields with little return on their loans.
The bigger issue?
Student debt interacts with other wealth gaps. A 2022 Pew Research study showed that Black borrowers with bachelor’s degrees have twice the debt of their white peers, partly due to attending less-funded institutions. Meanwhile, wealthier families can absorb debt through parental gifts or home equity loans. The chart of net worth in America doesn’t just show who has debt—it shows who can leverage debt to build assets, and who gets trapped in a cycle of servicing it.
####
Myth 3: The Middle Class Is Shrinking Because People Are Lazy
Blame for stagnant median net worth in the chart of net worth in America often falls on individual behavior—wages, spending habits, or lack of ambition. Yet the data points to structural forces: wage stagnation, rising healthcare costs, and the erosion of union power. Since the 1970s, real wages for the bottom 60% of earners have grown by just $2.50 per hour, adjusted for inflation. Meanwhile, corporate profits and CEO pay have soared.
The
chart of net worth in America also reflects how automation and globalization have reshaped labor markets. Jobs that once provided middle-class stability—manufacturing, retail, even mid-level office work—have been outsourced or replaced by AI. A 2023 McKinsey report estimated that 30% of U.S. work hours could be automated by 2030, disproportionately affecting lower-wage workers. Without policies like wage subsidies, universal pre-K, or wealth redistribution, the chart of net worth in America will continue to concentrate wealth at the top.
What Holds Up to Scrutiny
The chart of net worth in America isn’t just numbers—it’s a diagnostic tool for economic health. When examined closely, three truths emerge:
1. Wealth is not the same as income. The top 1% earn a disproportionate share of income, but the top 0.1% hold 20% of all wealth, thanks to assets like real estate, stocks, and businesses.
2. Demographics drive disparities. The median net worth of a 65-year-old white household is $250,000, while a 65-year-old Black household sits at $36,000. Age and race are stronger predictors of wealth than education or income.
3. Policy shapes the chart. Tax cuts for the wealthy, deregulation of financial markets, and underfunded public services all tilt the chart of net worth in America upward for the rich.
>
"Wealth inequality isn’t an accident—it’s the result of rules that favor those who already have power. The chart of net worth in America is a ledger of those rules." — Darrick Hamilton, economist and professor at The New School
| Common Belief | What the Evidence Says |
|----------------------------------|-------------------------------------------------------------------------------------------|
| "The middle class is disappearing." | The middle quintile’s share of wealth has fallen from 30% (1989) to 20% (2022), but the top 1% now holds 35%. |
| "Homeownership evens the playing field." | White households have 10x the wealth of Black households, partly due to inherited homes and discriminatory lending. |
| "Student debt is the biggest wealth killer." | Medical debt now exceeds student debt in total, and 40% of borrowers are over 40—many with children to support. |
Why the Confusion Persists

The chart of net worth in America is deliberately opaque. Wealth data is collected irregularly (every three years by the Fed), and media coverage often focuses on market highs or celebrity fortunes rather than distribution. Politicians avoid direct discussions about wealth taxes or inheritance reform, instead framing inequality as a "skills gap" or "cultural issue." Even economists debate whether to measure liquid assets (like stocks) or total net worth (including homes and pensions), obscuring the full picture.
Another factor? The psychology of wealth. Americans overestimate their own financial standing—70% believe they’re in the top 20% of earners—while underestimating systemic barriers. The chart of net worth in America reveals that only 12% of households are in the top 20%, yet most people assume they’re closer to that threshold. This disconnect fuels policies that benefit the wealthy while leaving the rest to navigate a rigged system.
Conclusion
The chart of net worth in America isn’t just a statistic—it’s a report card on economic fairness. It shows that wealth isn’t earned equally, inherited fairly, or taxed justly. The myths surrounding it—homeownership as a panacea, student debt as the sole villain, or laziness as the cause of stagnation—distract from the real drivers: policy, power, and historical exclusion. Without addressing these, the chart of net worth in America will only deepen its divides.
The good news? The data is clear, and the tools to reshape it exist. Progressive taxation, wealth audits, and targeted investments in education and housing could rewrite the chart of net worth in America—but only if the public demands it. The question isn’t whether the numbers will change; it’s who will benefit when they do.
Comprehensive FAQs
#### Q: How often is the chart of net worth in America updated?
The Federal Reserve’s Survey of Consumer Finances—the gold standard for net worth data—is released every three years (most recently in 2022). The Census Bureau also publishes annual estimates, but these focus on income, not assets. For real-time snapshots, economists rely on stock market trends, home price indices, and pension fund reports, but these are incomplete without the Fed’s full dataset.
#### Q: Does the chart of net worth in America include debt?
Yes. Net worth = total assets (home, stocks, cash) minus liabilities (mortgages, loans, credit cards). A household with $500,000 in home equity but $300,000 in debt has a $200,000 net worth, not $500,000. This is why high-debt professionals (like doctors or lawyers) can appear wealthier on paper than retirees with paid-off homes.
#### Q: Why do the top 10% hold so much more wealth than the rest?
The chart of net worth in America reflects compound advantage: the wealthy invest in assets that generate passive income (stocks, real estate, businesses), while the middle class often prioritizes liquidity (savings, emergency funds). A 2023 study by the Institute for Policy Studies found that the top 0.1% own 35% of all privately held corporate equity, meaning their wealth grows faster than wages or salaries.
#### Q: How does race affect the chart of net worth in America?
Racial wealth gaps are structural. A white family’s median net worth is $188,200, while a Black family’s is $24,100—a ratio that hasn’t budged since the 1980s. Factors include:
- Redlining (denying mortgages to Black neighborhoods).
- Wage gaps (Black workers earn 22% less than white workers, adjusted for education).
- Inheritance disparities (Black families receive $10,000 less per year in gifts/bequests).
#### Q: Can the chart of net worth in America be fixed?
Yes, but it requires policy changes, not individual effort. Proposals include:
- Wealth taxes (e.g., Elizabeth Warren’s 2% tax on fortunes over $50M).
- Baby bonds (government-funded accounts for children from low-income families).
- Closing the racial wealth gap via reparations or targeted housing policies.
Historically, wealth redistribution (like the New Deal) has worked—but only when political will aligns with economic necessity.
#### Q: What’s the biggest misconception about the chart of net worth in America?
That it’s merit-based. The chart of net worth in America shows that 60% of wealth comes from inheritance, gifts, or asset appreciation—not salaries. A child born to parents in the top 1% has a 92% chance of staying there; a child born in the bottom 20% has just a 7% chance of escaping. This isn’t about effort—it’s about starting position.
#### Q: How does the chart of net worth in America compare to other countries?
The U.S. has one of the most unequal wealth distributions among developed nations. While Sweden’s top 10% hold 55% of wealth, America’s top 10% hold 70%. The Gini coefficient (a measure of inequality) for U.S. wealth is 0.89—higher than South Africa’s (0.70). Countries with stronger social safety nets (like Denmark or Germany) see less extreme disparities in the chart of net worth.
#### Q: Where can I find the most accurate chart of net worth in America?
For official data, use:
- Federal Reserve’s SCF (
federalreserve.gov).
- Census Bureau’s Wealth Data (
census.gov).
- Pew Research Center’s reports (
pewresearch.org).
Avoid media headlines or social media claims—they often cherry-pick data to fit narratives. Always cross-reference with primary sources.