Where It All Began
The concept of retirement as a financial milestone didn’t exist for most Americans until the 20th century. Before the New Deal, the idea of saving for decades after leaving work was foreign. Pensions were rare, and Social Security—when it launched in 1935—was designed as a safety net, not a lifeline. Early "average retirement net worth us" data from the 1950s and 60s showed figures that today would seem laughably modest: a median household retirement account balance of around $5,000 in 1962, adjusted for inflation. But back then, a single income, a defined-benefit pension, and a modest home often sufficed. The system assumed stability.
That stability began cracking in the 1980s. The shift from defined-benefit to defined-contribution plans—like 401(k)s—meant workers now bore the risk of market performance. Employers stopped guaranteeing payouts; instead, they offered matching contributions, but only if employees contributed first. The "average retirement net worth us" trajectory, which had been flat for decades, started its first steep climb. By 1992, the median retirement account balance had doubled to $20,000, but the gap between the haves and have-nots was widening. The stock market boom of the late 1990s hid the truth: most Americans weren’t saving enough, and those who did were betting everything on volatile assets.
#### The Early Signs
The first red flags appeared in the early 2000s. A 2004 Employee Benefit Research Institute study found that 44% of Americans had less than $10,000 saved for retirement. That same year, the median "average retirement net worth us" for near-retirees (ages 55–64) was $120,000—enough to cover maybe six months of expenses if invested conservatively. But here’s the catch: that number included home equity, which many assumed they’d tap into. The problem? Home values were about to crash. The housing bubble’s collapse in 2008 didn’t just wipe out equity; it shattered the illusion that real estate was a safe retirement hedge. The "average retirement net worth us" for households headed by someone 65 or older plunged by 28% between 2007 and 2010, according to the Federal Reserve. For those under 65, the drop was even steeper. The lesson? Retirement savings weren’t just about 401(k)s—they were about resilience. And most Americans weren’t prepared.The Turning Point
The moment "average retirement net worth us" became a national conversation was 2016. That’s when the Federal Reserve’s Survey of Consumer Finances revealed something jarring: the median retirement account balance for all working-age households was $25,000. For those nearing retirement (55–64), it was $163,577. The median. Not the average. The average was skewed higher by a small number of ultra-wealthy retirees, but the median told the real story: most Americans were woefully underprepared.
What changed? Three things. First, the rise of robo-advisors and fintech made saving easier—but also more confusing. Apps like Betterment and Acorns lowered the barrier to entry, but they didn’t solve the fundamental issue: most people still didn’t know how much they needed. Second, the gig economy and decline of traditional pensions left more workers without employer-sponsored plans. By 2017, 55% of U.S. workers lacked access to a retirement plan through their job. Third, longevity risk became undeniable. People were living longer, but their savings weren’t keeping pace. The "average retirement net worth us" gap wasn’t just about money—it was about time.
"Retirement isn’t a finish line; it’s a marathon you didn’t sign up for." — Aria Rafal, founder of Savvy Retirees, 2019The turning point wasn’t just statistical. It was psychological. For the first time, "average retirement net worth us" wasn’t just a dry economic metric—it was a measure of collective anxiety. Millennials, watching their parents struggle, started side hustles, delayed marriages, and moved back in with parents. Gen Xers, sandwiched between aging parents and their own retirement needs, stretched Social Security benefits like elastic. The numbers stopped being abstract. They became personal.

The Build-Up, Year by Year
| Period | What Happened / What Changed |
|--------------------------|------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------------|
| 2010–2014 | The "average retirement net worth us" recovery stalled. The stock market rebounded, but wages didn’t. The median balance for near-retirees grew by just 1.2% annually, while healthcare costs rose 3.9%. Student loan debt surged, diverting savings. |
| 2015–2018 | Fintech disruption hit. Apps like Ellevest and SoFi Invest targeted women and younger investors, but adoption was uneven. The median "average retirement net worth us" for households 35–44 rose to $45,000, but 30% had nothing saved. |
| 2019–2021 | The pandemic exposed the fragility of "average retirement net worth us" figures. 40% of Americans reported dipping into retirement savings in 2020. The CARES Act allowed penalty-free withdrawals, but many never repaid the loans. |
| 2022–2024 | Inflation eroded purchasing power. The median retirement account balance for 55–64-year-olds hit $185,000—but home values and healthcare costs outpaced growth. The "average retirement net worth us" gap widened along racial lines: Black households had $90,000 less than white peers. |
#### Lessons From the Journey
- Home equity isn’t a retirement plan. The 2008 crash proved that relying on real estate for income is risky. Yet, 60% of retirees still count on it. - Market timing is a myth. The "average retirement net worth us" for those who retired in 2000 (pre-dot-com crash) is 20% lower than those who retired in 2010—despite both groups having similar savings. - Social Security isn’t enough. The average monthly benefit ($1,800) covers 25% of pre-retirement income—far below the 70% replacement rate financial planners recommend. - Debt follows you into retirement. 30% of retirees carry student loans or credit card debt, dragging down their "average retirement net worth us" by $50,000+.Where Things Stand Today
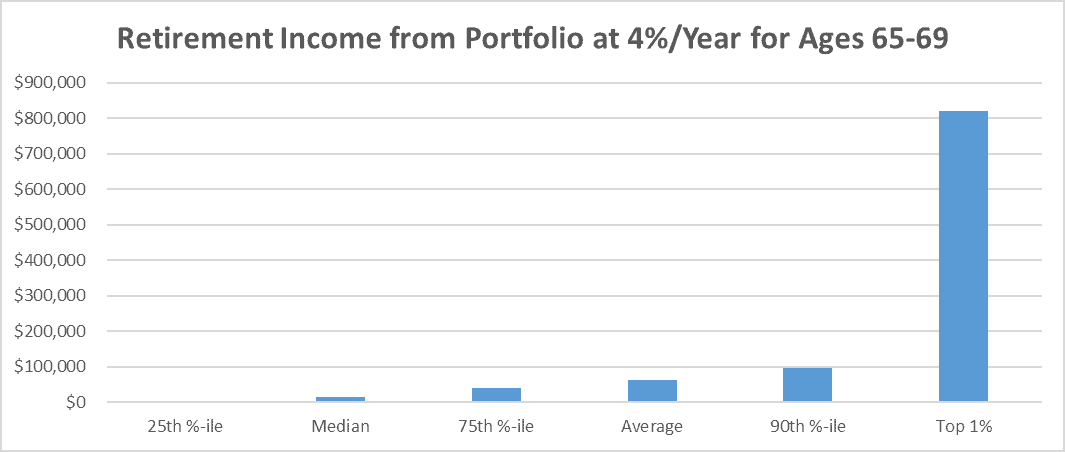
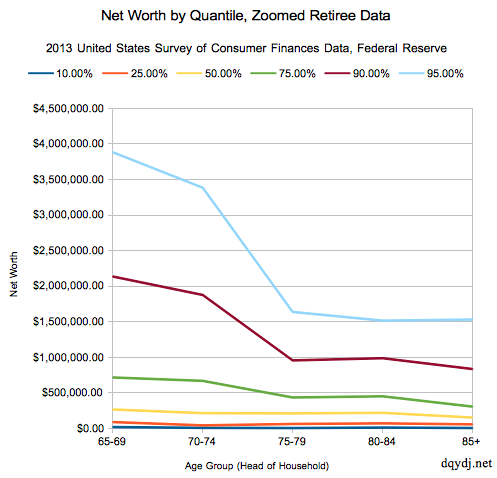
As of 2024, the "average retirement net worth us" for households headed by someone 65 or older is estimated at $305,000, according to the Federal Reserve. But that’s the median—and it’s misleading. The average (mean) is $1.2 million, inflated by the ultra-wealthy. For the bottom 50% of retirees, the number is closer to $120,000. That’s enough to generate $500–$700/month in income if invested conservatively—far below the $4,000/month needed to maintain a middle-class lifestyle in most states.
The bigger story isn’t the numbers themselves, but the systemic failures they reveal. 40% of retirees rely on defined-benefit pensions, but those plans are disappearing. 25% have no retirement savings at all. And the "average retirement net worth us" divide is racial: White households have 8x more in retirement accounts than Black households, and 6x more than Hispanic households. The problem isn’t just individual behavior—it’s decades of policy choices, from 401(k) fees that eat into savings to Social Security’s solvency crisis.
Conclusion
The "average retirement net worth us" isn’t just a statistic—it’s a report card on America’s economic health. And the grades are failing. The system that once promised security now demands self-reliance in an era of uncertainty. The good news? Awareness is growing. More employers offer auto-enrollment in 401(k)s, and state-run retirement plans (like CalSavers) are filling gaps. But the bad news? Time is running out. Those in their 50s today have 15 years to catch up—and the math doesn’t add up.
The real question isn’t how to fix the "average retirement net worth us"—it’s whether America will finally treat retirement as a public good, not just a personal responsibility. The numbers tell us one thing: we’re not ready. The question is whether we’ll act before it’s too late.
Comprehensive FAQs
#### Q: What’s the difference between the median and average "average retirement net worth us"?
The median (middle value) is $305,000 for retirees 65+, while the average (mean) is $1.2 million. The gap exists because a small number of ultra-wealthy retirees skew the average upward. The median gives a truer picture of what most people have.
####Q: Can I retire comfortably with the "average retirement net worth us"?
No. The "average retirement net worth us" of $305,000 generates $1,500–$2,000/month in income (assuming a 4% withdrawal rate). Most financial planners recommend $4,000–$6,000/month for a comfortable retirement in most regions. You’d need $1 million+ to cover healthcare, housing, and living expenses.
####Q: How does inflation affect the "average retirement net worth us"?
Inflation erodes purchasing power. Since 2000, the "average retirement net worth us" has grown 50%, but healthcare costs have risen 120%. A $200,000 nest egg in 2000 would buy far less today due to higher housing, medical, and grocery expenses. Adjusting for inflation, the real value of retirement savings has stagnated for decades.
####Q: Are there racial disparities in the "average retirement net worth us"?
Yes. White retirees have 8x more in retirement accounts than Black retirees and 6x more than Hispanic retirees. The gap stems from historical wealth disparities, wage gaps, and limited access to employer-sponsored plans. Closing this divide requires policy changes, not just individual savings efforts.
####Q: What’s the biggest threat to the "average retirement net worth us" today?
Three risks stand out: 1) Market volatility—a 20% drop in stocks could slash a retiree’s portfolio by $60,000+. 2) Longevity risk—living to 90+ means 30+ years of withdrawals. 3) Policy uncertainty—Social Security solvency and healthcare costs could force unexpected cuts. The "average retirement net worth us" is only as strong as the system protecting it.
