
7 Things Worth Knowing About What Net Worth Defines Wealthy in the US Today
The debate over financial thresholds isn’t just academic—it shapes policy, perception, and personal ambition. Here’s what the data and cultural shifts reveal.1. The $1 Million Line Is Obsolete in Most of America
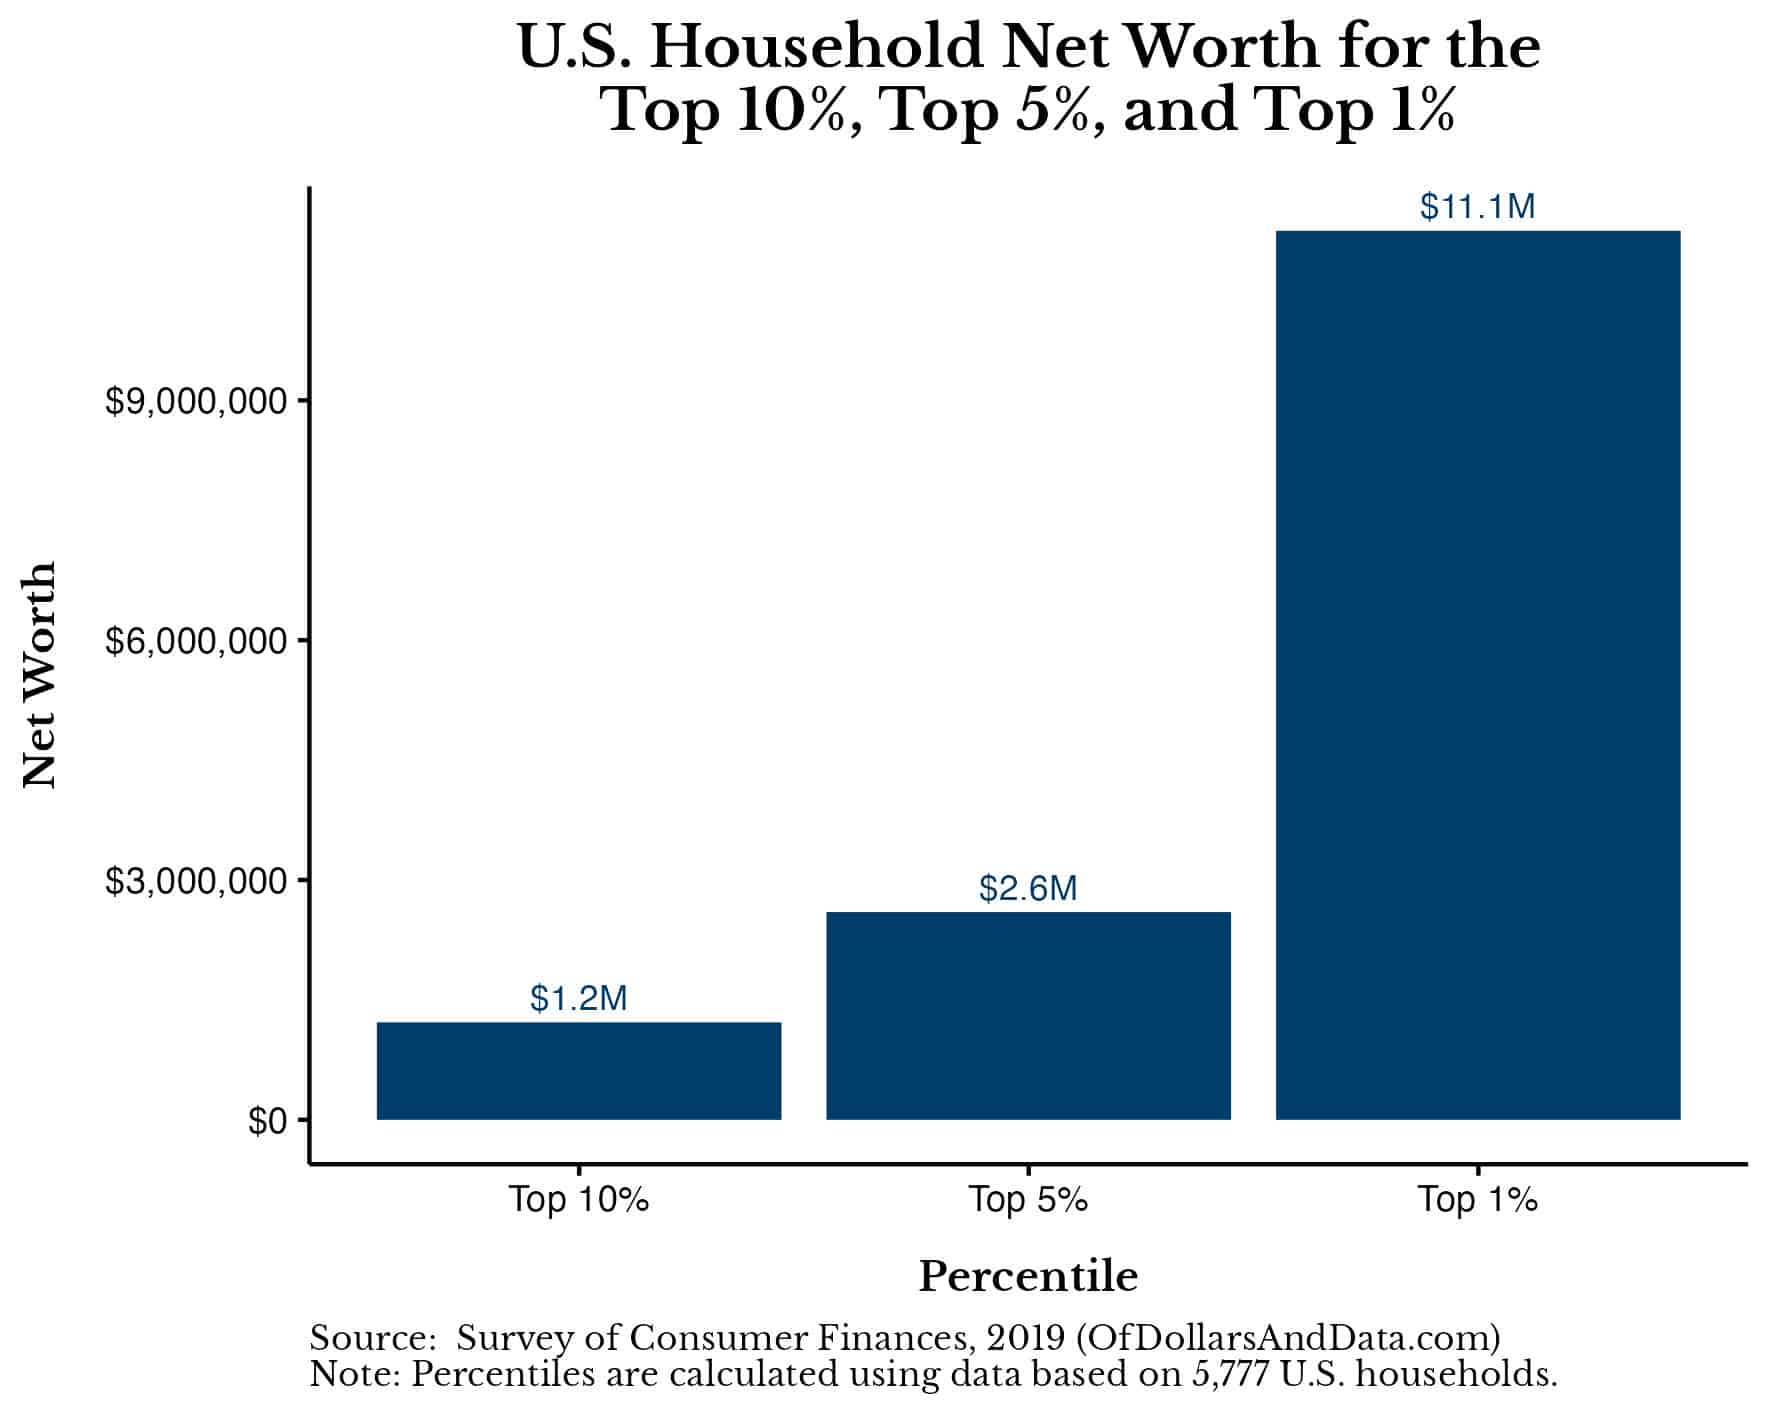
A net worth of $1 million used to be the gold standard for wealth, but today it’s more of a regional speed bump. In San Francisco or New York, that sum might cover a down payment on a two-bedroom condo—if you’re lucky. Meanwhile, in Des Moines or Memphis, $1 million could mean generational security, a second home, and early retirement. The Federal Reserve’s 2022 Survey of Consumer Finances found that only 12.3% of U.S. households hit the $1 million mark, down from 14% in 2019—a drop that reflects stagnant wage growth and soaring housing costs. The real story? Wealth accumulation now depends more on geography than gross income. A teacher in Boston with $800,000 in net worth might feel precarious, while a plumber in Oklahoma with the same figure could retire tomorrow. The confusion deepens when you factor in liquid vs. illiquid assets. A $1 million portfolio in Bitcoin or private equity might feel volatile to its owner, while the same sum in a family farm or rental properties could generate passive income. The IRS’s "high net worth" label ignores this nuance, treating all wealth as fungible. Yet for most Americans, the psychological threshold of wealth—the point where financial stress lifts—hovers around $2.5 million, according to a 2023 Charles Schwab survey. That’s not just money; it’s the ability to say no to a job you hate, send kids to college without panic, and weather a recession without selling your home.2. The Ultra-Wealthy Play by Different Rules
When discussing what net worth defines wealthy in the US today, the conversation often stumbles over the $30 million club. This isn’t just wealth—it’s a tax-advantaged ecosystem. The top 0.1% of Americans (those with net worths above $30 million) hold more wealth than the bottom 90% combined, per the Institute for Policy Studies. Their assets aren’t in 401(k)s or IRAs; they’re in private jets, hedge funds, and art collections that appreciate independently of the stock market. A $50 million net worth might mean a $20 million primary residence, a $10 million yacht, and $20 million in "illiquid" assets like vineyards or racehorses—none of which show up on a standard financial disclosure. The ultra-wealthy also benefit from compound privilege. A family that’s been wealthy for three generations can pass down trusts, avoid estate taxes through dynasty planning, and invest in assets that appreciate quietly. Meanwhile, the newly minted millionaire—say, a tech founder with $10 million in stock options—faces capital gains taxes, volatility risk, and the pressure to keep growing. The net worth number alone doesn’t capture the generational inertia that keeps the ultra-rich on top. As economist Thomas Piketty argues, wealth begets wealth—and the system is rigged to reward those who already have it.3. Student Debt Is the New Wealth Killer
For younger Americans, the question of what net worth defines wealthy in the US today is often moot—because debt erases the playing field. The average Class of 2023 graduate leaves school with $38,000 in student loans, a figure that can take decades to outearn. A physician with $500,000 in medical school debt might have a $2 million net worth but still feel poor. The wealth gap between debt-free and indebted millennials is staggering: those without student loans have nearly twice the median net worth of their peers with degrees, according to the Federal Reserve. This isn’t just a personal finance issue—it’s a structural barrier to wealth accumulation. The effect is most brutal for Black and Latino borrowers, who take on more debt for the same degrees and face higher denial rates for refinancing. A 2022 Brookings Institution study found that Black families with college degrees have less wealth than White families without them. For these groups, the path to wealth isn’t just about earning more—it’s about surviving the debt trap that keeps net worth artificially suppressed. Even if a borrower hits $1 million, the psychological weight of past debt can make them feel financially insecure—a paradox that challenges the very definition of wealth.4. Homeownership Is the Great Equalizer (and Divider)
Owning a home remains the single most powerful wealth-building tool in America—but only if you’re in the right market at the right time. The median home value in the U.S. is now $416,100, up 40% since 2019. For a family with $100,000 in savings, that’s a 30-year commitment to mortgage payments, property taxes, and maintenance—with little left for investments. Yet homeowners still hold nearly 40% of all U.S. wealth, per the Urban Institute. The problem? Access isn’t equal. Black households have a homeownership rate 25 percentage points lower than White households, largely due to redlining, predatory lending, and wealth gaps passed down for generations. The homeownership paradox is stark: in some cities, a $1 million home might be a liability (think: Miami’s condo market crash of 2023), while in others (like Boise or Phoenix), it’s a ticket to generational wealth. The net worth premium of homeownership—often cited as $200,000+—only applies if you buy at the right time and hold for decades. For renters, the dream of wealth through real estate feels like a myth. This duality forces a reckoning: Is a $1 million net worth truly wealthy if it’s all tied up in a single asset that could collapse?5. The Gig Economy’s Invisible Wealth
The rise of freelance work, side hustles, and digital assets has created a new class of "quiet millionaires"—people who never show up on traditional wealth rankings. A Uber driver in Houston might have $1.2 million in net worth from cash savings, a paid-off home, and a rental property, yet their income reports as $40,000 annually. Meanwhile, a corporate lawyer with the same net worth would be celebrated as affluent. This disconnect between income and wealth is reshaping what what net worth defines wealthy in the US today means for the gig economy. Platforms like Fiverr, Etsy, and YouTube have turned skills into illiquid wealth. A top-selling Etsy shop might generate $500,000 in annual revenue, but its net worth is hard to quantify—especially if the owner reinvests profits rather than take a salary. The IRS’s wealth metrics don’t account for digital equity, meaning these entrepreneurs often fall through the cracks of official statistics. For them, wealth isn’t about a single net worth number—it’s about cash flow flexibility. A $500,000 net worth in gig assets might feel richer than a $1 million portfolio in volatile stocks.6. The Retirement Reckoning
The traditional retirement benchmark—$1 million in savings—was designed for an era of defined-benefit pensions and low healthcare costs. Today, $1 million won’t last 20 years for most retirees, thanks to inflation, rising medical expenses, and the collapse of Social Security solvency projections. Fidelity now recommends $1.5 million for a comfortable retirement, while some financial planners suggest $2.5 million for those in high-cost areas. The disconnect? Most Americans aren’t saving enough to hit even the old target. The median retirement account balance for near-retirees is $65,000, per the Economic Policy Institute. This forces a brutal question: If $1 million isn’t enough to retire, what net worth does define wealthy in the US today? The answer depends on lifestyle. A couple in Florida might live comfortably on $1.2 million, while one in San Francisco could deplete $2 million in a decade. The psychological threshold—the point where money stops causing stress—varies wildly. For some, it’s $3 million; for others, it’s $10 million. What’s clear is that retirement wealth is no longer a fixed number but a moving target tied to healthcare, longevity, and geographic luck.7. The Cultural Shift: Wealth as Status vs. Security
There’s a growing divide between how wealth is perceived and how it functions. For the 1%, wealth is about legacy, influence, and tax avoidance. For the newly affluent (think: crypto millionaires, real estate flippers), it’s about flexibility and freedom. And for the aspirational middle class, wealth is still tied to homeownership and college funds—even if those paths are closing. This cultural split explains why $1 million can feel like poverty in one context and opulence in another. Consider the luxury real estate market. A $5 million penthouse in Miami might be a speculative asset for its owner, while a $2 million townhouse in Chicago could be a generational investment. The symbolic value of wealth has detached from its functional value. A Tesla in the driveway signals status, but a paid-off mortgage signals true financial independence. The what net worth defines wealthy in the US today debate is no longer just about numbers—it’s about what those numbers can buy you in a world where money’s rules keep changing.
How These Facts Connect
The data on what net worth defines wealthy in the US today tells two stories: one about financial thresholds, and another about who gets to set them. The $1 million marker is a relic of a pre-2008 economy, where homeownership was the primary wealth vehicle and debt was manageable. Today, that number means little in coastal cities, while in others, it’s a ticket to early retirement. The ultra-wealthy operate in a parallel financial system, where trusts, private equity, and illiquid assets keep their true net worth hidden from public metrics. Meanwhile, the newly minted wealthy—whether through gig work, real estate, or tech—face liquidity risks and tax burdens that the old money class doesn’t. The most revealing insight? Wealth is no longer just about money—it’s about access. Access to education (without debt), access to homeownership (without discrimination), access to investment opportunities (without insider knowledge). The net worth number is just the tip of the iceberg. Beneath it lies generational advantage, systemic barriers, and cultural capital—factors that traditional wealth metrics ignore. The $1 million line is meaningless if you’re trapped in student debt. A $10 million portfolio is irrelevant if you can’t convert it to cash during a crisis. What defines wealth today isn’t a single number—it’s who you are, where you live, and how the system treats you.| Metric | Old Definition (Pre-2010) | New Reality (2024) | Who It Favors |
|---|---|---|---|
| $1 Million Net Worth | Top 10% of households | Regional speed bump (varies 300% by city) | Homeowners in low-cost areas |
| Ultra-Wealthy ($30M+) | 0.1% of population | Controls 20%+ of national wealth | Multi-generational families |
| Student Debt Impact | Minor wealth drag | Erases net worth gains for decades | White, college-educated borrowers |
| Homeownership Premium | $200K+ wealth boost | Depends on market timing and race | White suburban families |
| Retirement Target | $1M for comfort | $1.5M–$2.5M (or more) for security | Those with pensions or low healthcare costs |
Conclusion
The search for what net worth defines wealthy in the US today leads to a disorienting conclusion: there is no single answer. The $1 million benchmark is a zombie statistic, clinging to life despite being out of date. What matters now is context—context of geography, debt, asset liquidity, and the hidden costs of living. The ultra-rich play by one set of rules, the aspirational middle class by another, and the gig economy by a third. Meanwhile, systemic barriers—student debt, racial wealth gaps, and housing discrimination—ensure that the definition of wealth is as much about who you are as how much you have. The most important takeaway? Wealth is no longer just a number. It’s a combination of security, mobility, and opportunity—and those things are in shorter supply than ever. The next generation will either redesign the system or accept that the old definitions no longer apply. Either way, the question of what net worth defines wealthy in the US today won’t just be about money. It’ll be about who gets to call themselves wealthy—and why.Comprehensive FAQs
Q: Is $1 million still considered wealthy in 2024?
A: Not in most of America. A $1 million net worth in San Francisco or New York might cover a down payment on a modest home, while in Dallas or Indianapolis, it could fund early retirement. The Federal Reserve’s data shows only 12.3% of U.S. households hit this mark, down from 14% in 2019. For true financial security—especially in high-cost areas—$2.5 million to $3 million is now the psychological threshold where stress lifts, per Charles Schwab surveys. However, liquid vs. illiquid assets complicate this: a $1 million portfolio in Bitcoin may feel riskier than the same sum in rental properties.
Q: How does student debt affect wealth accumulation?
A: Student debt erases decades of potential wealth growth. The average borrower’s net worth is nearly 50% lower than that of non-borrowers, per the Federal Reserve. For Black and Latino graduates, the gap is even wider—their net worth is often negative in their 30s due to loan burdens. Even high-earning professions (like medicine or law) can see $500,000+ in debt cancel out early wealth-building. The result? A $1 million net worth for a physician might feel like poverty if most of it is tied up in loans, while a debt-free peer with $600,000 could retire comfortably.
Q: Can you be wealthy without a high net worth?
A: Yes—but it depends on cash flow and asset liquidity. A gig worker with $500,000 in savings and no debt might live richer than a corporate employee with $1.5 million in a volatile stock portfolio. Similarly, homeowners with equity can access wealth without a high net worth number. The key is financial flexibility: the ability to cover expenses, invest, and weather crises without selling assets. For some, $300,000 in liquid savings + a paid-off home is wealthier than $1 million in illiquid investments.
Q: How does geography change what defines wealth?
A: Dramatically. A $1 million net worth in Raleigh, North Carolina, could mean generational security, while the same sum in Los Angeles might only cover a condo down payment. The cost of living varies by 300% across U.S. metros, per MIT’s Living Wage Calculator. In Austin or Miami, a $2 million net worth might feel middle-class due to housing costs, while in Cleveland or Pittsburgh, it’s upper-tier. Even within states, rural vs. urban divides matter: a farmer with $1 million in land is wealthy in ways a city dweller with the same sum in stocks isn’t. Wealth thresholds are now zip-code-dependent.
Q: What’s the future of wealth definitions in America?
A: The $1 million benchmark is dying, replaced by dynamic, context-dependent metrics. Future definitions will likely include:
- Debt-adjusted net worth (accounting for student loans, mortgages, and medical debt)
- Liquidity ratios (how easily assets can be converted to cash)
- Geographic cost-of-living multipliers (e.g., $1M in SF ≠ $1M in SF)
- Generational transferability (can wealth be passed down without tax erosion?)
- Non-financial security (healthcare access, education funding, retirement longevity)
