The question of what constitutes
upper-class status in America has never been static. A generation ago, a net worth of $1 million might have placed someone firmly in the top tier. Today, that same figure barely registers above the middle-class ceiling in many coastal cities. The net worth to be upper class in America isn’t just about dollars—it’s about access, legacy, and the invisible barriers that separate financial comfort from generational power. The numbers shift with inflation, regional cost of living, and the quiet erosion of traditional wealth markers by new forms of capital: private equity stakes, digital assets, or even the unquantifiable currency of social capital in elite networks.
What’s often overlooked is that upper-class thresholds aren’t just about raw figures. They’re about
liquidity horizons—the ability to withdraw $5 million without blinking, or to leverage a single property transaction to fund a child’s Ivy League education and trust fund. The net worth to be upper class in America today demands more than assets; it requires structural wealth: the kind that doesn’t just sit in a brokerage account but flows through trusts, family offices, and the unspoken rules of old-money circles. This is the difference between a tech CEO with a paper fortune and a scion of a New England dynasty whose wealth has been quietly compounding for centuries.
The data tells a story of quiet stratification. A 2023 Federal Reserve study revealed that the top 1% of American households hold
nearly 35% of all privately held wealth, while the bottom 50% collectively own just 2.6%. The net worth to be upper class in America isn’t a fixed line—it’s a moving target, pulled upward by the concentration of wealth in fewer hands. For context, the median net worth of the top 0.1% (those with over $22 million) dwarfs the median of the top 1% by a factor of 10. The elite aren’t just richer; they operate in a different economic ecosystem, where wealth begets wealth through tax advantages, inheritance, and the ability to deploy capital at scale.
The Complete Overview of the Net Worth to Be Upper Class in America
The
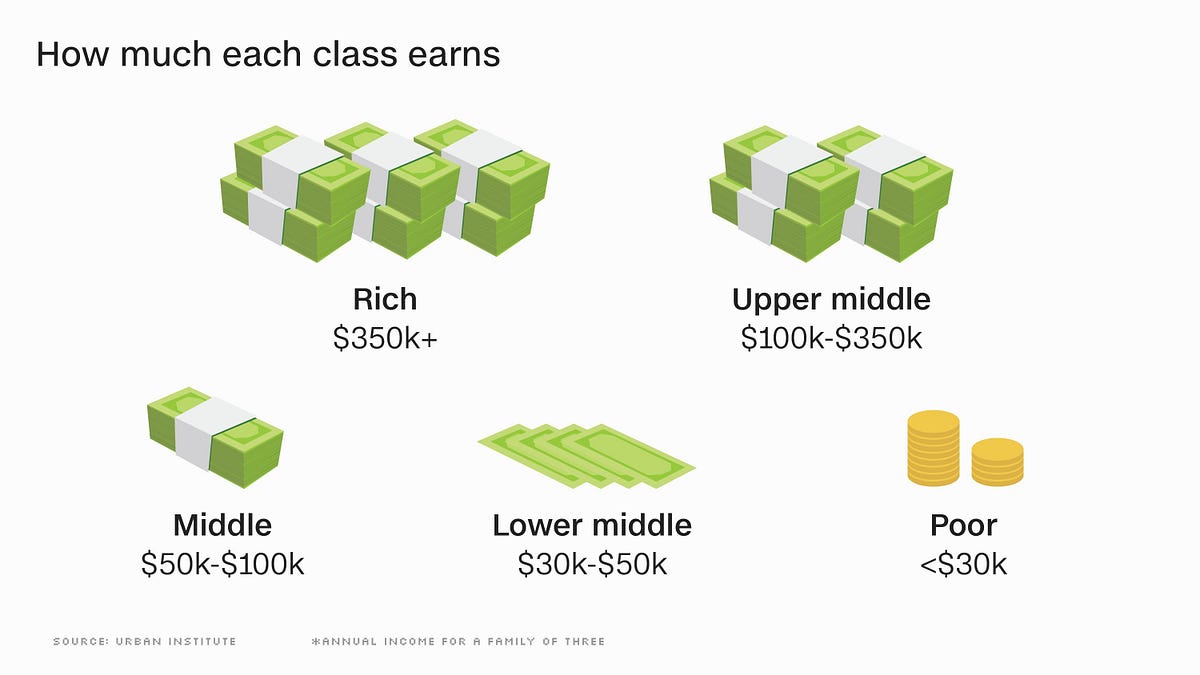
net worth to be upper class in America isn’t a single number but a spectrum defined by geography, industry, and generational wealth. In 2024, financial analysts and sociologists generally agree that $2 million to $5 million in liquid and illiquid assets marks the lower boundary of upper-class status in most U.S. regions. However, this figure balloons in high-cost areas like New York City or San Francisco, where the net worth to be upper class in America may require closer to $5 million to $10 million to maintain the lifestyle associated with elite circles. The disparity isn’t just about dollars—it’s about financial autonomy. Someone with $3 million in a single property in Ohio might live comfortably, but in Manhattan, that same sum could leave them vulnerable to market shocks or social exclusion from the city’s old-money enclaves.
The upper class isn’t monolithic. There’s the
new money—self-made fortunes from tech, finance, or entertainment—that often lacks the cultural capital of old money. Then there’s the legacy wealth, where family trusts, inherited real estate, and generational networks provide a buffer against economic volatility. The net worth to be upper class in America for a trust-fund heir in Boston might differ significantly from that of a Silicon Valley entrepreneur, even if their bank balances align. The former moves in circles where wealth is assumed; the latter must constantly prove their standing. This distinction explains why some individuals with $10 million in assets still feel like outsiders in elite social circles, while others with half that sum are welcomed with open doors.
Historical Background and Evolution
The concept of upper-class wealth in America has been reshaped by three seismic forces: industrialization, globalization, and the rise of financialization. In the early 20th century, the
net worth to be upper class in America was tied to industrial barons—men like Rockefeller or Carnegie, whose fortunes were built on oil, steel, and railroads. A net worth of $5 million to $10 million (adjusted for inflation) was enough to secure a place among the Gilded Age elite, where wealth was displayed through mansions, art collections, and political influence. The Robber Barons’ era was one of visible wealth—brass plaques, yachts, and country estates served as public declarations of status.
By the mid-20th century, the
net worth to be upper class in America had fragmented. The post-WWII boom democratized affluence to a degree, but the true upper class remained concentrated in the 1%. The Kennedy and Rockefeller dynasties, for example, maintained fortunes in the hundreds of millions through diversified holdings in media, real estate, and finance. Meanwhile, the rise of Wall Street in the 1980s and 1990s introduced a new breed of ultra-wealthy: hedge fund managers, private equity kings, and tech moguls. The net worth to be upper class in America now included intangible assets—stock options, carried interest, and the ability to deploy capital in ways that traditional wealth couldn’t. Today, the upper class is less about owning factories and more about controlling the systems that generate wealth: algorithms, venture capital, and global supply chains.
Core Mechanisms: How It Works
The
net worth to be upper class in America isn’t just about accumulation—it’s about structural advantage. Take liquidity, for instance. A family with $5 million in cash equivalents can write checks without hesitation, while someone with the same net worth tied up in illiquid assets (like a single business or real estate) may face liquidity crises. Upper-class wealth is also about tax efficiency. The ultra-rich deploy strategies like dynasty trusts, offshore entities, and charitable lead annuity trusts to shield assets from erosion. A study by the Urban Institute found that the top 1% pay an effective tax rate of just 20% on their capital gains, compared to nearly 30% for middle-income earners. This isn’t just about more money—it’s about keeping more of it.
Social capital plays an equally critical role. The
net worth to be upper class in America is amplified when wealth is paired with access to elite networks—private schools, exclusive clubs, and old-boy networks that open doors to investment opportunities, political connections, and social validation. A Harvard Business School alum with $3 million might struggle to enter certain circles, while a Yale graduate with the same net worth—born into a family with a century of wealth—could waltz in. This isn’t just about money; it’s about cultural fit. The upper class isn’t just a financial tier; it’s a closed system where membership is as much about lineage and behavior as it is about balance sheets.
Key Benefits and Crucial Impact
The privileges of the upper class aren’t just financial—they’re existential. The net worth to be upper class in America grants a level of optionality that the middle class can only dream of. Need to relocate? A private jet or first-class ticket makes it trivial. Facing a health crisis? The best doctors, experimental treatments, and concierge medicine become accessible. The upper class operates in a world where problems are solved with capital, not time or effort. This isn’t hyperbole; it’s observable in the way elite families handle everything from college admissions (where donations to universities can buy influence) to legal troubles (where high-powered attorneys and political connections can mitigate fallout).
The psychological impact is equally profound. Upper-class individuals often report lower stress levels despite their wealth, not because money eliminates problems, but because it reduces perceived risk. A family with $10 million doesn’t fear a stock market dip the way a middle-class family might. They know they can ride out volatility. This financial buffer extends to legacy planning—the ability to ensure children inherit not just money, but social standing. The net worth to be upper class in America isn’t just a number; it’s a generational insurance policy.
>
"Wealth isn’t just about what you have in the bank—it’s about what you can do with it without anyone noticing." — A former Goldman Sachs partner, speaking off the record about the unspoken rules of elite finance.
Major Advantages
The net worth to be upper class in America confers a suite of privileges that redefine opportunity:
- Tax Optimization: Access to top-tier accountants, offshore strategies, and legal loopholes that minimize liabilities. The ultra-rich pay effectively lower tax rates than middle-class earners.
- Exclusive Networks: Membership in private clubs, country clubs, and alumni networks that provide business and social capital unavailable to outsiders.
- Educational Advantage: The ability to secure spots at top universities through donations, legacy admissions, or direct influence over admissions officers.
- Political Leverage: Contributions to campaigns, access to policymakers, and the ability to shape regulations that benefit their portfolios.
- Lifestyle Immunity: The freedom to live without constraints—whether it’s traveling first-class, hiring personal chefs, or sending children to elite boarding schools without second-guessing.

Comparative Analysis
| Metric | Upper Class ($2M–$5M+) | Affluent Middle Class ($500K–$2M) |
|--------------------------|----------------------------------------------------|----------------------------------------------------|
| Tax Burden | Effective rates as low as 15–20% on capital gains | Rates near 30% for middle-income earners |
| Liquidity | Can deploy $1M+ without hesitation | May face liquidity constraints with large sums|
| Social Mobility | Closed networks; legacy matters more than merit | Merit-based access to opportunities |
| Risk Tolerance | Can weather market crashes without lifestyle impact | Vulnerable to downturns in retirement planning |
| Legacy Planning | Dynasty trusts, offshore entities, and generational wealth | 529 plans, Roth IRAs—limited legacy tools |
Future Trends and Innovations
The net worth to be upper class in America is evolving alongside technological and geopolitical shifts. The rise of cryptocurrency and private equity has introduced new forms of wealth that traditional metrics fail to capture. A fortune built on Bitcoin or a stake in a unicorn startup may not show up on a balance sheet but can still command elite status. Meanwhile, geographic arbitrage—where the ultra-rich relocate to low-tax states like Florida or Texas—is reshaping where wealth accumulates. The net worth to be upper class in America may soon be less about owning property in Manhattan and more about owning digital infrastructure or global real estate portfolios.
Another trend is the blurring of public and private wealth. Social media has democratized the appearance of success, but the real upper class remains insular. Private membership platforms (like The Forum or Aspen Institute retreats) are becoming the new currency of status, where networking, not net worth alone, determines access. As artificial intelligence and automation reshape labor markets, the net worth to be upper class in America may increasingly depend on owning the means of production—whether through AI startups, robotics patents, or control over data assets.
Conclusion
The net worth to be upper class in America isn’t a fixed number—it’s a dynamic threshold shaped by history, geography, and the ever-shifting rules of elite economics. What was once enough to secure a place among the Gilded Age aristocracy now feels modest in an era of multi-billionaire tech moguls and hedge fund titans. The upper class today isn’t just about money; it’s about control—control over capital, influence, and the unspoken codes that govern access. For those aspiring to join its ranks, the challenge isn’t just accumulating wealth but mastering the invisible rules that separate the merely affluent from the truly elite.
The most striking reality is that the net worth to be upper class in America has become less about the size of your bank account and more about how you deploy it. A family with $5 million in a single stock may feel rich, but one with the same sum in diversified, tax-efficient assets and social capital operates in a different league entirely. The upper class isn’t just a financial tier—it’s a cultural ecosystem, and entry requires more than a balance sheet. It requires belonging.
Comprehensive FAQs
#### Q: What’s the exact net worth threshold to be considered upper class in America?
A: There’s no single answer, but financial analysts and sociologists generally cite $2 million to $5 million as the lower bound for upper-class status in most regions. In high-cost areas like New York or San Francisco, the net worth to be upper class in America may need to exceed $5 million to $10 million to maintain elite lifestyle standards. The key differentiator isn’t just the number but liquidity, tax efficiency, and social capital.
#### Q: Does being upper class mean you’re automatically part of the 1%?
A: No. The net worth to be upper class in America often sits below the 1% threshold, which typically begins at $11 million (per Federal Reserve data). The upper class includes new money (self-made fortunes) and old money (legacy wealth), while the 1% is dominated by ultra-high-net-worth individuals with $20 million+. The upper class is a broader category—it’s about lifestyle, access, and cultural capital, not just raw wealth.
#### Q: Can you be upper class with a high income but low net worth?
A: Unlikely. While income matters, net worth is the true marker of upper-class status. A doctor earning $500,000 annually may live well but likely won’t reach the net worth to be upper class in America without significant asset accumulation. The upper class is defined by wealth accumulation over time, not just annual earnings. Exceptions exist (e.g., a CEO with stock options), but they’re rare.
#### Q: How does regional cost of living affect upper-class thresholds?
A: Dramatically. In rural areas or low-cost states, a $1 million net worth might grant upper-class status, while in San Francisco or Manhattan, the net worth to be upper class in America may require $5 million+. Real estate is the biggest variable—owning a $2 million home in Ohio doesn’t carry the same prestige (or financial security) as a $5 million penthouse in NYC. The upper class in coastal cities operates at a higher baseline.
#### Q: Is it possible to achieve upper-class status without inheriting wealth?
A: Yes, but it’s extremely difficult. Self-made upper-class individuals typically combine high-income professions (law, finance, tech) with aggressive wealth-building strategies—real estate, private equity, or entrepreneurship. However, old money provides structural advantages (networks, tax planning, legacy access) that new money must replicate. Most ultra-wealthy Americans today start with some form of inherited capital or marry into wealth, though exceptions like Elon Musk or Mark Zuckerberg prove it’s not impossible.
#### Q: What’s the biggest misconception about upper-class wealth?
A: The assumption that more money = upper class. Many upper-class individuals live frugally (by elite standards) because they prioritize liquidity and legacy over conspicuous consumption. The net worth to be upper class in America isn’t about flashy spending—it’s about financial autonomy. A billionaire who flaunts wealth may be socially ostentatious, but a family with $5 million in a trust might live modestly while maintaining generational control over their fortune.
#### Q: How does the upper class protect and grow its wealth?
A: Through tax optimization, asset diversification, and social capital. Upper-class families use dynasty trusts, private foundations, and offshore entities to shield wealth. They also leverage elite networks—private school alumni associations, country clubs, and old-money social circles—to access exclusive investment opportunities. The net worth to be upper class in America isn’t just preserved; it’s engineered to compound across generations.
#### Q: Can you lose upper-class status?
A: Absolutely. Market crashes, poor investments, or divorce can erode wealth quickly. The upper class isn’t just about accumulation—it’s about risk management. A family that over-leverages debt or fails to diversify can plummet from elite status in a single downturn. Even legacy wealth isn’t guaranteed—prodigal heirs or mismanaged trusts can dissolve fortunes in a generation.