
7 Things Worth Knowing About Who Created Instacart
The creation of Instacart wasn’t a solo endeavor. It emerged from a convergence of skills, timing, and an unshakable belief in a market others ignored. Here’s what defines the story of who created Instacart and how they did it.1. The Founders’ Diverse Backgrounds
Instacart’s trio of founders—Apoorva Mehta, Max Mullen, and Brandon Leonardo—had little in common before 2012. Mehta, the CEO, had co-founded a failed social network called Shopkick and worked at Google. Mullen, the CTO, had experience in retail tech and a Stanford MBA. Leonardo, the COO, was a Stanford dropout with a background in operations. Their varied expertise became Instacart’s strength: Mehta handled vision and fundraising; Mullen built the tech; Leonardo managed the chaotic logistics of early operations. What united them was a shared frustration with existing grocery delivery options. Mehta, in particular, had watched Shopkick struggle to monetize and saw an opportunity in a sector ripe for disruption. The founders’ lack of prior grocery industry experience became an advantage—they approached the problem with fresh eyes, unburdened by legacy retail thinking.2. The Birth of Instacart in a Palo Alto Garage
Instacart launched in August 2012, operating out of a garage in Palo Alto. The initial concept was simple: a mobile app where users could order groceries from local stores, with shoppers (later called "Instacart shoppers") fulfilling the orders. The first stores to partner were Safeway and Whole Foods, both of which saw the potential in offloading labor-intensive tasks to third parties. The early days were brutal. The founders had to convince skeptical retailers that their model wouldn’t cannibalize in-store sales. They also had to recruit shoppers willing to work for modest pay—often less than minimum wage, a criticism that would later dog the company. Yet the demand was immediate. Within months, Instacart had processed thousands of orders, proving that consumers were willing to pay for convenience.3. The Role of Venture Capital in Shaping Instacart
Instacart’s growth wasn’t organic—it was fueled by venture capital. The company raised its first round of funding in 2013, led by Andreessen Horowitz, with additional backing from Sequoia Capital and Instagram co-founder Kevin Systrom. These investors saw potential in a market they believed was underserved. By 2015, Instacart had raised over $200 million, allowing it to expand rapidly across the U.S. The funding wasn’t without controversy. Critics argued that Instacart’s valuation was inflated, given the thin margins in grocery delivery. Yet the founders leveraged the capital to refine their model, improving technology and shopper incentives. The VC backing also provided credibility with retailers, who were more willing to partner with a company backed by Silicon Valley heavyweights.4. The Shift from Tech to Logistics
Early Instacart relied heavily on its app and shopper network, but the real challenge was logistics. Stores had to integrate with Instacart’s platform, shoppers had to navigate inventory, and deliveries had to meet tight time windows. The founders quickly realized that technology alone wouldn’t solve these problems—they needed operational rigor. By 2014, Instacart had hired former Amazon and Uber logistics experts to streamline operations. The company also introduced Instacart Plus, a subscription service that guaranteed faster delivery, further solidifying its market position. This shift from pure tech to end-to-end logistics became a defining feature of Instacart’s growth strategy.5. The Controversy Over Shopper Pay and Labor Practices
One of the most contentious aspects of Instacart’s rise was its treatment of shoppers. Early on, shoppers were paid per order, often earning less than minimum wage when factoring in gas and time. This led to lawsuits and criticism from labor advocates, who argued that Instacart was exploiting gig workers. The founders defended the model, citing the flexibility it offered shoppers. Yet the controversy forced Instacart to adjust its pay structure, eventually introducing minimum wage guarantees and benefits. This evolution reflected a broader industry reckoning with gig economy labor practices, one that Instacart navigated with mixed success.6. The Acquisition That Nearly Didn’t Happen
In 2020, Instacart was on the brink of an IPO, but the pandemic changed everything. With grocery demand surging, the company became a lifeline for consumers. Amazon, which had been quietly expanding its own grocery delivery service, saw an opportunity. In August 2020, Amazon acquired Instacart for a reported $13.7 billion, making it one of the largest tech acquisitions of the year. The deal was contentious. Some argued that Amazon was buying Instacart to eliminate competition, while others saw it as a strategic move to integrate Instacart’s logistics network with Amazon Fresh. For the founders, the acquisition was a validation of their vision—even if it meant stepping back from day-to-day operations."Instacart was built on the belief that grocery delivery was the next frontier of e-commerce. The acquisition by Amazon proves that the market saw it the same way." — Apoorva Mehta, Instacart founder and CEO (2020)
7. The Founders’ Post-Instacart Ventures
After the Amazon acquisition, the founders took different paths. Mehta remained involved in Instacart’s leadership but shifted focus to new ventures, including Flexport, a logistics startup. Mullen and Leonardo also explored entrepreneurship, with Mullen co-founding a company focused on AI-driven retail solutions. Their post-Instacart careers reflect a broader trend in Silicon Valley: founders who build successful companies often pivot to new challenges. For Mehta, Mullen, and Leonardo, Instacart was a proving ground—one that reshaped an industry and set the stage for their next moves.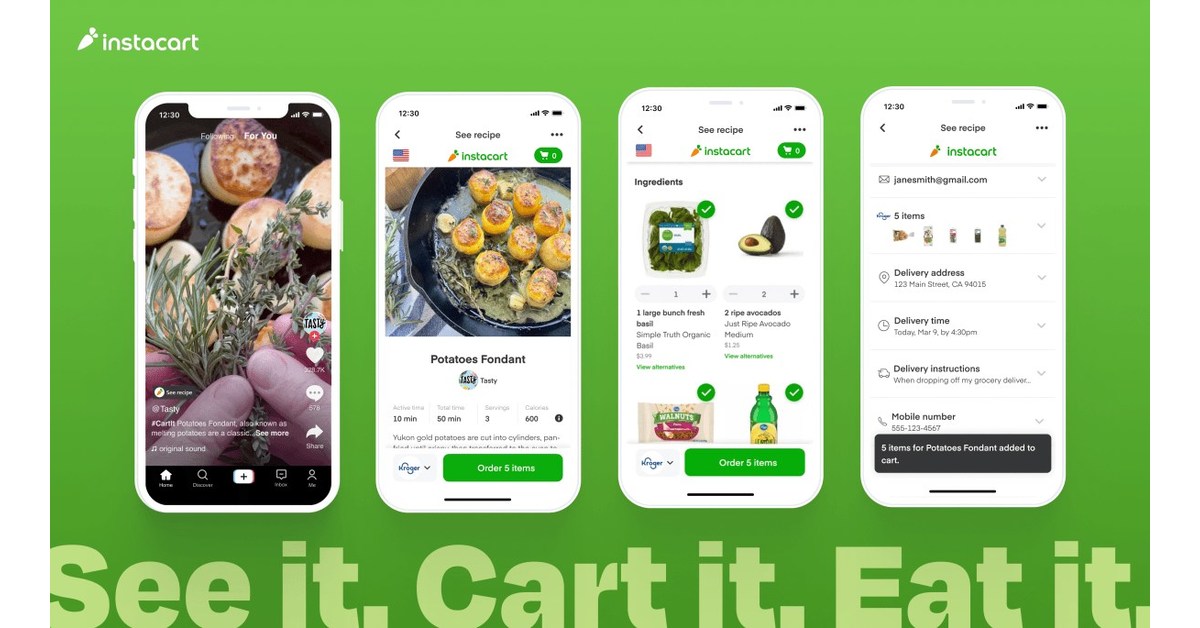
How These Facts Connect
The story of who created Instacart is more than a tale of three entrepreneurs. It’s a case study in how technology, logistics, and market timing collide to create a disruptor. The founders’ diverse backgrounds allowed them to tackle problems others had failed at—convincing retailers to partner, scaling a shopper network, and navigating labor challenges. Their ability to pivot from tech to operations was critical when early assumptions proved flawed. Instacart’s rise also highlights the role of venture capital in shaping modern startups. Without Andreessen Horowitz and Sequoia’s backing, the company might never have expanded beyond Palo Alto. Yet the capital came with pressure to grow quickly, which led to operational shortcuts—like underpaying shoppers—that later required course corrections. The Amazon acquisition, while lucrative, also revealed the limits of independent scaling in a market dominated by tech giants.| Key Factor | Impact on Instacart | Long-Term Outcome |
|---|---|---|
| Founders’ diverse skills | Allowed rapid problem-solving in tech and logistics | Built a scalable model that attracted VC funding |
| Early retailer partnerships | Validated the grocery delivery concept | Enabled national expansion within 2 years |
| Amazon acquisition | Provided capital and infrastructure | Shifted Instacart from independent startup to Amazon subsidiary |
Conclusion
Instacart’s creation wasn’t inevitable—it was the result of a specific moment in tech and retail history. The founders’ willingness to take risks, combined with the right investors and market conditions, turned a garage-based experiment into a billion-dollar company. Yet the journey also exposed the complexities of scaling a labor-dependent business in an era of gig economy scrutiny. Today, Instacart operates under Amazon’s umbrella, but its legacy endures. It proved that even traditional industries could be disrupted by tech-savvy entrepreneurs. For those asking who created Instacart, the answer lies in the intersection of ambition, adaptability, and the willingness to challenge the status quo.Comprehensive FAQs
Q: Who are the three founders of Instacart?
A: Instacart was co-founded by Apoorva Mehta (CEO), Max Mullen (CTO), and Brandon Leonardo (COO). Each brought distinct skills: Mehta’s tech and fundraising experience, Mullen’s retail tech background, and Leonardo’s operational expertise.
Q: How did Instacart get its first stores to partner?
A: The founders pitched Instacart to retailers like Safeway and Whole Foods by emphasizing cost savings and efficiency. Early partnerships were secured through direct negotiations, often offering retailers a cut of delivery fees to offset labor costs.
Q: Why did Instacart struggle with shopper pay early on?
A: Instacart’s initial pay model—per-order compensation—led to shoppers earning below minimum wage when factoring in expenses. The company defended this as a trade-off for flexibility, but labor lawsuits and public backlash forced adjustments, including minimum wage guarantees.
Q: What happened to the founders after the Amazon acquisition?
A: After the 2020 acquisition, Mehta remained involved in Instacart’s leadership but focused on new ventures, including Flexport. Mullen and Leonardo also pursued entrepreneurship, with Mullen co-founding a retail tech startup and Leonardo exploring operational consulting.
Q: Could Instacart have succeeded without venture capital?
A: Unlikely. While the founders’ initial funding came from personal savings and early revenue, Instacart’s rapid expansion required VC backing. Without Andreessen Horowitz and Sequoia’s investment, the company would not have scaled nationally or attracted major retailers.
Q: Did Instacart’s model change after the Amazon acquisition?
A: Yes. While Instacart retained its brand and operations, Amazon integrated its logistics network, improving delivery speed and reliability. The acquisition also shifted Instacart’s focus from independent growth to aligning with Amazon’s broader retail strategy.
Q: What was the biggest challenge in Instacart’s early years?
A: Convincing retailers to adopt a third-party delivery model. Many feared Instacart would drive customers away from stores. The founders overcame this by offering retailers a share of delivery fees and demonstrating that in-store sales often increased due to convenience.
