
Where It All Began
The post-World War II era wasn’t just about economic recovery—it was about US median wealth becoming a political and social battleground. After decades of Depression-era austerity, the New Deal and subsequent policies had reshaped the American dream into something tangible: homeownership, union wages, and the promise of upward mobility. By the 1950s, US median wealth had surged as veterans returned, bought homes with GI loans, and filled the expanding middle class. The statistic became a proxy for national pride. If the median was rising, the country was thriving. But the cracks appeared early. By the 1970s, stagnant wages and inflation had eroded the purchasing power of that hard-won wealth. The median net worth—adjusted for inflation—began a slow decline, a trend economists would later attribute to globalization, deregulation, and the hollowing out of manufacturing jobs. The 1980s tax cuts, while boosting growth, also widened the gap between the wealthy and everyone else. US median wealth stopped being a unifying metric and became a fault line. The Reagan era’s rhetoric of individualism clashed with the reality that for many, the American dream had become a myth.The Early Signs
The 1990s brought a brief reprieve. The dot-com boom and the housing bubble of the early 2000s inflated asset values, lifting US median wealth to record highs by 2007. But the crash that followed wasn’t just financial—it was existential. The median net worth plummeted by nearly 40% between 2007 and 2010, wiping out decades of progress for millions. The Great Recession exposed a harsh truth: US median wealth wasn’t just a reflection of economic performance; it was a barometer of systemic risk. When the housing market collapsed, so did the wealth of the middle class. The recovery that followed was uneven. While the stock market rebounded, wages stagnated, and the cost of living—especially housing—rose faster than inflation. By 2016, the Federal Reserve’s data showed that US median wealth had finally inched back to pre-recession levels, but only because the ultra-wealthy had seen their portfolios explode. For everyone else, the recovery felt more like a reset than a rebound. The median had returned, but the middle class hadn’t.The Turning Point
The 2008 financial crisis wasn’t just a turning point—it was the moment US median wealth became a political weapon. The Occupy Wall Street movement in 2011 wasn’t just about inequality; it was about the erosion of the median. Protesters held signs reading “We Are the 99%”, a direct challenge to the concentration of wealth at the top. The median net worth, once a source of national pride, had become a symbol of economic betrayal. Politicians on both sides of the aisle began framing policies around it, from Bernie Sanders’ wealth taxes to Trump’s populist rhetoric about “draining the swamp.” The turning point wasn’t just ideological—it was demographic. Millennials, entering the workforce during the recession, faced a job market that offered little stability and student debt that crushed their ability to build wealth. Their entry into the labor force coincided with the slowest wealth accumulation in generations. US median wealth for households under 35 plummeted, while older generations saw their savings erode. The median became a generational fault line, with younger Americans asking whether they’d ever catch up.“The median is a lie. It smooths over the truth—that for most people, wealth isn’t about the stock market or inheritance. It’s about whether you can afford a down payment on a house, whether your kid’s college fund will outlast a recession, whether you’ll ever stop working just to get by.” — Economist Raj Chetty, Stanford University
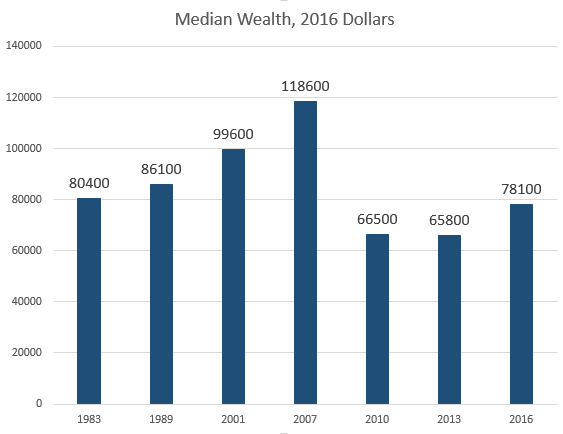
The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 1945–1970 | Post-war prosperity, GI Bill, strong unions, and suburban expansion drove US median wealth to historic highs. Homeownership rates soared, and asset values grew steadily. |
| 1980–2000 | Deregulation, financial innovation, and the dot-com boom inflated asset prices. US median wealth peaked in 2000, but the gains were uneven—most middle-class families saw little real growth. |
| 2007–2012 | The Great Recession wiped out $16 trillion in household wealth. US median wealth fell by nearly 40%, with the poorest households losing the most. The recovery was slow and unequal. |
| 2016–Present | Stock market gains and rising home prices boosted US median wealth to new highs, but wage stagnation and student debt kept most families from sharing in the growth. The pandemic exacerbated divides. |
Lessons From the Journey
- Wealth isn’t just about income—it’s about assets. The median net worth is heavily tied to homeownership and stock ownership. When housing crashes or markets stall, the median suffers disproportionately.
- Policy matters more than rhetoric. The New Deal’s focus on homeownership and unions created lasting wealth for the middle class. Modern policies, like student debt relief or housing subsidies, could reverse the trend.
- Generational wealth is a zero-sum game. If younger generations can’t build savings, the median will stagnate—regardless of market performance.
- The median hides extreme inequality. A rising median doesn’t mean everyone is doing better—just that the average is being pulled up by the ultra-rich.
Where Things Stand Today
As of 2023, US median wealth stands at roughly $188,000, according to Federal Reserve data. On the surface, that’s progress—nearly double the 2010 lows. But the reality is far more complex. The median is propped up by a combination of soaring home prices in high-cost cities, a bull market that has enriched the top 10%, and a pandemic-era stimulus that temporarily boosted savings. For most Americans, however, the gains have been illusory. Wages remain flat, student debt has ballooned, and the cost of healthcare and childcare has outpaced inflation. The bigger story isn’t the number itself—it’s what it obscures. The median tells us little about the 60% of Americans who can’t cover a $1,000 emergency or the 40% who report struggling to afford basic necessities. It doesn’t account for the fact that Black and Hispanic households hold only about 10% of the wealth white households do. US median wealth has become a statistical mirage, a number that suggests stability while masking deep instability. The question now isn’t whether the median will keep rising—it’s whether it matters anymore.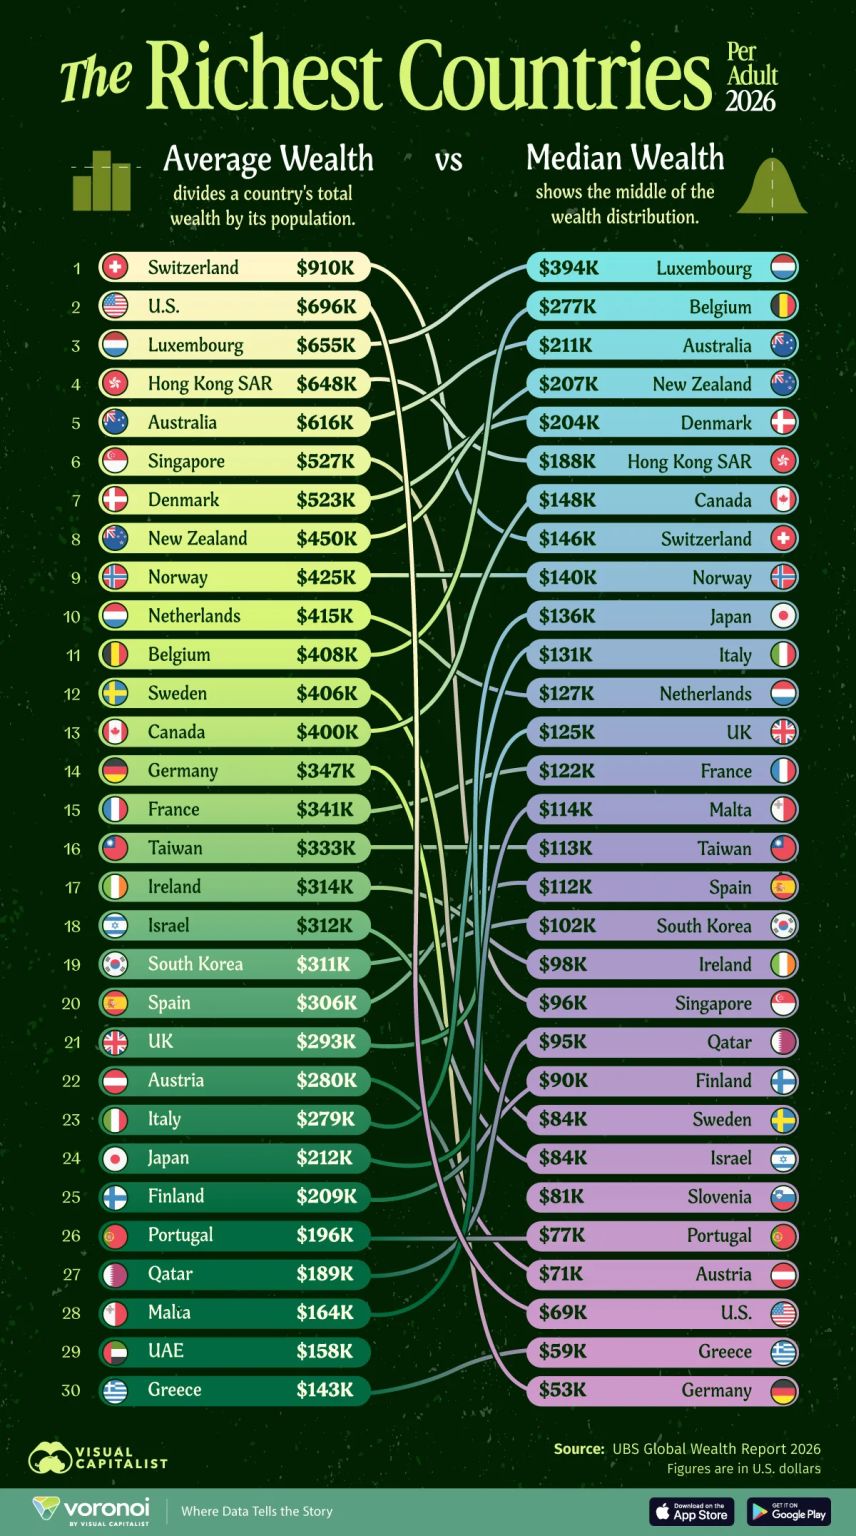
Conclusion
The history of US median wealth is the story of America’s economic soul. It reflects our collective ambition, our failures, and our contradictions. The median wasn’t meant to be a measure of inequality—it was supposed to be proof that the system worked. But when the median becomes a relic, when it no longer reflects the lived experience of most Americans, it’s a sign that something fundamental has broken. The challenge now isn’t just to restore the median to its former glory—it’s to redefine what wealth means in a country where opportunity is no longer guaranteed. The data tells us one thing: US median wealth will keep rising as long as asset prices climb and the rich get richer. But the real test is whether that wealth trickles down—or whether it remains a distant dream for the majority. The answer will determine not just the economy, but the future of American democracy itself.Comprehensive FAQs
Q: How is US median wealth calculated?
The Federal Reserve’s Survey of Consumer Finances measures US median wealth by subtracting liabilities (debt) from assets (home equity, investments, retirement accounts). It’s reported every three years, with supplemental estimates in between. The median is the middle value when all households are ranked by net worth.
Q: Why does US median wealth matter more than average wealth?
The average (mean) wealth is skewed by the ultra-rich—think of a few billionaires dragging the number up. The median gives a clearer picture of what a typical household holds, making it a better gauge of middle-class economic health.
Q: How does student debt affect US median wealth?
Student debt suppresses wealth accumulation by delaying home purchases, retirement savings, and other investments. A 2022 study found that US median wealth for households with student debt is 40% lower than for those without. The burden falls hardest on younger generations.
Q: Can US median wealth ever return to 1990s levels?
Unlikely, given today’s economic realities. The 1990s median was inflated by the dot-com boom and a strong labor market. Today’s challenges—stagnant wages, high housing costs, and student debt—make a full recovery improbable without major policy shifts.
Q: What policies could improve US median wealth?
Options include:
- Expanding homeownership programs (e.g., down payment assistance).
- Student debt relief or income-based repayment reforms.
- Stronger wage growth through union support or minimum wage hikes.
- Tax reforms that reduce wealth concentration (e.g., higher capital gains taxes).
Q: How does US median wealth compare globally?
The US median is higher than most developed nations (e.g., Germany’s is around $110,000, adjusted for PPP), but the gap between rich and poor is wider. Countries with stronger social safety nets—like Nordic nations—see less volatility in median wealth.
