
5 Things Worth Knowing About Total Household Net Worth in the US, 2010
The data from 2010 paints a picture of a country still grappling with the aftermath of the financial crisis, where wealth accumulation had become a privilege rather than a universal outcome. The figures tell a story of regional divides, asset class disparities, and the lingering effects of policy responses—from the stimulus to the housing market’s slow thaw. Here’s what stood out.1. The National Median Was Still Below 2007 Levels
By 2010, the median total household net worth in the U.S. had fallen to around $93,100, according to Federal Reserve estimates—nearly 37% below its 2007 peak of $146,500. This decline reflected the collapse of home values, which accounted for roughly 60% of total household wealth at the time. The drop wasn’t uniform; urban areas with speculative housing bubbles, like Phoenix and Miami, saw median net worths plummet by over 50%. Rural and less volatile markets fared better, but even there, the erosion of equity left millions underwater on mortgages. The median figure masked a deeper truth: the bottom 50% of households had lost $1.2 trillion in net worth since 2007, while the top 10% had lost far less in relative terms. What made this stagnation particularly troubling was the lack of upward mobility. Unlike previous recessions, where wealth rebounded as employment recovered, 2010’s recovery was asset-driven—meaning those without homes or stocks to gain were left behind. The Fed’s data showed that by 2010, 43% of families had net worth below $50,000, up from 35% in 2007. This wasn’t just a statistical blip; it was evidence of a structural shift where wealth accumulation had become concentrated in fewer hands.2. Stock Market Recovery Favored Older, Wealthier Households
While home values remained depressed, the stock market began its ascent in 2009, and by 2010, the S&P 500 had nearly doubled from its March 2009 low. This rebound disproportionately benefited households with retirement accounts—particularly those in their 50s and 60s, who had seen 401(k) balances recover faster than younger workers. The total household net worth tied to financial assets (stocks, bonds, mutual funds) rose by $2.5 trillion in 2010 alone, according to the Fed’s Flow of Funds report. However, only 30% of households owned stocks directly, and those under 35 had seen their portfolios shrink by an average of 25% since 2007. The disparity was stark when comparing households headed by someone over 65—where 60% held stocks—versus those under 35, where the rate was below 15%. This wasn’t just about age; it was about legacy wealth. Older Americans had benefited from decades of compounding returns, while younger generations faced a double whammy: stagnant wages and the burden of student loans, which had surged to $830 billion by 2010. The stock market’s recovery, in other words, was a wealth transfer from the young to the old.3. Homeownership Rates Hit a 15-Year Low
The housing market’s collapse had a delayed but devastating impact on total household net worth. By 2010, the homeownership rate had fallen to 66.4%, the lowest since 1998. The decline wasn’t just about foreclosures—it reflected a broader shift in behavior. Many renters, facing tight credit markets, chose not to attempt home purchases, while others who had bought at peak prices in 2006-2007 found themselves trapped in negative equity. The Fed’s data showed that 23% of mortgaged homes were worth less than the loan balance, a figure that had ballooned from just 2% in 2005. Regional differences were extreme. In Nevada, home values had dropped by 60% from their 2006 highs, while in Texas, they fell by only 15%. The total household net worth in states like California and Florida—where housing had driven wealth for decades—was still 15-20% below 2007 levels by 2010. Even as prices began to stabilize in late 2010, the damage was done: millions of homeowners had lost their primary wealth-building tool, and renting had become a long-term lifestyle for many.4. Student Debt Emerged as a New Wealth Drag
One of the most underappreciated factors in 2010’s total household net worth dynamics was the explosion of student loan debt. While the Fed didn’t track student loans separately until 2013, industry estimates placed the total at $830 billion by 2010—up from $540 billion in 2007. This debt was unique because it couldn’t be discharged in bankruptcy and carried interest rates that often exceeded inflation. For households with young adults, student loans acted as a negative asset, offsetting any gains from employment or homeownership. The impact was most severe for minority households. Black and Hispanic families were three times more likely to have student debt than white families, according to a 2011 Brookings Institution study. This debt wasn’t just delaying major purchases—it was reducing the ability to build equity in other assets. By 2010, 40% of borrowers were already behind on payments, and defaults were rising sharply. The Fed’s data suggested that households with student debt had 20% lower net worth than those without, a gap that would widen in the coming years."Student loans are the new subprime crisis—except this time, the debt can’t be walked away from, and it’s crushing the very people who were supposed to be the future workforce." — Mark Zandi, Moody’s Analytics, 2010
5. The Top 10% Held 70% of All Wealth
The most glaring statistic from 2010 was the concentration of wealth. The total household net worth in the U.S. was $56.7 trillion, but the top 10% of families held $42.1 trillion of that—nearly 70%. This wasn’t new, but the gap had deepened. In 2007, the top 10% held 68% of wealth; by 2010, that share had risen despite the recession. The bottom 50%, meanwhile, saw their share shrink from 2.6% to 2.2%. What drove this disparity? Inheritance played a role, but the real accelerant was asset price inflation. The top 10% owned 80% of all stocks and mutual funds, while the bottom 50% owned just 0.5%. Even as home values recovered, the wealthiest households had diversified portfolios that benefited from the stock market’s rebound. For the rest, the recovery felt like a mirage—wages stagnated, unemployment remained high, and the safety net was stretched thin.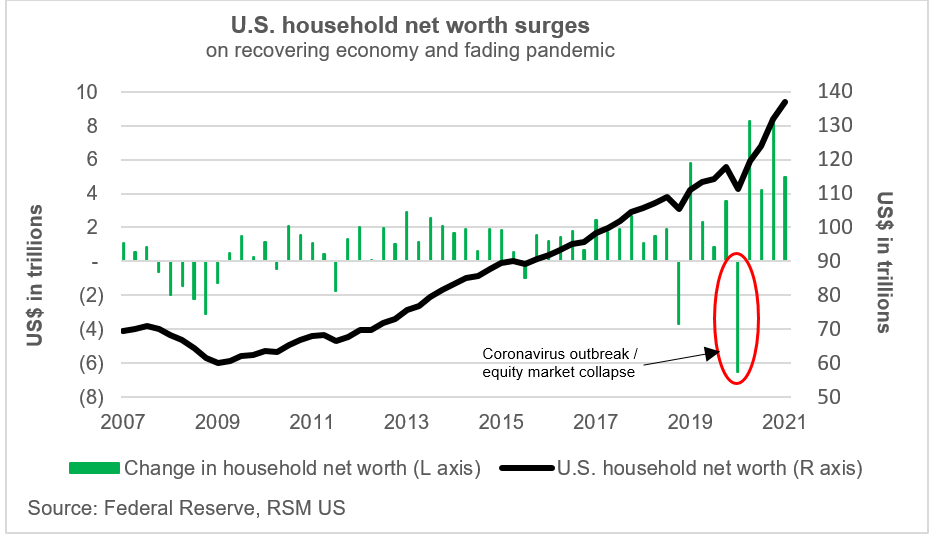
How These Facts Connect
The data from 2010 doesn’t just describe a financial snapshot; it reveals the mechanisms of a two-tiered recovery. On one side, older, asset-rich households saw their net worth rebound as stocks and home values stabilized. On the other, younger families, minorities, and renters faced a decade of stagnation, where debt outpaced income and wealth-building tools like homeownership were out of reach. The total household net worth in 2010 wasn’t just a number—it was a symptom of a system where wealth begets wealth, and where the crisis’s scars fell hardest on those least able to recover. The Fed’s estimates also highlighted how policy responses had uneven effects. The 2009 stimulus had prevented a deeper recession, but it didn’t address the structural issues: rising inequality, declining homeownership, and the student debt bubble. By 2010, it was clear that without targeted interventions—like expanded credit access or student loan reform—the recovery would favor the already wealthy. The year’s data foreshadowed the political and economic battles of the 2010s, from debates over the minimum wage to the rise of populist movements demanding wealth redistribution.| Key Factor | 2007 Level | 2010 Level | Impact on Wealth |
|---|---|---|---|
| Median Net Worth | $146,500 | $93,100 | 37% decline; bottom 50% lost $1.2T |
| Homeownership Rate | 68.1% | 66.4% | 15-year low; negative equity at 23% |
| Stock Market Ownership (Under 35) | 18% | 15% | Younger households excluded from recovery |
| Top 10% Wealth Share | 68% | 70% | Concentration accelerated despite recession |

Conclusion
The total household net worth in the U.S. during 2010 was a story of uneven recovery and deepening divides. The numbers told of a country where the financial crisis had reshaped the rules of wealth accumulation, favoring those with existing assets while leaving others behind. For policymakers, the lesson was clear: without deliberate efforts to address inequality, the recovery would remain a privilege, not a shared experience. For households, the message was harsher—wealth wasn’t just about income; it was about timing, location, and luck. A decade later, the patterns from 2010 would define the 2020s. The same households that struggled in 2010—those with student debt, negative equity, or no access to financial markets—would face the COVID-19 pandemic with far less resilience. The data from 2010 wasn’t just historical; it was a warning.Comprehensive FAQs
Q: How did the 2010 total household net worth compare to 2007?
The total household net worth in the U.S. fell from $68.2 trillion in 2007 to $56.7 trillion in 2010, a decline of 17%. The median net worth dropped by 37%, reflecting the collapse in home values and stock portfolios. However, the top 10% saw far smaller losses, widening the wealth gap.
Q: Which states had the worst declines in net worth by 2010?
States with housing bubbles—Nevada, Florida, California, and Arizona—saw the steepest drops in total household net worth, with declines ranging from 20% to 30% below 2007 levels. Rural and Midwestern states, where housing had been more stable, fared better, with declines closer to 10-15%.
Q: Did the stock market recovery in 2010 help most households?
No. While the S&P 500 rebounded strongly in 2010, only 30% of households owned stocks directly. The recovery disproportionately benefited older Americans with retirement accounts, while younger households—especially those with student debt—saw little to no gain from the market’s rise.
Q: How did student loans affect net worth in 2010?
By 2010, student debt had surged to $830 billion, acting as a negative asset for millions. Households with student loans had 20% lower net worth than those without, and defaults were rising sharply. The debt burden was particularly severe for minority families, who were three times more likely to hold student loans.
Q: What was the biggest policy failure in addressing net worth declines?
The 2009 stimulus prevented a deeper recession but failed to target structural issues like homeownership collapse, student debt, and wage stagnation. Without reforms to credit access, housing affordability, or student loan repayment, the recovery remained concentrated among the wealthy, deepening long-term inequality.
Q: How did the 2010 net worth data foreshadow future trends?
The total household net worth in 2010 revealed trends that would dominate the 2010s: rising student debt, wealth concentration, and stagnant wages. These factors contributed to the 2016 populist backlash, the 2020 racial wealth gap debates, and the COVID-19 pandemic’s unequal economic impact. The data essentially predicted a decade of financial stress for middle- and lower-income households.
