Where It All Began
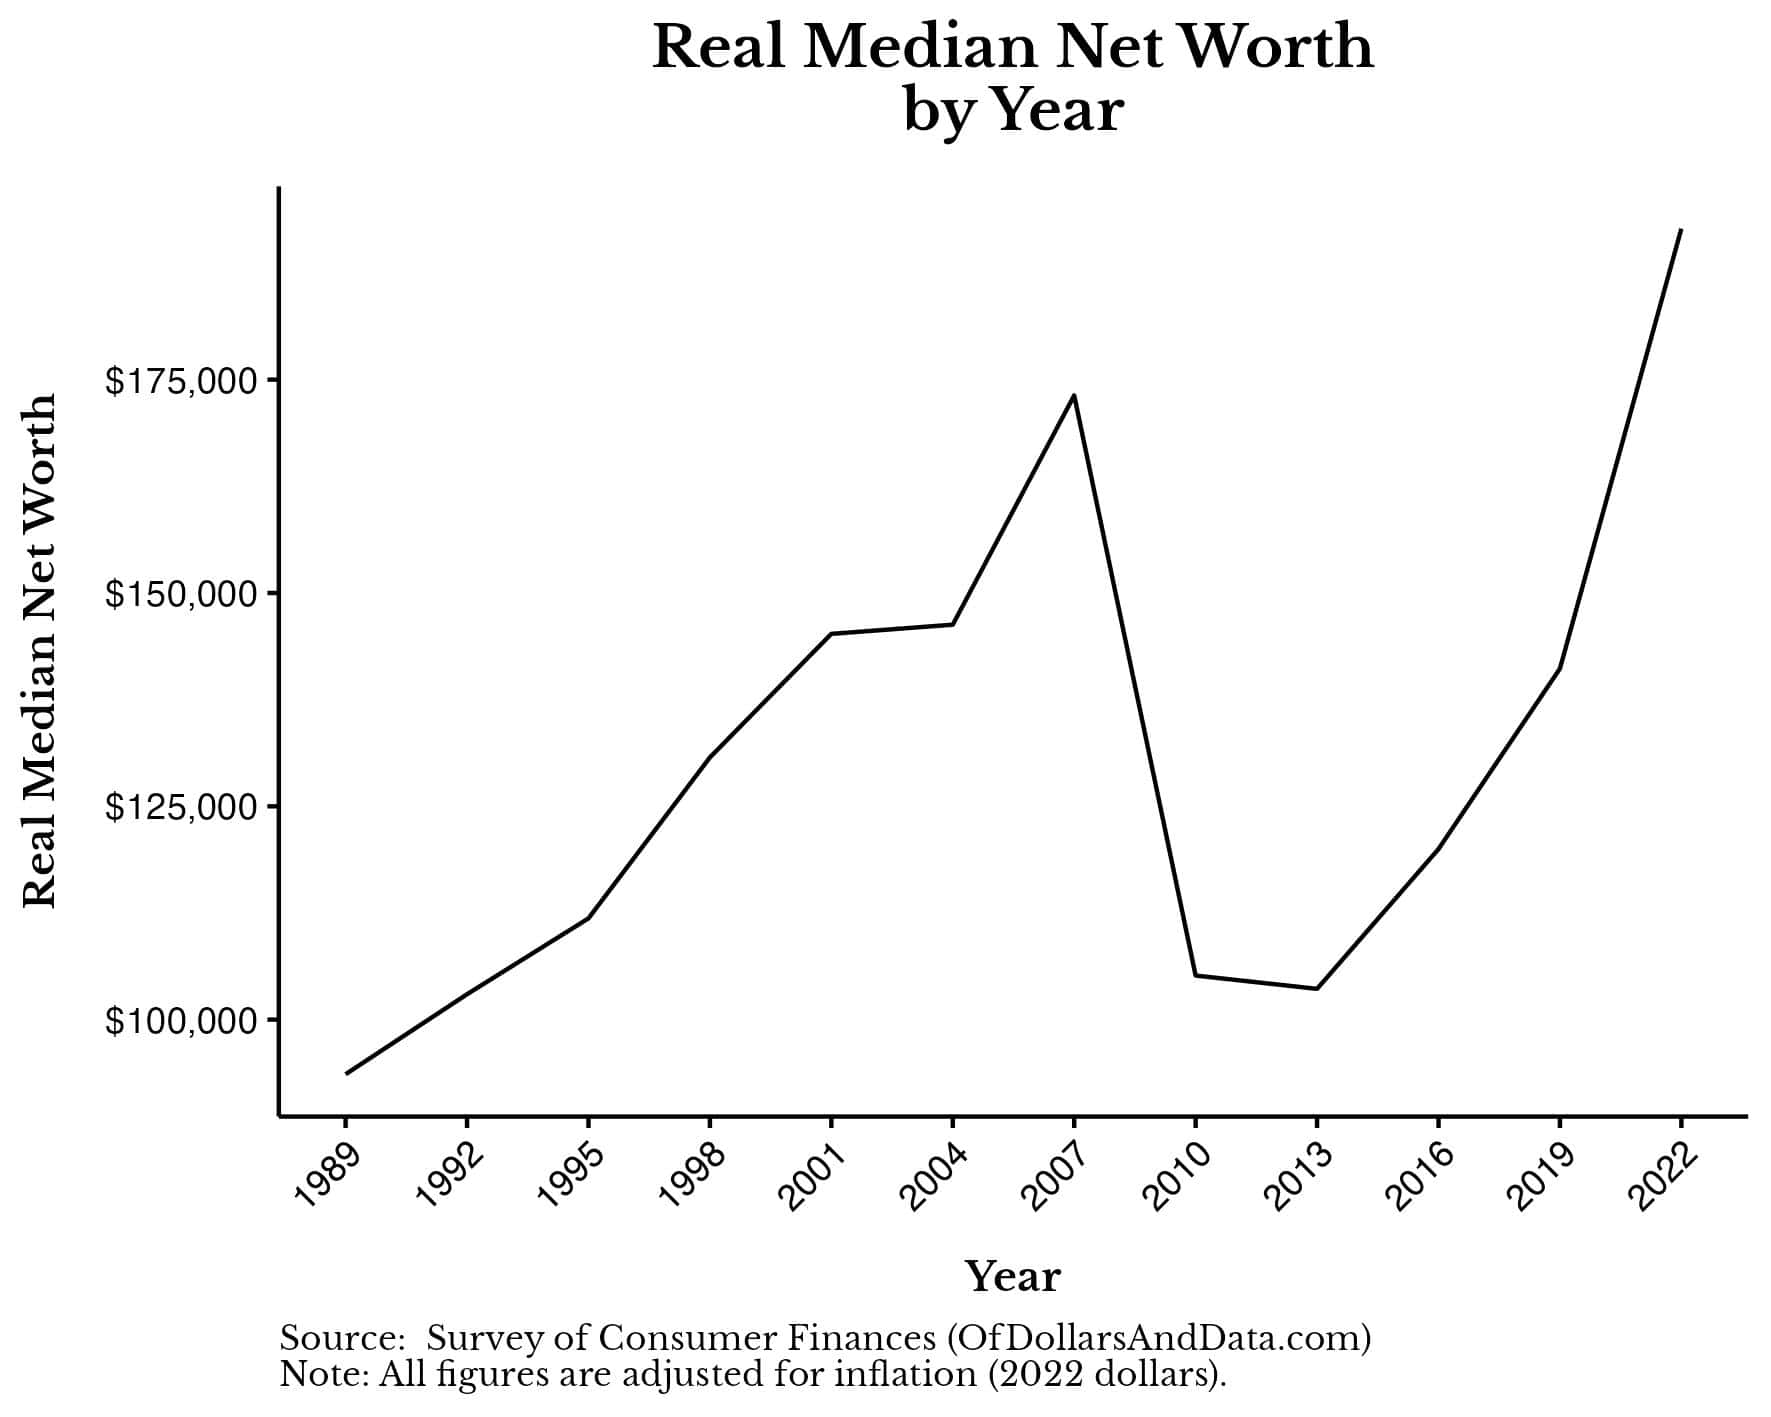
The roots of the average median net worth 2016 stretch back to 2007, when the housing bubble burst and took the financial system with it. By 2010, the median net worth of American households had plunged by nearly 40%, wiping out decades of accumulated wealth in a single collapse. The Federal Reserve’s Survey of Consumer Finances, conducted every three years, became the primary tool for tracking the fallout. The 2013 report—covering data up to 2013—showed that the median net worth had only just begun to crawl back from its lows, still 36% below its 2007 peak. The recovery, when it came, was slow and uneven. While some sectors rebounded quickly, others remained frozen in time. Young adults, hit hardest by the job market collapse, saw their net worth stagnate as wages failed to keep pace with inflation. Meanwhile, older households, many of whom owned homes, began to see their equity rebuild—but only if they’d avoided foreclosure. The average median net worth 2016 wasn’t just a rebound; it was a test of resilience. The data showed that by 2016, the median net worth had finally surpassed its 2007 level, but the gains were concentrated. Homeownership rates, which had plummeted during the crisis, began to stabilize, but the wealth gap between homeowners and renters widened. The bottom 50% of households—those with net worth below $93,400—had seen only modest improvements, while the top 1% had not just recovered but thrived. The narrative of economic recovery, often framed in terms of GDP growth and employment numbers, now had a human face: a household balance sheet that told a story of partial healing and persistent inequality.The Early Signs
Long before the 2016 report was released, there were whispers in the data. The Federal Reserve’s 2013 survey had shown that the median net worth for white households was $134,200, compared to $11,000 for black households and $13,700 for Hispanic households—a disparity that predated the recession but was exacerbated by it. By 2016, the gap had narrowed slightly, but not enough. The average median net worth 2016 for white households remained nearly $97,300, while for black households it inched up to $13,600. The progress was real, but the systemic barriers remained. Student debt, which had ballooned to $1.3 trillion by 2016, weighed heavily on younger households, many of whom were just starting to build wealth. Meanwhile, older households, particularly those of retirement age, saw their savings erode as low-interest-rate environments squeezed returns on fixed-income investments. The average median net worth 2016 also reflected the impact of asset price inflation. Stock markets had rebounded sharply, but only those with existing portfolios benefited. For the majority of Americans, who lacked retirement accounts or investments, the recovery felt distant. The data pointed to a fundamental truth: wealth begets wealth. Those who entered the recession with savings or assets were better positioned to recover, while those who didn’t were left behind. The median net worth in 2016 wasn’t just a number—it was a snapshot of an economy where opportunity was still tied to pre-existing advantage.The Turning Point
The shift toward the average median net worth 2016 as a focal point in economic discussions came in 2015, when the Federal Reserve’s 2013 data was finally analyzed in the context of the emerging recovery. Economists began to ask: Was the rebound real, or was it just the wealthy pulling ahead? The answer, as the 2016 data confirmed, was complicated. Yes, the median net worth had climbed, but the composition of that wealth had changed. Home values, which had been the backbone of middle-class wealth for decades, were finally rising in many markets—but only for those who owned. Renters, who made up a growing share of households, saw no such gains. The stock market’s surge benefited those with 401(k)s and IRAs, while wages for the average worker stagnated. What made 2016 distinct was the political backdrop. The election of Donald Trump in November 2016 promised a radical rethinking of economic policy, from tax cuts to deregulation. The average median net worth 2016 became a battleground in debates about whether the recovery had been broad-based or just a trickle-down effect. Critics argued that the numbers proved the system was rigged—wealth was accumulating at the top, while the middle class was left to pick up the pieces. Supporters countered that the data showed progress, even if it was uneven. The truth, as always, lay somewhere in between. The median net worth was rising, but the question of who was benefiting remained unanswered."The recovery from the Great Recession has left deep scars. The median net worth is up, but the distribution of that wealth tells a different story—one of persistent inequality and limited mobility." — Federal Reserve Economist, 2017

The Build-Up, Year by Year
The path to the average median net worth 2016 was paved with economic shifts, policy changes, and unforeseen crises. Below is a breakdown of the key periods that shaped the data:| Period | Key Developments |
|---|---|
| 2007-2009 | The Great Recession wipes out $16 trillion in household wealth. The median net worth plummets by 38.8%, with the bottom 90% losing $11.7 trillion while the top 1% sees a 1.1% decline. Homeownership rates drop, and stock portfolios evaporate. |
| 2010-2013 | Slow recovery begins. The median net worth stabilizes but remains 36% below 2007 levels. The Fed’s quantitative easing boosts asset prices, but wages stagnate. The bottom 50% of households see little improvement, while the top 10% begin to regain lost ground. |
| 2014-2015 | Housing markets recover in many regions, pushing home values up. The median net worth for homeowners begins to rise, but renters—now 36% of households—see no benefit. Stock market gains favor those with retirement accounts, widening the wealth gap. |
| 2016 | The average median net worth finally surpasses its 2007 peak at $97,300, but the recovery is uneven. The top 10% hold 71% of all liquid assets, while the bottom 50% hold just 2.6%. Student debt reaches $1.3 trillion, dragging down younger households. |
Lessons From the Journey
The data leading to the average median net worth 2016 offers several key insights:- Wealth inequality is structural. The gap between white and minority households persisted, with black and Hispanic families holding just 5-10% of the median net worth of white families.
- Homeownership remains the primary wealth-building tool. Those who owned homes in 2016 saw their equity rebound, while renters were left behind.
- Asset price inflation benefits the wealthy. Stock market and real estate gains disproportionately helped those who already owned assets.
- Student debt is a wealth drag. Younger households, burdened by loans, had negative median net worth in some cases.
- The recovery was job-driven, not wage-driven. Employment rose, but real wages for the median worker stagnated.
- Policy matters. The Fed’s monetary policies helped asset owners, but fiscal policies—like tax cuts—would later be debated as tools to bridge the gap.
Where Things Stand Today
A decade after the average median net worth 2016 report, the story has evolved—but the core issues remain. The median net worth in 2021 stood at $120,400, up from 2016, but the distribution tells a familiar tale. The bottom 50% of households still hold just 2.6% of all wealth, while the top 1% hold 32%. The pandemic exacerbated these trends: stock market gains soared, but millions of workers faced layoffs or reduced hours. The median net worth for black and Hispanic households remains a fraction of that for white households, reflecting centuries of systemic barriers. Meanwhile, student debt has ballooned to $1.7 trillion, delaying wealth-building for an entire generation. The average median net worth 2016 was more than a statistic—it was a warning. It showed that economic recovery could coexist with deepening inequality. Today, the question is whether the lessons of 2016 have been learned. Policymakers now grapple with whether to focus on broad-based growth or targeted interventions to close the wealth gap. The data from 2016 remains a benchmark, a reminder that wealth isn’t just about numbers—it’s about opportunity, access, and the kind of economy we choose to build.
Conclusion
The average median net worth 2016 was a moment in time, but its implications stretch far beyond that year. It captured the tension between recovery and stagnation, between progress and persistence. The numbers told a story of an economy that had healed in some ways but remained fractured in others. For policymakers, it was a call to action. For economists, it was a puzzle to solve. For ordinary Americans, it was a reflection of their own financial struggles—or, in some cases, their unexpected windfalls. A decade later, the conversation continues. The median net worth is no longer the sole measure of economic health, but it remains a critical lens through which to view inequality. The question now is whether the lessons of 2016 will shape a more equitable future—or if history will repeat itself, with another generation left behind.Comprehensive FAQs
Q: What exactly is the difference between median and average net worth?
The median net worth is the middle value when all households are ranked by wealth—half have more, half have less. The average (mean) net worth is the total wealth divided by the number of households, which is skewed higher by ultra-wealthy individuals. In 2016, the median was $97,300, while the average was $650,000, showing how wealth concentration distorts perceptions of prosperity.
Q: Why did the median net worth take so long to recover after the 2008 crash?
The recovery was slow because the crisis hit different groups at different times. Homeowners saw equity rebuild as housing markets recovered, but renters gained nothing. Younger households, burdened by student debt and stagnant wages, struggled to accumulate wealth. Meanwhile, the wealthy saw their portfolios rebound quickly, widening the gap. The median net worth 2016 only surpassed 2007 levels because home values and stock markets finally stabilized—but the gains were uneven.
Q: How did student debt impact the median net worth in 2016?
Student debt acted as a wealth drag, particularly for younger households. By 2016, $1.3 trillion in student loans weighed down borrowers, many of whom were just entering the workforce. Unlike other debts, student loans are difficult to discharge in bankruptcy, forcing borrowers to delay major wealth-building steps like homeownership or investing. This contributed to the median net worth for households under 35 being negative in some cases, as liabilities exceeded assets.
Q: Were there any demographic groups that saw significant improvements by 2016?
Yes, but with caveats. Homeowning households, particularly older white families, saw their net worth rebound as home values rose. The median net worth for white households in 2016 was $168,600, up from $134,200 in 2013. However, black and Hispanic households saw only modest gains, with medians of $13,600 and $20,700, respectively. The progress was real, but the starting point for many minority families was far lower due to historical discrimination in housing, employment, and education.
Q: How did the 2016 median net worth compare to other developed nations?
In 2016, the U.S. median net worth was higher than in many European nations but reflected deeper inequality. For example, Germany’s median net worth was lower ($50,000), but wealth was more evenly distributed. Canada’s median was similar to the U.S. ($100,000), but its top 1% held a smaller share of total wealth. The U.S. stood out for its extreme concentration of wealth at the top, where the top 10% owned 71% of all liquid assets—a figure far higher than in peer nations.
Q: What policies could have accelerated wealth recovery after 2008?
Experts point to several potential interventions that could have sped up recovery:
- Direct wealth-building programs, such as baby bonds or first-time homebuyer subsidies, to help low- and middle-income families accumulate assets.
- Wage growth policies, including stronger minimum wage laws and union protections, to ensure that economic recovery translated into higher incomes.
- Student debt relief, such as income-based repayment reforms or partial loan forgiveness, to reduce the burden on younger households.
- Tax reforms that reduced inequality, such as higher marginal rates for the wealthy or closing loopholes that benefit corporations over workers.
Q: How accurate were the 2016 net worth estimates?
The Federal Reserve’s Survey of Consumer Finances is considered the gold standard for household wealth data, but it has limitations. The survey samples 6,000 households and relies on self-reported data, which can understate assets or overstate liabilities. Additionally, the data is triennial, meaning gaps exist between reports. While the median net worth 2016 figure of $97,300 is widely cited, some economists argue that underreporting of assets (like cryptocurrency or off-shore accounts) could slightly inflate the true median. However, the broad trends—stagnant wages, rising inequality, and uneven recovery—are well-supported by other data sources.
