Common Myths About Public Liability Insurance for Makeup Artists
The first myth is that public liability insurance for makeup artists is only for those working in high-stakes environments like fashion weeks or red carpets. In reality, the risk isn’t tied to prestige but to exposure. A freelance artist booking a single bridal session in a rented studio faces the same liability as one working a week-long campaign. The difference is that the latter has deeper pockets—and more claims history—to draw from. Insurance providers don’t distinguish between "serious" and "casual" work; they assess the potential for harm, which exists in every application of makeup, from theatrical to editorial. Another persistent belief is that a makeup artist’s professional indemnity (PI) policy will cover public liability claims. These are separate coverages. PI protects against claims of negligence in services (e.g., a client alleging a botched contour ruined their skin), while public liability covers third-party injuries or property damage (e.g., a client tripping over a dropped palette). Mixing the two isn’t just a mistake—it’s a gaping hole in protection. Yet many artists, especially those priced out of comprehensive policies, end up with one or the other, leaving themselves vulnerable to claims that fall through the cracks. The third myth is that public liability insurance is prohibitively expensive for freelancers. While premiums can vary wildly, the cost is often a fraction of what artists spend on high-end brushes or training courses. A basic policy for a solo makeup artist might start in the £10–£20 per month range, depending on turnover and risk factors. The real expense comes from not having it—legal fees alone can run into thousands, regardless of whether the claim is justified.Myth 1: "I Only Work with Friends and Family—So I Don’t Need It"
The assumption that personal relationships negate liability is one of the most dangerous in the industry. Even if an artist never charges for a session, the moment they use professional products or tools, they’re operating under commercial standards. A friend who develops an allergic reaction to a primer or slips on a wet palette during a home photoshoot could still pursue legal action—especially if the artist is using branded products or working in a semi-professional capacity. Courts don’t distinguish between paid and unpaid work when assessing negligence. Moreover, word-of-mouth referrals can quickly escalate into paid gigs. What starts as a favor for a cousin’s wedding might turn into a regular client base, complete with venue bookings and commercial contracts. The transition from hobbyist to professional isn’t always clear-cut, but the legal responsibilities follow the same trajectory. Insurance providers often ask about the nature of work—not just whether it’s paid—but whether it’s conducted as a business. If an artist is promoting their services on social media, accepting payments via PayPal, or using branded materials, they’re likely already operating commercially, even if informally.Myth 2: "My Landlord’s Insurance Covers Me When I Work in Salons"
This is a critical misunderstanding. A salon’s public liability policy typically covers the business itself—not the freelance artists working within it. If a client is injured by an artist’s actions (e.g., a product spill, a brush left unattended, or an allergic reaction to a product brought in by the artist), the salon’s insurance may not extend to the freelancer. In such cases, the artist could be held personally liable, and the salon’s insurer may even subrogate (pursue reimbursement) from the artist’s own policy—or lack thereof. Some salons require freelancers to sign waivers absolving them of liability, but these are rarely enforceable in court. Judges weigh the balance of power between a commercial entity and an independent contractor, often ruling in favor of the client. The safest approach is for freelancers to carry their own public liability insurance for makeup artists, regardless of where they’re working. This isn’t just about protecting the artist—it’s about ensuring that a single incident doesn’t derail a career before it begins.Myth 3: "I’ve Never Had a Problem—So I Won’t Need It"
This is the most insidious myth of all, because it’s rooted in luck rather than risk assessment. The absence of claims doesn’t mean the risk is absent—it means the artist hasn’t been tested yet. A single incident, no matter how minor, can trigger a cascade of consequences. For example, an artist using a new highlighter that causes temporary irritation might face a claim for emotional distress, even if the reaction clears within hours. The client’s perception of harm—real or imagined—is what drives legal action, not the severity of the injury. Industry anecdotes abound of artists who assumed their reputation would protect them, only to find that a disgruntled client with deep pockets could still pursue damages. In the UK, for instance, the cost of bringing a small claims case is minimal, and many clients opt for legal action as a negotiating tactic, even if they don’t intend to follow through. The stress of defending against a claim—let alone the potential financial fallout—can force an artist out of business before they ever set foot in court.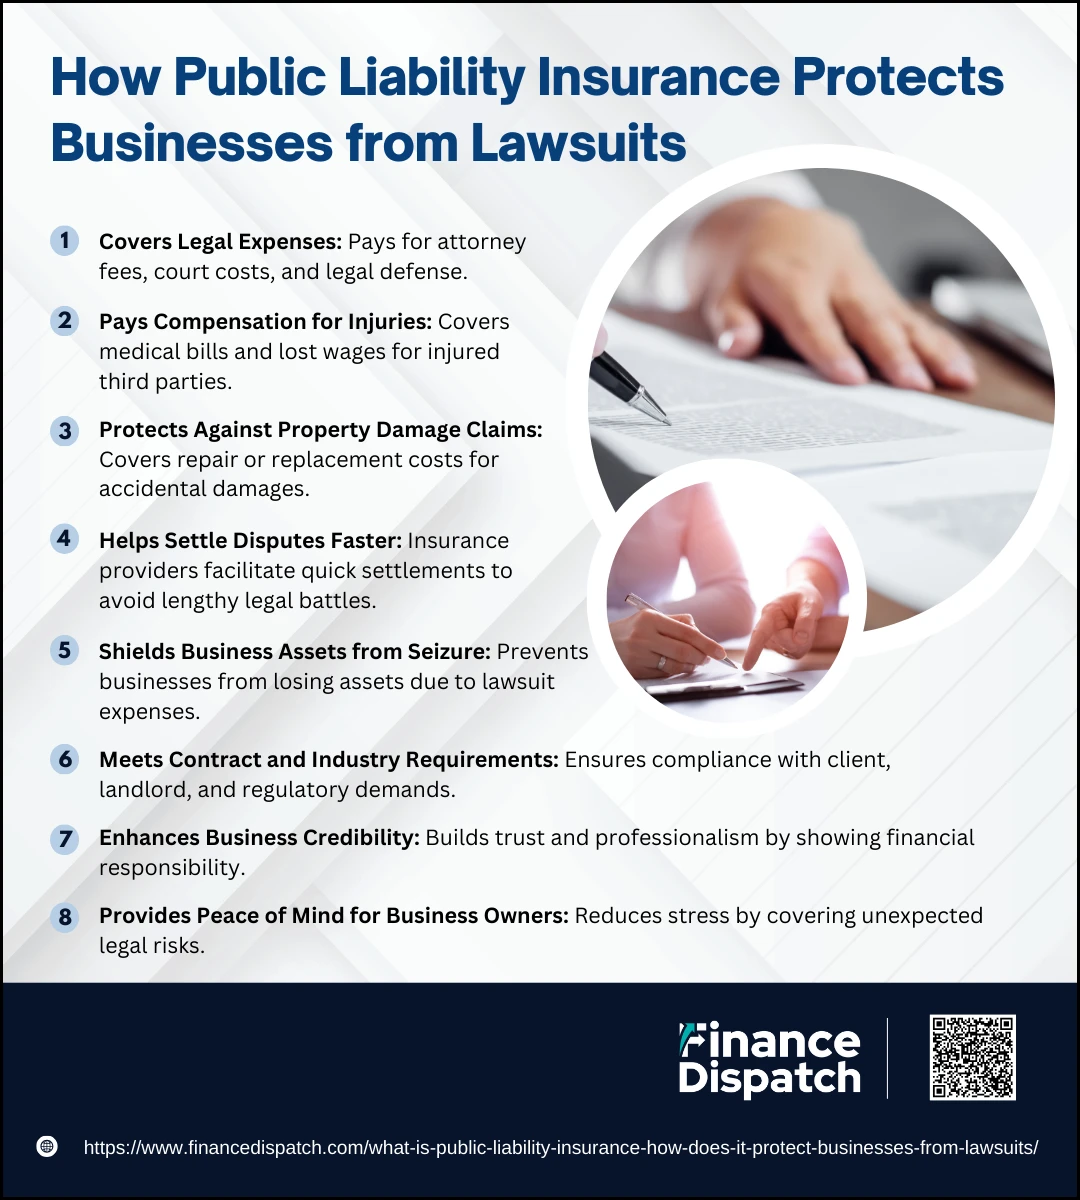
What Holds Up to Scrutiny
At its core, public liability insurance for makeup artists exists to address two fundamental legal principles: duty of care and foreseeability of harm. The moment an artist applies makeup to a client, they assume a duty to ensure their work doesn’t cause injury. This duty isn’t limited to the application itself—it extends to the products used, the environment they work in, and even the advice they give (e.g., recommending a primer without disclosing potential allergens). Courts have ruled that artists must act as a "reasonable professional" would in similar circumstances, meaning industry standards—not personal skill—determine liability. The foreseeability of harm is where most artists underestimate their exposure. A makeup artist using a spray setting mist in a poorly ventilated space could be liable if a client faints or develops respiratory issues. Similarly, an artist who fails to patch-test a client before applying a heavily pigmented eyeshadow might face claims for skin damage. These scenarios aren’t rare—they’re textbook examples of preventable harm that insurance is designed to mitigate. The key is recognizing that public liability insurance isn’t about guilt—it’s about managing the unpredictable."Liability insurance isn’t just a safety net; it’s a professional credential. Clients, venues, and even other artists will question your legitimacy if you can’t produce a policy. In an industry that thrives on trust, skipping insurance sends the wrong message." — Sarah Whitaker, insurance broker specializing in creative industries
| Common Belief | What the Evidence Says |
|---|---|
| "I only need insurance if I work with clients in public spaces." | Liability exists anywhere makeup is applied professionally, including private homes and salons. The venue doesn’t determine risk—the act of providing services does. |
| "My products are safe, so I’m not at risk." | Allergies, counterfeit products, and improper use can all lead to claims. Insurance covers the legal fallout, not the product’s safety. |
| "I can’t afford it, so I’ll take the risk." | Legal fees for defending a claim can exceed £5,000, even if the claim is dismissed. The cost of insurance is far lower than the cost of a lawsuit. |
Why the Confusion Persists
The beauty industry’s reliance on word-of-mouth recommendations and informal contracts has created a culture where legal safeguards are seen as optional. Many artists learn about insurance only after a near-miss incident—if they learn at all. Social media amplifies this confusion by glorifying the creative process while downplaying the administrative side of the business. A single Instagram post of an artist’s work might garner thousands of likes, but it won’t address the question: What happens if something goes wrong? Additionally, the insurance market itself contributes to the ambiguity. Policies vary wildly in coverage, and providers often use jargon that obscures the true extent of protection. Terms like "products liability" or "public liability" can be conflated, leading artists to assume they’re covered when they’re not. Without a clear understanding of exclusions—such as damage caused by counterfeit products or pre-existing conditions—artists may find their claims denied when they need them most.
Conclusion
Public liability insurance for makeup artists isn’t a luxury—it’s a non-negotiable part of operating professionally. The industry’s emphasis on creativity often overshadows the practical realities of liability, but the legal consequences of an uninsured incident can be career-ending. The artists who thrive are those who treat insurance as seriously as they treat their craft, recognizing that a single claim can unravel years of hard work. For those still hesitant, the solution is simple: treat insurance as a line item in every job booking. Whether it’s a £500 wedding gig or a £50 favor for a friend, the risk profile remains the same. The difference is that the insured artist walks away with their reputation—and their livelihood—intact.Comprehensive FAQs
Q: Does public liability insurance cover product-related claims if I use my own brands?
A: It depends on the policy. Standard public liability may not cover claims arising from your own products unless you’ve declared them as part of your business activities. Some insurers offer separate products liability insurance, which is essential if you sell or distribute makeup. Always disclose all product-related income to your provider to avoid claim denials.
Q: Can I add public liability coverage to an existing business insurance policy?
A: Sometimes, but it’s not guaranteed. Many business insurance policies exclude creative professionals or have sublimits for liability claims. A dedicated public liability insurance for makeup artists policy is often more comprehensive and tailored to the specific risks of the role. Consult an insurance broker who specializes in the creative industries to explore your options.
Q: What should I do if a client makes a claim against me?
A: Notify your insurer immediately, even if you believe the claim is unfounded. Provide all relevant details, including dates, products used, and witness statements. Do not admit fault or agree to settlements without legal advice. Your insurer will guide you through the claims process, which may include mediation or legal representation.
Q: Does public liability insurance cover damage to my equipment during a shoot?
A: No. Public liability covers third-party injuries or property damage (e.g., a client’s dress ruined by a spill), but not your own equipment. For that, you’ll need equipment insurance or a rider on your home insurance policy. Always clarify what’s covered before assuming a policy is comprehensive.
Q: How do I choose the right insurer for my needs?
A: Look for providers that specialize in creative industries and offer public liability insurance for makeup artists with clear coverage limits. Check reviews for claims handling speed and customer service. Avoid policies with excessive exclusions, such as those that void coverage if you work outside the UK or use unbranded products. A broker can help compare quotes and ensure you’re not overpaying for unnecessary coverage.
