Common Myths About Georgia Pacific’s Financial Standing
One persistent myth is that Georgia Pacific’s net worth is primarily tied to its consumer brands alone. The assumption goes that if you add up the value of Quilted Northern towels or Angel Soft paper, you’ve captured the company’s full worth. In reality, the bulk of its value lies in its industrial assets: pulp mills, packaging facilities, and supply chains that underpin retail giants. The consumer brands are just the visible tip of a much deeper economic iceberg. Another misconception is that Georgia Pacific’s net worth is easily comparable to its peers in the paper industry. Companies like International Paper or WestRock operate under different ownership structures and financial reporting standards, making direct comparisons misleading. What’s often overlooked is how Georgia Pacific’s integration with Koch Industries—known for its private equity strategies—shapes its financial resilience. A third myth suggests that Georgia Pacific’s net worth has stagnated in recent years. While the paper industry faces cyclical challenges, Georgia Pacific has quietly expanded through acquisitions and cost optimizations. Its ability to pivot into high-growth areas like sustainable packaging has also redefined its long-term value proposition. The company’s financial health isn’t static; it’s a dynamic interplay of market demand, regulatory shifts, and Koch Industries’ broader investment thesis.Myth 1: Georgia Pacific’s net worth is dominated by its consumer brands
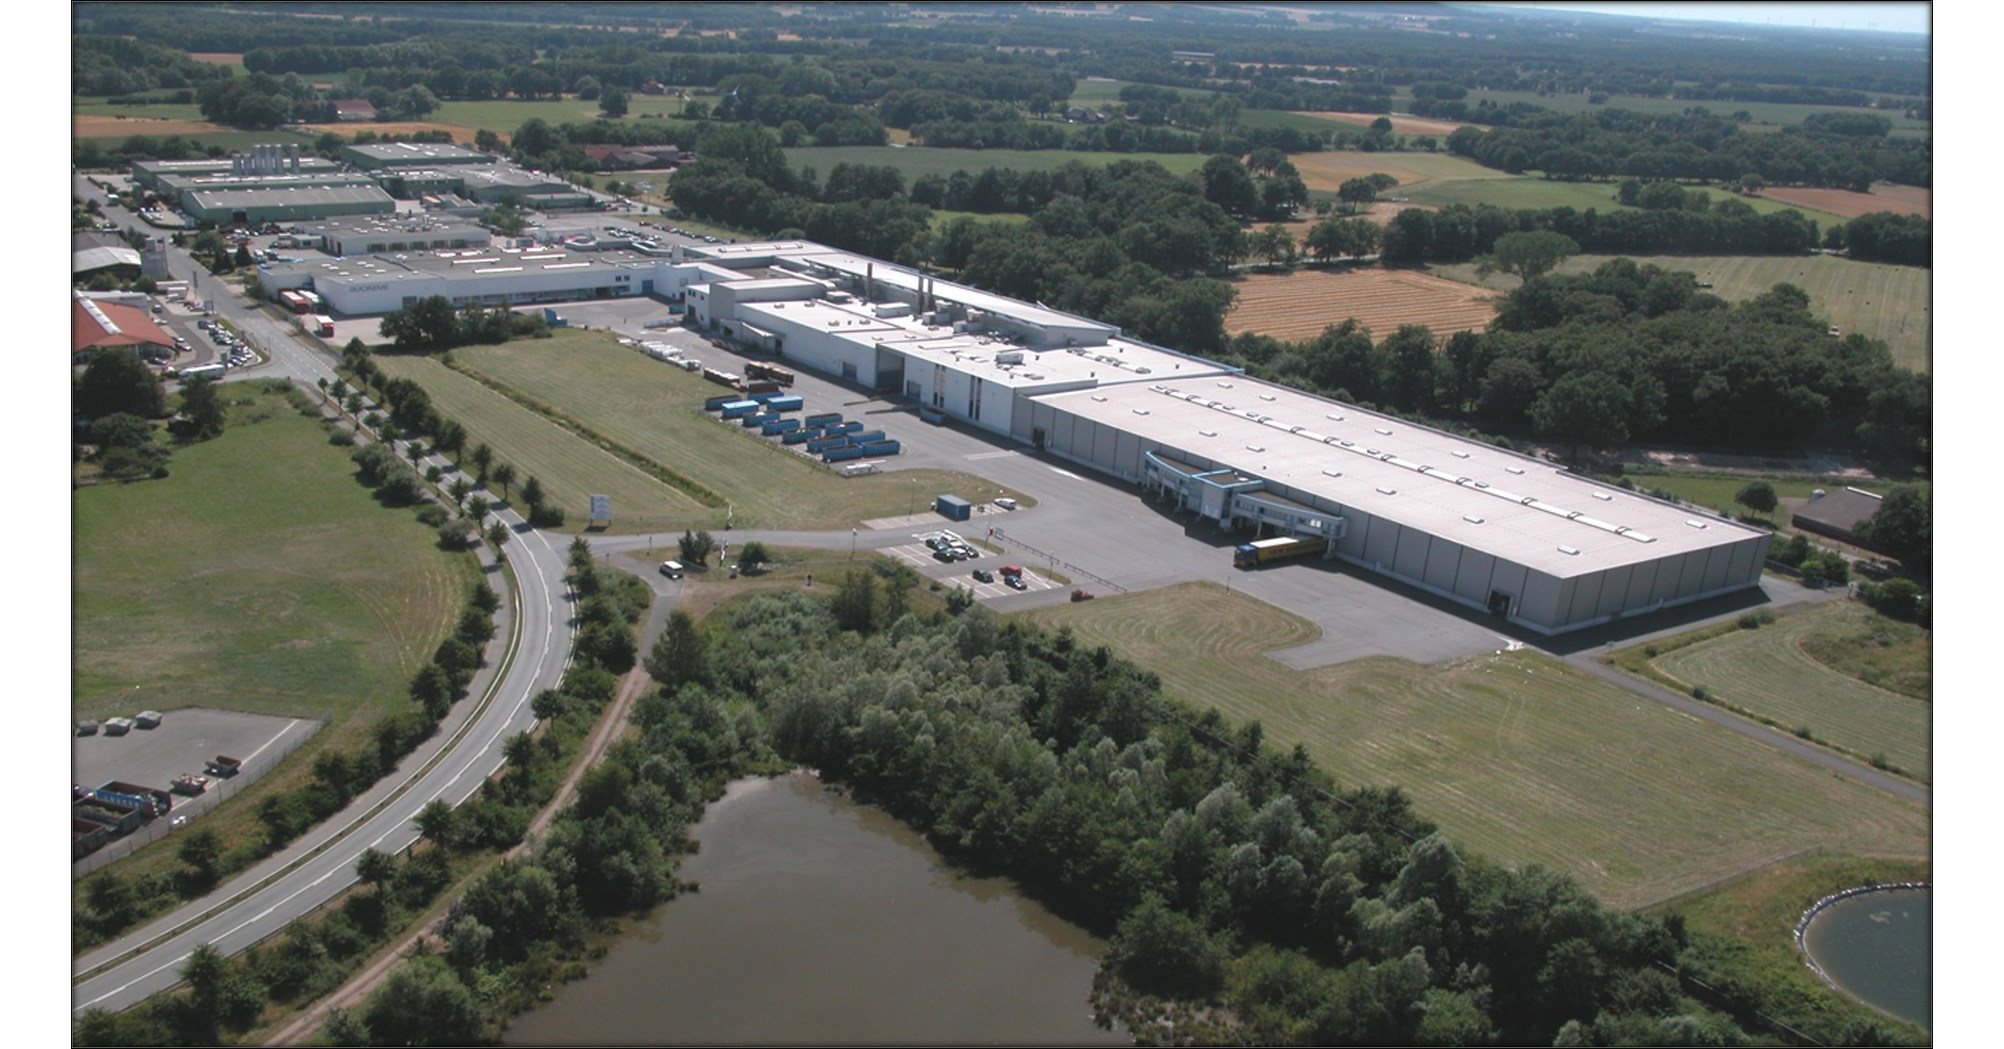
The idea that Quilted Northern or Brawny paper towels drive the majority of the company’s valuation ignores its core business: industrial pulp and packaging. While consumer brands contribute significantly to revenue—estimated to account for roughly 30% of sales—the real wealth generators are the company’s manufacturing assets. These include 200-plus facilities across North America, Europe, and Asia, producing everything from toilet paper to corrugated boxes. The value of these physical plants, coupled with their strategic locations near raw material sources, far exceeds the brand equity of its household names. For instance, a single pulp mill can represent billions in asset value, depending on capacity and market conditions. What’s often missed is how Georgia Pacific’s industrial segment benefits from long-term contracts with retailers and e-commerce platforms. These relationships lock in steady cash flows, insulating the company from short-term consumer trends. The net worth isn’t just about what’s sold on store shelves; it’s about the infrastructure that makes those products possible. Koch Industries’ ownership further complicates the picture, as private equity firms often prioritize operational efficiency over public disclosures, leaving outsiders to infer value from indirect signals like capital expenditures and debt levels.Myth 2: Georgia Pacific’s net worth is publicly disclosed in its financial reports
Unlike publicly traded companies, Georgia Pacific doesn’t publish a net worth figure in the traditional sense. As a subsidiary of Koch Industries—a privately held conglomerate—its financials are consolidated within Koch’s broader operations. This lack of transparency forces analysts to rely on proxies: revenue estimates, asset valuations from industry reports, and occasional hints in Koch’s filings. For example, Georgia Pacific’s revenue has been reported to hover around $10 billion annually, but net worth calculations require assumptions about debt, equity, and intangible assets. Even then, Koch’s structure means Georgia Pacific’s performance is often lumped together with other divisions, obscuring its standalone worth. The closest public approximations come from third-party valuations, such as those by PitchBook or Bloomberg, which estimate Georgia Pacific’s enterprise value at between $15 billion and $20 billion. These figures are educated guesses, not audited numbers. Koch Industries’ refusal to break out Georgia Pacific’s finances entirely stems from strategic reasons: private equity firms often avoid disclosing granular details to competitors or potential acquirers. This opacity isn’t negligence; it’s a deliberate choice to control narrative and leverage.Myth 3: Georgia Pacific’s net worth has declined due to the paper industry’s struggles
The paper industry has faced headwinds in recent decades—rising raw material costs, competition from digital alternatives, and environmental regulations—but Georgia Pacific has mitigated these risks through diversification. Its foray into sustainable packaging, for example, aligns with global retail trends favoring eco-friendly materials. This shift hasn’t just preserved value; it’s created new growth vectors. Additionally, Georgia Pacific’s cost-cutting measures, such as automation in mills and supply chain optimizations, have improved margins. While the company may not dominate headlines like tech giants, its financial engineering has kept it competitive. Industry analysts note that Georgia Pacific’s net worth isn’t in freefall; it’s evolving. The company’s ability to adapt—whether through acquisitions like the 2015 purchase of Verso Corporation or investments in alternative fibers—demonstrates resilience. Koch Industries’ backing further stabilizes its position, as the parent company’s deep pockets allow for long-term plays that publicly traded peers might avoid. The perception of decline ignores these strategic moves.
What Holds Up to Scrutiny
At its core, what is Georgia Pacific’s net worth boils down to three verifiable pillars: its industrial assets, its revenue streams, and its integration with Koch Industries. The company’s pulp mills, for instance, are valued not just for production but for their strategic locations near timber resources or waterways—critical for cost efficiency. Revenue estimates, while not precise, provide a baseline: Georgia Pacific’s sales have consistently ranged in the $9 billion to $11 billion bracket, with profitability tied to its ability to pass through input costs to customers. Koch Industries’ ownership adds another layer, as the parent’s private equity model allows for reinvestment without shareholder pressure to maximize quarterly earnings. The most reliable data points come from Georgia Pacific’s own disclosures, such as its 2022 sustainability report, which highlighted $1.5 billion in capital expenditures—a figure that reflects its ongoing commitment to expansion. Industry reports also suggest that Georgia Pacific’s enterprise value, when estimated, falls into a $15 billion to $20 billion range, though these are rough approximations. The key takeaway is that Georgia Pacific’s net worth isn’t a fixed number; it’s a moving target shaped by market conditions, regulatory changes, and Koch’s long-term vision.“Georgia Pacific’s strength lies in its ability to operate as a quiet giant—unnoticed by the public but indispensable to the supply chains it serves.” — Industry analyst, 2023
| Common Belief | What the Evidence Says |
|---|---|
| Georgia Pacific’s net worth is primarily tied to its consumer brands. | Industrial assets (pulp mills, packaging) account for the majority of its value. |
| Its net worth is publicly disclosed. | No standalone figure exists; estimates rely on proxies like revenue and asset valuations. |
| The company’s net worth has declined. | Strategic acquisitions and cost controls have preserved and grown its value. |
| It’s comparable to WestRock or International Paper. | Ownership structure and reporting differences make direct comparisons unreliable. |
Why the Confusion Persists
The ambiguity around Georgia Pacific’s net worth stems from two primary factors: its private ownership and the nature of the paper industry itself. Koch Industries’ decision to keep Georgia Pacific under the radar limits transparency, a common trait among private equity-backed firms. Without quarterly earnings calls or detailed filings, outsiders must piece together information from fragmented sources—press releases, industry publications, and occasional leaks. This lack of clarity invites speculation, as analysts fill gaps with educated guesses rather than hard data. The paper industry’s cyclical nature also fuels confusion. When commodity prices spike or demand softens, perceptions of Georgia Pacific’s financial health fluctuate wildly. A downturn in one segment (e.g., consumer paper) doesn’t necessarily translate to a decline in net worth, given the company’s diversified portfolio. Yet, without a clear benchmark, the public and even some investors struggle to distinguish between short-term volatility and long-term stability. The result? A persistent narrative of uncertainty, where what is Georgia Pacific’s net worth becomes less a question of facts and more a matter of interpretation.
Conclusion
Georgia Pacific’s net worth is a study in contrasts: a company that touches millions of lives daily yet remains financially enigmatic. Its true value lies not in flashy headlines but in the quiet efficiency of its operations, the resilience of its supply chains, and the strategic foresight of its parent company. While exact figures may never be publicly confirmed, the available evidence paints a picture of a well-managed enterprise with significant hidden assets. For stakeholders—whether suppliers, employees, or regulators—the challenge isn’t uncovering a single number but understanding the forces that shape it. The lesson here is that Georgia Pacific’s net worth isn’t just a balance sheet entry; it’s a reflection of an industry in transition. As sustainability demands reshape packaging and digital alternatives redefine paper use, Georgia Pacific’s ability to adapt will determine its future trajectory. For now, the most accurate answer to the question isn’t a precise dollar figure but a recognition of its enduring relevance in an era of corporate opacity.Comprehensive FAQs
Q: Is Georgia Pacific a publicly traded company?
A: No. Georgia Pacific is a subsidiary of Koch Industries, a privately held conglomerate. This means its financials aren’t subject to public disclosure requirements like those of publicly traded companies.
Q: How does Georgia Pacific’s net worth compare to WestRock or International Paper?
A: Direct comparisons are difficult due to differences in ownership structures and reporting standards. WestRock and International Paper are publicly traded, while Georgia Pacific’s value is inferred from Koch Industries’ consolidated data. Industry estimates suggest Georgia Pacific’s enterprise value may be in the $15 billion to $20 billion range, but this is speculative.
Q: What are Georgia Pacific’s primary revenue sources?
A: The company’s revenue streams include consumer brands (e.g., Quilted Northern, Brawny), industrial pulp and paper, packaging solutions, and tissue products. Industrial segments—particularly pulp and packaging—are considered the backbone of its financial stability.
Q: Has Georgia Pacific’s net worth been affected by recent industry downturns?
A: The paper industry has faced challenges, but Georgia Pacific has mitigated risks through cost controls, acquisitions (e.g., Verso Corporation), and investments in sustainable packaging. Koch Industries’ backing has also provided financial flexibility during downturns.
Q: Where can I find official financial statements for Georgia Pacific?
A: Georgia Pacific doesn’t publish standalone financial statements. Koch Industries occasionally references its subsidiaries in broader filings, such as tax disclosures or sustainability reports. Third-party sources like PitchBook or Bloomberg offer estimates based on industry data.
Q: Why doesn’t Koch Industries disclose Georgia Pacific’s exact net worth?
A: Private equity firms like Koch Industries often limit disclosures to maintain competitive advantages, avoid regulatory scrutiny, and control narrative. Transparency isn’t a priority when the focus is on long-term operational strategy rather than public market performance.
Q: Are there rumors of Georgia Pacific being sold or spun off?
A: Speculation about Koch Industries divesting assets is common, but no credible rumors have surfaced regarding Georgia Pacific specifically. Koch’s strategy has historically favored holding onto core businesses for decades, not rapid turnover.
