6 Things Worth Knowing About JP Morgan Chase’s Financial Dominance
The JP Morgan Chasec net worth isn’t a single figure but a constellation of interconnected data points. What follows are six critical dimensions that define its economic gravity.1. A Trillion-Dollar Asset Base That Outweighs Most Countries
As of recent filings, JP Morgan Chase’s total assets hover around $3.5 trillion, a sum larger than the GDP of all but a handful of nations. This isn’t idle capital—it’s the fuel for its lending operations, investment banking, and trading desks. The bank’s ability to deploy this firepower explains why it secures trillions in deposits annually, often at rates that smaller institutions can’t match. Even during crises, like the 2008 financial collapse or the COVID-19 pandemic, its asset base remained a bulwark, absorbing shocks while competitors faltered. The scale becomes clearer when juxtaposed with peers. While Bank of America or Citigroup also boast multi-trillion-dollar balances, JP Morgan’s asset-to-equity ratio—a measure of leverage—is among the most aggressive in the industry. This means it wields outsized influence relative to its own capital, a strategy that amplifies returns but also exposes it to systemic risk. Regulators watch this ratio closely, but the bank’s size often insulates it from the kind of penalties that could cripple smaller players.2. Market Capitalization: A Barometer of Investor Confidence
The JP Morgan Chasec net worth as reflected in its stock price is another story. With a market cap frequently exceeding $400 billion, the bank’s valuation fluctuates with macroeconomic trends, interest rate expectations, and even the whims of algorithmic traders. Unlike private wealth, this figure is liquid—shares can be bought or sold in seconds, making the bank’s worth a real-time referendum on global stability. When markets panic, JP Morgan’s stock often holds up better than peers’, a testament to its perceived resilience. Yet the market cap tells only part of the story. The bank’s tangible net worth—assets minus liabilities—is far larger, thanks to its ability to borrow cheaply and its dominance in high-margin businesses like wealth management and asset servicing. This disconnect between market valuation and book value is a hallmark of financial institutions: investors pay a premium for stability, even if the underlying assets aren’t trading at par.3. The Wealth Management Empire: Private Banking for the Ultra-Rich
JP Morgan’s private bank—one of the largest in the world—manages assets totaling over $3 trillion for high-net-worth individuals and institutions. This isn’t just a profit center; it’s a moat. The bank’s ability to attract and retain clients like sovereign wealth funds, hedge funds, and billionaires creates a feedback loop: the more wealth it manages, the more deposits it attracts, the more it can lend, and the cycle repeats. Competitors like Goldman Sachs or Morgan Stanley struggle to replicate this scale, leaving JP Morgan with an insurmountable lead. The private bank’s success hinges on exclusivity. Clients don’t just get investment advice—they get access to deals, research, and even political influence. This embedded wealth isn’t reflected in quarterly earnings but in the bank’s long-term stickiness. When a family office or endowment chooses JP Morgan over a rival, it’s not just a transaction; it’s a decades-long relationship that compounds the bank’s net worth in ways no balance sheet can capture.4. Trading and Investment Banking: The Engine of Hidden Profits
While retail banking grabs headlines, JP Morgan’s trading and investment banking divisions generate the lion’s share of its revenue—over $40 billion annually in recent years. These units don’t just facilitate deals; they create liquidity, profit from market movements, and dominate niches like derivatives trading and corporate lending. The bank’s proprietary trading operations, for instance, have historically delivered returns that dwarf traditional lending, though they also invite scrutiny from regulators wary of excessive risk-taking. A lesser-known but critical aspect is JP Morgan’s role as a market maker. When other banks hesitate to underwrite debt or take inventory risk, JP Morgan steps in, ensuring markets remain functional. This utility isn’t just a service—it’s a wealth multiplier. The more the bank trades, the more it earns in commissions, fees, and spreads, all of which inflate its net worth in ways that evade traditional accounting.5. Regulatory Arbitrage: How Exemptions Boost the Bottom Line
The JP Morgan Chasec net worth benefits from a legal advantage most corporations can’t replicate: regulatory exemptions. As a systemically important financial institution (SIFI), the bank operates under a different set of rules than regional banks. It can borrow at lower rates, take on more leverage, and even fail with less scrutiny—because its collapse would trigger a global meltdown. This implicit subsidy isn’t charity; it’s the price of stability, and JP Morgan has mastered the art of extracting value from it. Consider the Volcker Rule, which restricts proprietary trading. While competitors scrambled to comply, JP Morgan found loopholes, rebranding certain activities as "market-making" rather than speculative betting. The result? A net worth that grows not just from organic growth but from the ability to operate in a legal gray zone where others dare not tread."JP Morgan doesn’t just play by the rules—it writes them, or at least interprets them in ways that maximize its advantage. The rest of us are left playing catch-up." — Former U.S. Treasury official, speaking off-record to financial journalists in 2022.
6. The Global Reach: A Bank That Outsizes Nations
With operations in 100+ countries, JP Morgan Chase’s net worth isn’t confined to U.S. borders. Its London arm is the largest American bank in Europe, its Asian desks dominate emerging-market finance, and its Hong Kong and Singapore hubs serve as gateways to China’s capital flows. This global footprint isn’t just about geography—it’s about currency dominance. The bank processes more dollars, euros, and yen than any other institution, giving it unparalleled influence over cross-border transactions. The implications are geopolitical. When central banks move, JP Morgan moves first. Its traders anticipate policy shifts before they’re announced, its lenders fund sovereign debt before ratings agencies act, and its wealth managers advise governments on fiscal strategy. This soft power—the ability to shape financial narratives—is as valuable as its hard assets. In an era of sanctions, currency wars, and deglobalization, a bank that controls these flows doesn’t just have wealth; it dictates the rules of the game.
How These Facts Connect
The JP Morgan Chasec net worth isn’t a static number but a dynamic ecosystem. Its asset base funds its trading operations, which in turn attract wealthy clients, whose deposits reinforce its regulatory advantages, which then allow it to expand globally. Each component feeds into the next, creating a virtuous cycle that few competitors can disrupt. The bank’s size isn’t just a byproduct of success—it’s a self-perpetuating mechanism, where scale begets more scale. Yet this interconnectedness also exposes vulnerabilities. A single misstep—like the 2012 "London Whale" trading debacle or the 2020 COVID-19 market crash—can ripple through the system. The bank’s net worth is only as strong as its risk management, and even minor errors can cost billions. This tension between dominance and fragility is the defining paradox of modern finance: the institutions that save us from chaos are often the same ones that create it.| Dimension | Key Statistic | Strategic Impact |
|---|---|---|
| Total Assets | $3.5 trillion+ | Leverage to deploy capital globally; deposit magnet for institutions. |
| Market Cap | $400B+ | Reflects investor confidence in crisis resilience; liquidity for acquisitions. |
| Private Banking AUM | $3T+ | Sticky client relationships; recurring revenue from fees and investments. |
Conclusion
The JP Morgan Chasec net worth isn’t just a balance-sheet figure—it’s a geopolitical force. Its wealth isn’t measured in private jets or yachts but in the trillions of dollars it moves, the markets it influences, and the policies it subtly shapes. Understanding this scale requires looking beyond quarterly earnings to the systemic role the bank plays: as a lender of last resort, a trader of first resort, and a wealth manager for the global elite. For critics, this dominance raises questions about accountability. For competitors, it’s a warning: the gap between JP Morgan and the rest of Wall Street isn’t closing. And for the public, it’s a reminder that in an era of inequality, some institutions don’t just accumulate wealth—they reshape the economy itself.Comprehensive FAQs
Q: How does JP Morgan Chase’s net worth compare to other megabanks?
JP Morgan Chase consistently ranks as the largest U.S. bank by assets, surpassing peers like Bank of America and Citigroup. While all three operate at a similar scale, JP Morgan’s trading revenue and private banking dominance give it a structural edge. For example, its investment banking division often leads global deal volumes, and its wealth management arm manages more assets than any other U.S. bank.
Q: Is JP Morgan Chase’s net worth public knowledge?
Not in a single figure. The bank reports assets, liabilities, and equity in filings, but its true economic value—including intangibles like client relationships and regulatory advantages—isn’t fully quantifiable. Analysts estimate its tangible net worth (assets minus liabilities) at hundreds of billions, but this excludes proprietary advantages like market-making dominance or political influence.
Q: How does JP Morgan Chase make most of its money?
The bank’s revenue streams are diverse but revolve around four pillars: net interest income (from lending), investment banking fees (M&A, underwriting), trading profits (proprietary and client-driven), and wealth management fees. In recent years, trading and investment banking have accounted for nearly 40% of total revenue, making them the most volatile but highest-margin businesses.
Q: Has JP Morgan Chase’s net worth grown or shrunk in recent years?
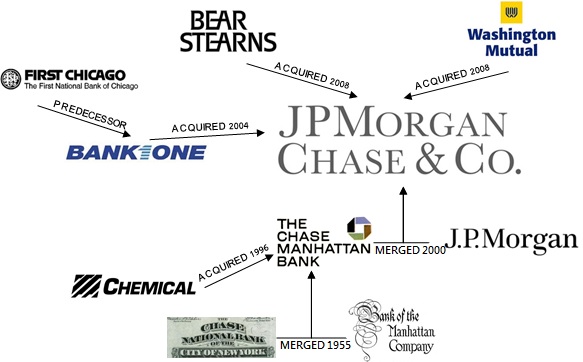
Like most large banks, its asset base has fluctuated with economic cycles. Post-2008, it expanded aggressively through acquisitions (e.g., Bear Stearns, Washington Mutual). During the COVID-19 pandemic, its market capitalization dipped as rates fell, but its asset growth remained robust due to strong deposit inflows. Long-term trends show steady growth, though regulatory pressures and competition from fintechs pose incremental risks.
Q: Does JP Morgan Chase pay taxes on its global wealth?
The bank operates under a complex tax structure. As a U.S. corporation, it pays federal and state taxes on domestic profits, but its foreign subsidiaries often benefit from territorial tax systems (e.g., Ireland’s low corporate rates). JP Morgan has faced scrutiny over tax inversion strategies in the past, though recent reforms have limited such maneuvers. Overall, its effective tax rate typically hovers around 20-25%, lower than the nominal U.S. corporate rate due to deductions and credits.
Q: Could JP Morgan Chase ever fail?
While no institution is immune to collapse, JP Morgan’s size and systemic importance make a failure unlikely without a catastrophic global crisis. The bank’s liquidity coverage ratio (a stress-test metric) is among the highest in the industry, and its government backstop (via the Federal Reserve) ensures it’s treated as "too big to fail." That said, a prolonged downturn—combined with mismanagement or a trading disaster—could still strain its balance sheet, though regulators would intervene before a collapse occurred.
Q: How does JP Morgan Chase’s wealth compare to that of the richest individuals?
The JP Morgan Chasec net worth (in the trillions) dwarfs even the combined fortunes of the world’s richest individuals. For context, the total net worth of all U.S. billionaires (as of recent estimates) is less than JP Morgan’s asset base. While figures like Elon Musk or Jeff Bezos are household names, their wealth is personal and illiquid; JP Morgan’s is institutional and operational, giving it a different kind of power—one that moves markets, not just portfolios.
