5 Things Worth Knowing About Doterra’s Financial Trajectory
The doterra annual revenue narrative is layered with contradictions. On one hand, the company’s growth has been meteoric, fueled by a cult-like following among distributors and consumers alike. On the other, its financial disclosures are fragmented, relying on indirect data points that require careful interpretation. Here are five key facts that contextualize its economic footprint—and the forces shaping it.1. Private Company, Public Speculation: Why Exact Figures Are a Moving Target
Doterra’s refusal to release audited annual revenue figures creates a paradox: the company is both highly profitable and deliberately opaque. While competitors like Young Living (its largest rival) disclose revenue through SEC filings, Doterra’s parent, YL Holdings, operates under a different legal structure. Industry estimates place doterra annual revenue in the $3–5 billion range for recent years, though these are educated guesses based on distributor earnings reports, wholesale data, and comparisons to similar MLM brands. The lack of transparency isn’t just about secrecy—it’s a strategic move to shield the company from scrutiny over its compensation plan, which has drawn criticism for its reliance on distributor recruitment over product sales. The opacity extends to Doterra’s valuation. In 2021, reports suggested a potential sale or private equity interest could value the company at $10 billion or more, though no deal materialized. Without a public IPO or acquisition, the true scale of doterra annual revenue remains a subject of debate among analysts and former executives. What’s clear is that the company’s growth has outpaced traditional retail models, proving that direct-selling can thrive even in a digital-first marketplace.2. The Distributor Economy: How 90% of Revenue Comes from Independent Sellers
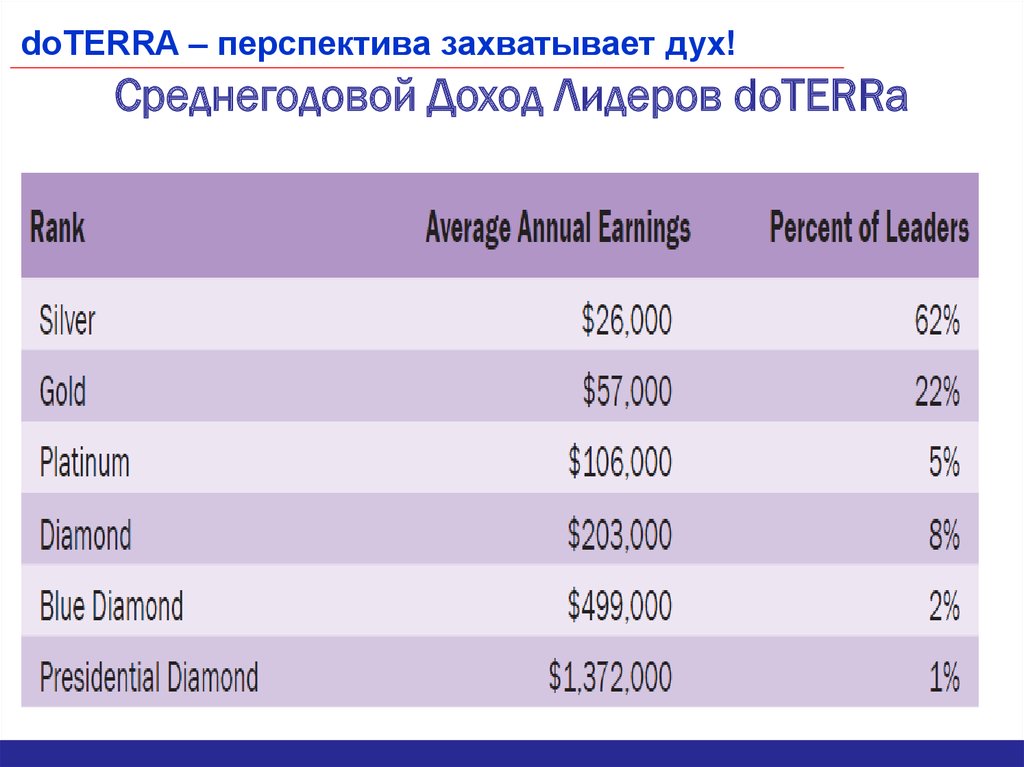
The backbone of Doterra’s financial model is its 1.5 million-plus independent distributors, who generate over 90% of its revenue. This reliance on a decentralized sales force is both its greatest strength and vulnerability. When distributors earn commissions—often tied to their own sales and those of their downline—the company benefits from a self-sustaining network effect. However, this structure has led to allegations of pyramid scheme dynamics, where recruitment incentives overshadow actual product demand. A 2022 analysis by the Wall Street Journal estimated that doterra annual revenue could exceed $4 billion if distributor activity remained steady, but the sustainability of this model hinges on continuous recruitment. The company’s response? Aggressive training programs, leadership incentives, and a heavy emphasis on "lifestyle branding" that blurs the line between personal income and corporate growth. Critics argue that the doterra annual revenue figures mask a system where only the top 1% of distributors earn significant income, while the majority struggle to break even.3. The Young Living Showdown: A Rivalry That Reshaped the Market
Doterra’s rise to prominence was fueled in part by its rivalry with Young Living, the MLM giant that dominated the essential oils market for decades. While Young Living’s doterra annual revenue equivalent (reportedly $1.5–2 billion in recent years) is publicly disclosed, the competition between the two companies has driven innovation—and regulatory pushback. Both firms have faced lawsuits over deceptive practices, with Doterra settling a $15 million FTC case in 2019 for misrepresenting the earnings potential of its distributors. The rivalry also highlights a key difference: Young Living’s revenue is more evenly distributed across wholesale and retail channels, while Doterra’s doterra annual revenue is almost entirely dependent on its distributor network. This distinction has made Doterra’s business model more volatile, as it’s directly tied to the whims of individual sellers’ motivations. Yet, the company’s aggressive marketing—including celebrity endorsements and influencer partnerships—has kept its revenue stream robust, even as consumer trust in MLMs wanes.4. The Regulatory Tightrope: How Scrutiny Could Reshape Future Revenue
Doterra’s financial future may hinge on its ability to navigate an increasingly hostile regulatory landscape. The doterra annual revenue growth story has been accompanied by a series of legal challenges, from state-level MLM bans (like California’s 2020 restrictions) to federal investigations into its compensation structure. In 2023, the FTC launched a probe into whether Doterra’s earnings claims violated consumer protection laws, a move that could force the company to restructure its payout model—or face fines that eat into its doterra annual revenue. The regulatory risk isn’t just legal; it’s reputational. As millennial and Gen Z consumers grow skeptical of MLMs, Doterra’s ability to maintain its distributor base—and thus its revenue—could be tested. The company has responded by shifting its marketing toward "wellness entrepreneurship," framing distributorship as a side hustle rather than a get-rich-quick scheme. Whether this pivot will sustain doterra annual revenue in the long term remains an open question.5. The Sustainability Paradox: Can a $4B+ Business Stay "Small-Batch"?
One of Doterra’s most enduring marketing strategies is its emphasis on small-batch, farm-fresh essential oils—a narrative that contrasts sharply with its industrial-scale revenue. Yet, as doterra annual revenue has ballooned, so too has the company’s production capacity. Internal documents leaked in 2021 revealed that Doterra sources oils from over 100 countries, with some suppliers operating at near-capacity to meet demand. The tension between its "artisanal" branding and its multibillion-dollar supply chain has led to accusations of greenwashing. The sustainability of this model is further complicated by the company’s carbon footprint. Shipping essential oils globally—especially in the small bottles favored by distributors—contributes to emissions that undermine its "natural living" ethos. While Doterra has launched initiatives like carbon-neutral shipping, these efforts are dwarfed by the sheer scale of its doterra annual revenue operations. The challenge for the company is balancing growth with authenticity—a test that will define its next decade.
How These Facts Connect
Doterra’s financial story is less about static numbers and more about the forces that propel and constrain them. The doterra annual revenue figures, while elusive, tell a tale of a company that has successfully monetized trust—both in its products and in its promise of financial freedom. The reliance on distributors isn’t just a business model; it’s a cultural phenomenon, where personal relationships drive sales and corporate growth. Yet, this same model has made Doterra vulnerable to regulatory backlash and shifting consumer priorities. The rivalry with Young Living underscores another truth: in the MLM space, growth often comes at the expense of transparency. Doterra’s refusal to disclose exact doterra annual revenue totals isn’t just about secrecy—it’s a reflection of a business built on the idea that the numbers don’t matter as much as the network. But as the company scales, the cracks in this narrative are becoming harder to ignore. The regulatory challenges, the sustainability paradox, and the distributor economy’s inherent instability all point to a future where Doterra’s financial trajectory will be shaped as much by external pressures as by its own ambition.| Key Factor | Impact on Revenue | Risks |
|---|---|---|
| Distributor Network (90%+ of revenue) | Drives explosive growth through viral recruitment | Regulatory scrutiny over pyramid-like structure |
| Rivalry with Young Living | Accelerates innovation and market share gains | Legal battles and consumer skepticism toward MLMs |
| Branding vs. Scale ("Small-Batch" vs. $4B+ revenue) | Maintains premium pricing and customer loyalty | Greenwashing accusations and supply chain sustainability issues |
Conclusion
Doterra’s doterra annual revenue is more than a financial metric; it’s a reflection of the broader tensions in the wellness industry. The company’s ability to grow while maintaining its cult-like following is a testament to its marketing prowess, but it also exposes the fragility of a business model that depends on endless recruitment. As regulators tighten their grip and consumers grow more discerning, Doterra’s financial future will depend on its ability to adapt—whether that means embracing transparency, restructuring its compensation plan, or doubling down on its "lifestyle brand" identity. One thing is certain: the numbers behind doterra annual revenue will continue to be a flashpoint in the debate over MLMs, corporate accountability, and the ethics of direct-selling. For now, the company remains a financial enigma—a privately held giant whose true scale is known only to a select few. But the story of its revenue isn’t just about dollars and cents; it’s about the people who power it, the laws that challenge it, and the consumers who either champion or question its place in the modern economy.Comprehensive FAQs
Q: Does Doterra disclose its exact annual revenue?
A: No. As a privately held company, Doterra does not release audited annual revenue figures. Industry estimates, based on distributor earnings data and comparisons to competitors like Young Living, suggest doterra annual revenue falls in the $3–5 billion range, but these are not verified totals. The company’s parent, YL Holdings, also operates under a structure that avoids public disclosures.
Q: How does Doterra’s revenue compare to Young Living’s?
A: Young Living, Doterra’s largest rival, discloses its revenue through SEC filings, reporting figures around $1.5–2 billion annually in recent years. While Doterra’s doterra annual revenue is estimated to be 2–3 times higher, the two companies operate in a highly competitive space where growth is driven by distributor recruitment rather than traditional retail expansion.
Q: What percentage of Doterra’s revenue comes from product sales vs. recruitment?
A: Over 90% of Doterra’s revenue is generated through its independent distributor network, where commissions are tied to both personal sales and the recruitment of new sellers. This structure has led to criticism that the company’s doterra annual revenue growth is more dependent on network expansion than actual product demand, a dynamic that mirrors other MLM models.
Q: Has Doterra faced legal consequences over its revenue or earnings claims?
A: Yes. In 2019, Doterra settled an FTC case for $15 million, accused of making deceptive earnings claims to potential distributors. The case highlighted broader concerns about how MLMs structure their doterra annual revenue models to prioritize recruitment over sustainable sales. Additional lawsuits in states like California have targeted the industry’s compensation practices, raising questions about the long-term viability of Doterra’s growth strategy.
Q: How does Doterra’s revenue model differ from traditional retail brands?
A: Unlike traditional retail brands that rely on wholesale distribution and brick-and-mortar sales, Doterra’s doterra annual revenue is almost entirely driven by a direct-selling network. This model eliminates middlemen but shifts risk onto independent distributors, who must constantly recruit to maintain income. The result is a highly scalable but volatile revenue stream that can fluctuate based on distributor activity rather than market demand.
Q: What are the biggest threats to Doterra’s future revenue growth?
A: The primary threats include regulatory crackdowns on MLM compensation structures, declining consumer trust in direct-selling models, and the sustainability of its distributor base. As millennial and Gen Z consumers grow skeptical of MLMs, Doterra’s ability to retain distributors—and thus sustain its doterra annual revenue—will be critical. Additionally, the company’s "small-batch" branding may face scrutiny as its production scale increases to meet demand.
Q: Could Doterra go public or be acquired in the near future?
A: Speculation about a potential IPO or acquisition has persisted, with reports in 2021 suggesting a valuation of $10 billion or more if sold. However, no concrete moves have materialized. Given the regulatory risks and the company’s reliance on its distributor network, a public offering could expose doterra annual revenue details that the company currently keeps private. For now, Doterra appears content to remain privately held, allowing it to control its narrative—and its numbers.
