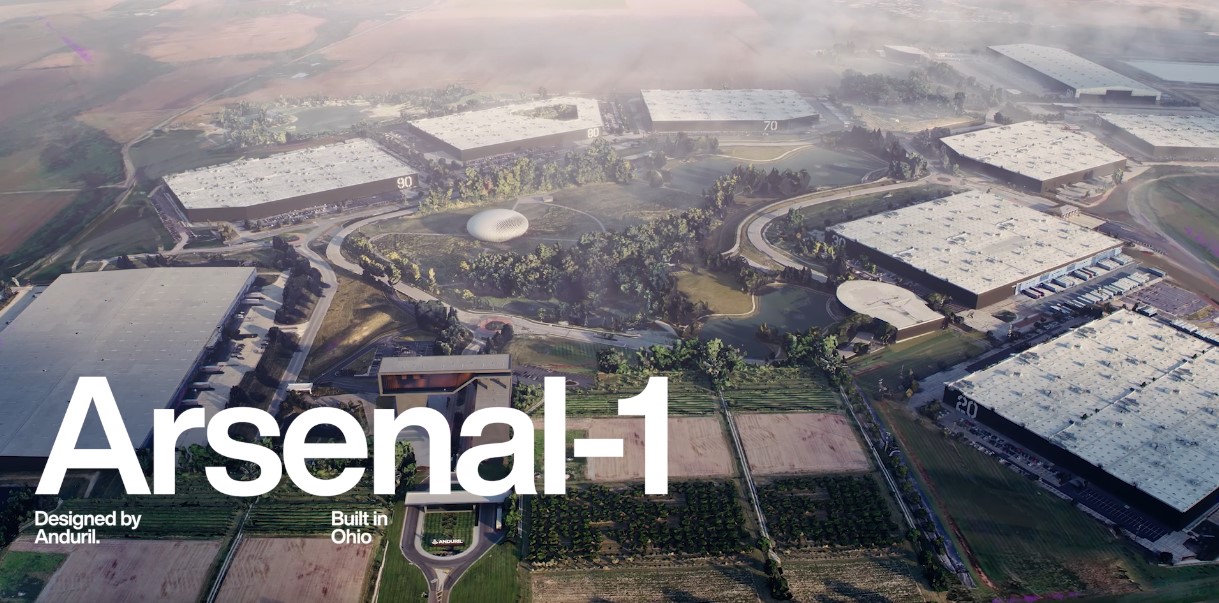
7 Things Worth Knowing About Anduril Industries Worth
The conversation around Anduril’s financial standing often collapses into two extremes: either it’s an overhyped startup with no path to profitability, or an unstoppable force poised to dismantle the entire defense industry. Both narratives ignore the company’s deliberate strategy—one that treats valuation as a tool, not an endpoint. Below are the seven pillars supporting (or undermining) the claims about Anduril industries worth, from its funding origins to its contractual leverage.1. The Funding Flywheel: How Anduril Turned $100M into a Pentagon Darling
Anduril’s early years were defined by the kind of venture capital alchemy that rarely works in defense. In 2018, it raised a $100 million Series A—a sum that would be modest for a biotech firm, but staggering for a company whose product was, essentially, "smart bombs with better software." The backers weren’t just Silicon Valley’s usual suspects; they included Andreas von Bechtolsheim, the "Father of Silicon Valley," and Peter Thiel’s Founders Fund, both of whom saw in Anduril a chance to export their risk-taking culture into a sector notorious for its conservatism. The real inflection point came in 2020, when Anduril pivoted from selling individual systems (like its Lattice drone) to offering modular, AI-driven "mission sets"—bundles of sensors, drones, and analytics that could be deployed as a single package. This shift mirrored the way AWS sells cloud services: instead of licensing a single product, customers bought access to a platform. The Pentagon, desperate for agility after two decades of war, took notice. By 2022, Anduril’s contract value had ballooned to $1.4 billion in backlog, with no signs of slowing. The funding wasn’t just fueling growth; it was rewriting the rules of engagement for defense procurement.2. The Pentagon’s Love Affair: Why Anduril’s Worth Matters to Uncle Sam
The U.S. military’s relationship with Anduril isn’t just transactional—it’s transformative. Where traditional defense contractors like Boeing or Northrop Grumman win contracts by proving they can build a fighter jet or a missile, Anduril wins by selling speed. Its Other Transaction Authority (OTA) agreements—a Pentagon program designed to fast-track innovation—allow it to bypass the red tape that strangles legacy firms. In 2023, Anduril became the first company to secure a multi-year OTA deal worth over $500 million, a figure that dwarfs the typical startup’s lifetime revenue. What makes this arrangement mutually beneficial is Anduril’s ability to adapt contracts in real time. While a traditional defense firm might take years to modify a system, Anduril’s software-first approach lets it push updates remotely. The military’s appetite for this model is clear: in 2024, Anduril was awarded a $300 million contract for its "Ghost" drone swarm technology, part of a broader push to replace aging MQ-1 Predators with AI-coordinated fleets. The Anduril industries worth in this context isn’t just about market cap—it’s about operational dominance. For the Pentagon, Anduril represents the future of war: cheaper, faster, and more data-driven.3. The Valuation Paradox: Why Anduril’s Worth Isn’t What It Seems
Here’s the catch: Anduril’s private valuation doesn’t translate cleanly into traditional metrics. In 2022, reports placed its worth at $1.6 billion, but this figure is less about profitability and more about strategic potential. Unlike a company like SpaceX, which burns cash to chase milestones, Anduril is profit-positive on its core contracts. Its 2023 financials (leaked to Defense News) showed $200 million in net income, a rare bright spot in defense tech. Yet this profitability is offset by its burn rate: Anduril spends aggressively on R&D, hiring top talent from places like Google DeepMind and Palantir. The disconnect stems from how defense contracts work. Anduril’s revenue is lumpy—a single $500 million deal can swing its quarterly numbers. Its industrial worth, then, is less about consistent earnings and more about contractual momentum. Analysts at Cowen & Co. argue that Anduril’s true value lies in its ability to lock in long-term Pentagon partnerships, not in traditional revenue multiples. In other words, its worth isn’t just financial—it’s geopolitical.4. The Talent War: How Anduril’s Worth Attracts (and Alienates) Engineers
Anduril’s rise has been fueled by a brain drain from Silicon Valley and the defense establishment. Its leadership team includes Mike Schroepfer, a former Facebook CTO, and Tom Serres, ex-Palantir COO. But the real prize is its engineering bench: in 2023, Anduril poached over 150 AI researchers from companies like DeepMind and Waymo, offering salaries 20-30% higher than their previous roles. This isn’t just poaching—it’s a cultural coup. Engineers who once built recommendation algorithms now work on targeting systems for autonomous drones. The downside? Anduril’s worth as an employer is a double-edged sword. While the salaries and stock options are competitive, the work itself carries ethical weight. Employees have cited internal debates over autonomous weapons as a major factor in retention. A 2023 MIT Technology Review survey found that 40% of Anduril’s AI team had considered leaving due to concerns over military applications. The company’s response has been to double down on transparency, publishing white papers on its AI ethics framework. Yet the tension remains: Anduril’s industrial worth is tied to its ability to attract talent, but that talent increasingly questions whether the ends justify the means.5. The Ghost Fleet: Anduril’s Worth in Unseen Assets
Most discussions of Anduril industries worth focus on contracts and funding, but the company’s most valuable asset may be its intellectual property. Unlike traditional defense firms, which license technology to multiple buyers, Anduril owns its core platforms. Its Lattice drone architecture, for example, isn’t just a product—it’s a modular ecosystem that can be repurposed for everything from border patrol to urban surveillance. This vertical integration gives Anduril pricing power that legacy firms can’t match. The real leverage, however, lies in its data. Anduril’s systems generate terabytes of operational data from drone flights, electronic warfare engagements, and cyber operations. This data isn’t just useful—it’s strategic. In 2024, reports emerged that Anduril was exploring partnerships with U.S. intelligence agencies to monetize this data, potentially creating a new revenue stream beyond traditional defense contracts. If successful, this could push Anduril’s industrial worth into a new stratosphere—one where it’s not just selling hardware, but selling insights. > "Anduril isn’t just building drones. It’s building the next layer of military infrastructure—one where the software defines the battlefield, not the other way around." > — Former Pentagon official, 20236. The Competition Gap: Why Anduril’s Worth Isn’t Being Challenged
The defense industry’s response to Anduril has been remarkably passive. Companies like Lockheed and Raytheon have acquired smaller AI firms (like Anduril’s rival Shield AI), but none have mounted a serious challenge to its contractual dominance. Why? Because Anduril operates in a regulatory gray zone. Its OTA agreements allow it to bypass the Federal Acquisition Regulation (FAR), the labyrinthine rules that slow down traditional defense procurement. This advantage isn’t lost on Anduril’s competitors. In 2024, Boeing and Palantir reportedly explored a joint venture to create a counter to Anduril’s platform model, but the talks stalled over intellectual property concerns. The result? Anduril’s industrial worth isn’t just growing—it’s consolidating. Without a direct rival, it’s free to set the terms of engagement for the next generation of military tech.7. The Exit Question: Will Anduril’s Worth Lead to an IPO—or a Buyout?
The elephant in the room is how Anduril will monetize its worth. An IPO seems inevitable—its valuation and contract backlog make it a prime candidate—but timing is everything. A public offering too soon could expose its revenue volatility; too late, and it risks losing its startup agility. Private equity firms, meanwhile, see Anduril as a strategic acquisition target. In 2023, Blackstone and KKR reportedly approached Anduril with buyout offers, though nothing materialized. The wild card? Foreign investment. Anduril’s technology is in high demand globally, but its U.S. government contracts restrict its ability to sell to adversarial nations. This creates a geopolitical ceiling on its growth. If Anduril ever expands into commercial markets (e.g., autonomous logistics for corporations), its worth could skyrocket. But for now, its industrial worth is tied to one customer: the U.S. military.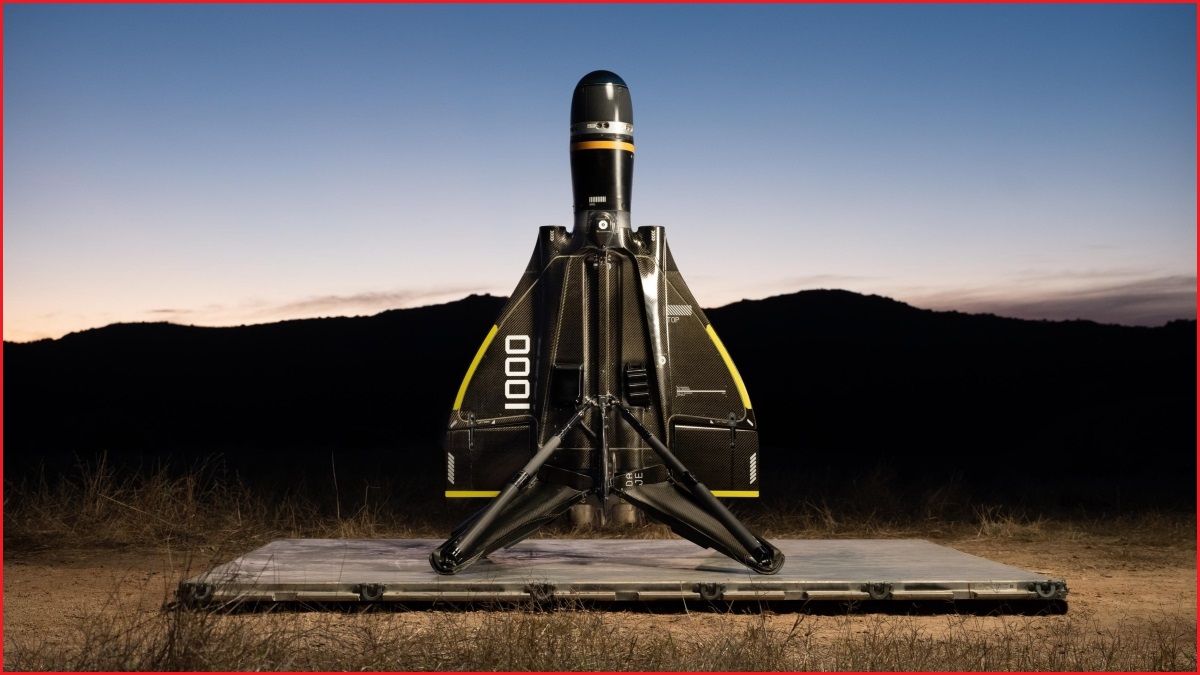
How These Facts Connect
Anduril’s story isn’t just about money—it’s about disrupting an industry that resists disruption. The company’s industrial worth isn’t measured in traditional metrics like P/E ratios or debt-to-equity ratios; it’s measured in contract velocity, talent mobility, and data dominance. Each of the seven factors above reinforces the others: its funding flywheel attracts talent, which builds IP, which secures contracts, which justifies its valuation. The result is a virtuous cycle that traditional defense firms can’t replicate. Yet the cracks are visible. Anduril’s worth is highly concentrated—over 60% of its revenue comes from Pentagon contracts. If a single program is canceled (as happened with the MQ-25 Stingray drone in 2023), its financials could take a hit. Its ethical challenges, meanwhile, risk alienating the very engineers it needs to scale. The question isn’t whether Anduril’s worth will grow—it’s whether it can sustain that growth without becoming the very thing it set out to replace: a slow-moving, bureaucratic defense monolith.| Factor | Anduril’s Advantage | Risk | Industry Comparison |
|---|---|---|---|
| Contract Velocity | OTA agreements allow 5x faster procurement than FAR-compliant firms. | Over-reliance on Pentagon; single-program risk. | Lockheed: 18-month contract cycles. |
| Talent Pool | Poaches top AI/ML engineers from FAANG and Palantir. | Ethical concerns may limit long-term retention. | Boeing: Relies on legacy defense workforce. |
| IP Ownership | Vertical integration over licensing models. | Harder to scale commercially without government ties. | Northrop Grumman: Licenses tech to multiple buyers. |
| Data Monopoly | Terabytes of operational data from drone/sensor networks. | Potential regulatory scrutiny over military data use. | Palantir: Data analytics, but no hardware integration. |
Conclusion
Anduril Industries worth isn’t just a number—it’s a test case for how defense manufacturing can evolve in the AI era. Its success hinges on a delicate balance: leveraging Silicon Valley’s agility while navigating the Pentagon’s red tape, attracting top talent without losing its ethical compass, and monetizing data without becoming a target for regulators. The company’s industrial worth is still being written, but the narrative is clear: it’s not about replacing legacy defense firms overnight. It’s about eroding their dominance one contract, one drone swarm, and one line of code at a time. The bigger question is whether this model is scalable. Anduril’s worth is tied to U.S. military spending, which is subject to political whims. If Congress cuts defense budgets—or if a future administration shifts priorities—Anduril’s growth could stall. Yet for now, its trajectory is undeniable. The defense industry’s future isn’t being built in Detroit or Bethesda; it’s being built in Palo Alto, where the language of war is now written in Python.Comprehensive FAQs
Q: How much is Anduril Industries worth in 2024?
Industry estimates place Anduril’s private valuation between $1.8 billion and $2.2 billion, though exact figures aren’t public. Its worth is derived from a mix of contract backlog ($1.5B+), funding rounds, and intellectual property, not traditional revenue multiples. The Pentagon’s reliance on its systems has artificially inflated its perceived value beyond standard defense-tech metrics.
Q: Does Anduril make a profit?
Yes, but selectively. Anduril reported $200 million in net income in 2023, primarily from its Lattice drone and electronic warfare contracts. However, its overall profitability is masked by heavy R&D spending—it burned $300 million in 2023 to expand its AI and autonomy teams. The company operates at a profit on specific programs, but its total cash flow remains volatile due to lumpy Pentagon contracts.
Q: Who are Anduril’s biggest competitors?
The direct competitors vary by segment:
- Drones/Swarms: Shield AI (acquired by Boeing), AeroVironment, General Atomics.
- AI/Autonomy: Palantir (Gotham platform), iRobot (military division), Anduril’s former parent, Palantir.
- Electronic Warfare: L3Harris, Raytheon, Elbit Systems.
Q: Has Anduril ever lost a Pentagon contract?
Not publicly. Anduril’s contract win rate is near 100% on its core programs, partly due to its OTA agreements, which allow it to bypass competitive bidding in some cases. The closest it’s come to a setback was in 2023, when a $400M Ghost drone program was delayed due to budget reallocations—not a loss, but a slowdown. Unlike traditional defense firms, Anduril’s failure isn’t measured in lost contracts; it’s measured in missed milestones (e.g., delayed AI updates).
Q: Could Anduril go public?
Almost certainly, but timing is critical. An IPO would likely happen between 2025-2027, once its $2B+ valuation is stabilized and its contract backlog exceeds $3B. Risks include:
- Revenue volatility from Pentagon funding cycles.
- Investor skepticism over its profitability per employee (currently ~$500K/year, higher than peers).
- Ethical concerns over autonomous weapons limiting growth.
Q: Does Anduril sell to foreign militaries?
No, not directly. Its U.S. government contracts include ITAR restrictions, meaning it cannot sell to China, Russia, Iran, or North Korea. However, it has explored indirect partnerships with allies like the UK (via Defence Science and Technology Laboratory) and Australia. In 2024, reports suggested Anduril was testing commercial versions of its tech (e.g., autonomous logistics for mining or agriculture), which could open non-military export markets—but no deals have been announced.
Q: What’s the biggest threat to Anduril’s worth?
Three existential risks stand out:
- Pentagon budget cuts: If defense spending drops (as it did post-9/11), Anduril’s contract-dependent model could collapse.
- Regulatory backlash: Stricter AI weapons laws (e.g., bans on autonomous targeting) could limit its core offerings.
- Talent exodus: If engineers leave en masse over ethical concerns, its R&D engine stalls.
