The Complete Overview of Wealth Thresholds in America
The concept of a millionaire in the U.S. has evolved alongside the economy itself. What once required decades of corporate ladder-climbing or family inheritance now can be achieved through a combination of high-earning careers, strategic investments, and the sheer appreciation of assets over time. The number of Americans with net worths exceeding $1 million is a moving target, influenced by market cycles, policy changes, and cultural attitudes toward debt and savings. For instance, the 2008 financial crisis temporarily stalled growth in this demographic, but the subsequent recovery—marked by low interest rates and a surging stock market—propelled the count to new highs. Industry estimates vary, but the most widely cited figures come from the Spectrem Group, a firm specializing in affluent consumer research. Their data suggests that as of 2023, approximately 12.3 million American households hold net worths of $1 million or more. This represents roughly 9.5% of all U.S. households, a figure that has risen steadily since the early 2000s. However, these numbers are often debated. The Federal Reserve’s Survey of Consumer Finances, for example, uses a broader definition of net worth that includes primary residences, which can inflate the count in high-cost housing markets. Conversely, studies focusing on liquid net worth—excluding homes and businesses—typically yield lower figures, sometimes as low as 8 million households. The discrepancy isn’t just methodological; it’s also generational. Older Americans, who own homes outright and benefit from decades of asset appreciation, dominate the millionaire ranks. But younger cohorts are entering the fray. A 2022 report by the St. Louis Federal Reserve found that the median net worth of households headed by someone under 35 had grown by 87% in real terms since 1989, though still far below the millionaire threshold. This suggests that while the overall number of millionaires is rising, the composition is shifting—slowly but undeniably. What remains constant is the concentration of wealth. The top 10% of U.S. households control roughly 70% of all liquid assets, and within that tier, the millionaire segment represents a critical mass. Their spending power, investment decisions, and philanthropic contributions ripple through the economy, from luxury real estate markets to private equity funds. Yet for all their influence, they remain a statistical footnote in broader discussions about wealth inequality, often overshadowed by the billionaire class or the struggles of the working poor.Historical Background and Evolution
The modern millionaire in America is a product of post-World War II economic policies, the rise of the middle class, and the democratization of financial products like mutual funds and 401(k)s. In the 1950s and 60s, achieving a net worth of $1 million required owning a business, inheriting land, or securing a high-ranking corporate position. The number of Americans with over $1 million in net worth was minuscule—likely under 1% of households—because wealth was tightly controlled by the elite. The Great Depression had eroded trust in speculative investments, and the post-war economy prioritized stability over rapid accumulation. The 1980s marked a turning point. Deregulation, the rise of Wall Street, and the tax reforms of the Reagan era created new pathways to wealth. Real estate booms in cities like Miami and Los Angeles produced instant millionaires, while the tech bubble of the late 1990s saw fortunes built overnight. By the turn of the millennium, the millionaire population had expanded, though still unevenly distributed. The Federal Reserve’s data from 2000 showed that only about 4.5 million households—or 4.2% of all U.S. households—had net worths exceeding $1 million. The dot-com crash and 2008 financial crisis temporarily reversed this growth, but the recovery that followed was swift and sustained. The past decade has seen the most dramatic shift. The combination of historically low interest rates, a bullish stock market, and the appreciation of home values—particularly in high-cost markets like San Francisco and New York—has propelled the millionaire count to record levels. The pandemic era added another layer: stimulus checks, remote work flexibility, and the surge in cryptocurrency and venture capital investments created new wealth-building opportunities. By 2021, the Spectrem Group estimated that the number of U.S. millionaires had grown by over 20% in just two years, a pace not seen since the late 1990s. This growth wasn’t just about the ultra-rich; it reflected a broader trend of middle-class households crossing the $1 million threshold for the first time. Yet the story isn’t one of unbroken progress. The wealth gap persists, and the path to millionaire status remains steep for many. Studies show that Black and Hispanic households have median net worths that are a fraction of white households, even when controlling for income. This disparity is rooted in historical inequities, from redlining to wage gaps, and it underscores that the growth in millionaire numbers doesn’t reflect a level playing field.Core Mechanisms: How It Works
The journey to a net worth of $1 million is rarely linear. It’s a combination of earning power, asset appreciation, and—crucially—opportunity. For most Americans, the path begins with steady income growth, often in professional fields like medicine, law, or technology. A physician earning $300,000 annually can accumulate wealth far more quickly than someone in a $70,000 salary bracket, thanks to the compounding effects of savings and investments. But income alone isn’t enough; how many people in the United States have a net worth over $1 million depends just as much on how that income is deployed. Real estate has been the most reliable wealth multiplier for decades. Homeownership, particularly in high-appreciation markets, allows families to build equity over time. A couple who bought a $500,000 home in 2000 and sold it in 2023 could see a gain of $1 million or more, depending on location. Similarly, rental properties and commercial real estate have long been staples of millionaire portfolios. The stock market plays an equally critical role. Index funds, retirement accounts, and even speculative investments in startups or cryptocurrencies can accelerate wealth accumulation, though with higher risk. Tax policies also shape these outcomes. The elimination of the net investment income tax for lower-income earners, the rise of Roth IRAs, and the stepped-up basis for inherited assets have all made it easier to preserve and grow wealth. Meanwhile, the capital gains tax—which applies only to profits from asset sales—favors long-term investors. For those who inherit wealth, the process is often seamless. A child who receives a $1 million trust fund at age 25 can manage that capital far more easily than someone starting from scratch. The role of luck cannot be overstated. Market timing, a single high-earning job, or an unexpected windfall (like a lottery win or a family settlement) can catapult an individual into the millionaire ranks overnight. Conversely, bad luck—a job loss, a medical emergency, or a market crash—can derail decades of planning. The number of Americans with over $1 million in net worth is thus a reflection of both systemic advantages and individual agency.Key Benefits and Crucial Impact
The millionaire demographic is more than a statistical curiosity; it’s a force that shapes consumer markets, political influence, and economic policy. These individuals wield disproportionate power in philanthropy, education, and even urban development. Their spending habits drive demand for luxury goods, private education, and high-end services, while their political donations can sway elections. Yet their impact isn’t uniformly positive. The concentration of wealth in this group has contributed to rising inequality, straining social safety nets and exacerbating housing shortages in desirable cities. The benefits of reaching a $1 million net worth are tangible. Financial independence becomes a reality, allowing for early retirement, entrepreneurial ventures, or charitable giving. The millionaire threshold also unlocks access to exclusive networks—private clubs, high-net-worth investment advisors, and elite educational institutions for children. Psychologically, it offers security, reducing the stress of financial instability. For many, it’s the culmination of a lifetime of disciplined saving and strategic investing. The downside is less visible but equally significant. The number of Americans with over $1 million in net worth is growing, but so is the gap between them and everyone else. Middle-class families struggle to keep pace, while the ultra-wealthy benefit from compounding returns on their investments. This divide has led to calls for wealth taxes, higher capital gains rates, and reforms to inheritance laws. Critics argue that the current system rewards those who already have advantages, perpetuating cycles of inequality."Wealth isn’t just about money. It’s about the options money buys—and the options that are systematically denied to others." — Rachel Schneider, economist and author of The Millionaire Paradox
Major Advantages
- Financial freedom: The ability to retire early, take career risks, or weather economic downturns without financial ruin.
- Access to elite networks: Connections to private equity firms, luxury real estate markets, and high-end service providers.
- Tax optimization: Lower effective tax rates through deductions, trusts, and asset location strategies.
- Generational wealth transfer: The ability to pass down significant assets to heirs, often tax-free or at reduced rates.
- Philanthropic influence: The capacity to fund causes, scholarships, or community projects at scale.
- Geographic flexibility: The option to live in desirable locations, even if local costs are high, without sacrificing lifestyle.

Comparative Analysis
| Metric | United States |
|---|---|
| Estimated millionaire households (2023) | 10–12.3 million (varies by source) |
| Percentage of total households | 9.5% (Spectrem Group) |
| Median age of millionaires | 60–65 (older cohorts dominate) |
| Primary wealth sources | Real estate (40%), stocks (35%), business equity (20%) |
| Wealth gap disparity | White households: ~$1.1M median net worth; Black households: ~$248K |
Future Trends and Innovations
The number of Americans with over $1 million in net worth is projected to grow, but the drivers will shift. The next decade will likely see a decline in traditional real estate-based wealth as younger generations prioritize flexibility over homeownership. Instead, assets like cryptocurrency, private equity, and intellectual property (such as patents or royalties) may become more prominent. The rise of remote work could also decentralize wealth, with millionaires emerging in smaller cities and international hubs rather than just coastal metropolises. Policy changes will play a critical role. Proposals for wealth taxes, higher capital gains rates, or reforms to inheritance laws could alter the trajectory of this demographic. Meanwhile, technological advancements—such as AI-driven investment tools or decentralized finance—may democratize wealth-building, though they could also create new divides. One certainty is that the millionaire population will remain a key indicator of economic health, reflecting both opportunity and inequality in the years ahead.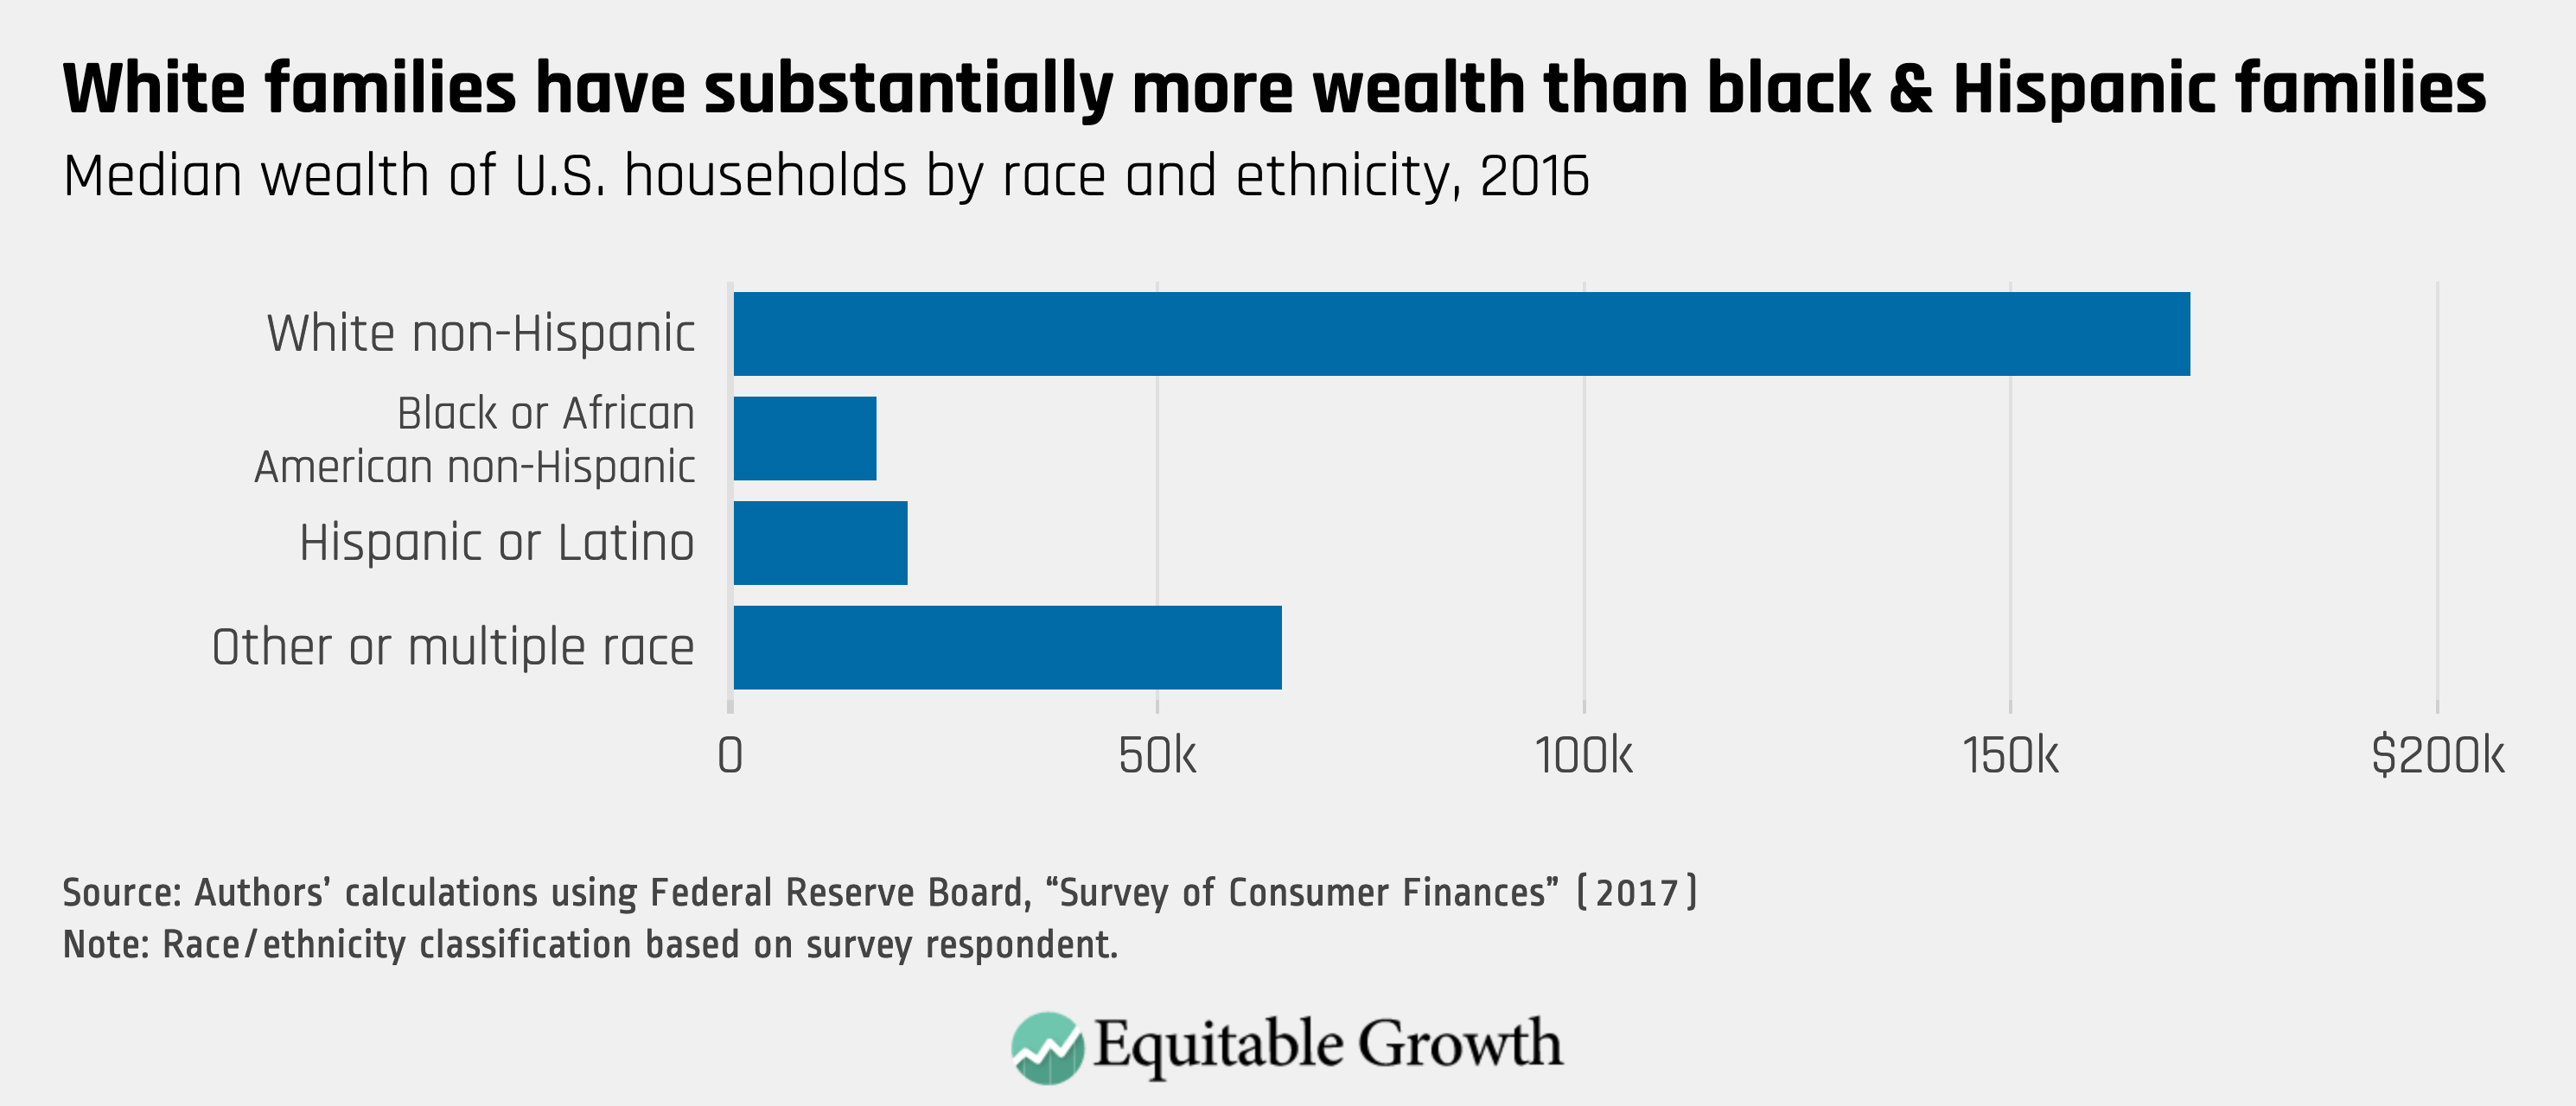
Conclusion
The question of how many people in the United States have a net worth over $1 million is more than a numerical exercise; it’s a mirror held up to the American economy. The growth of this group reflects the success of certain financial strategies, the resilience of asset markets, and the advantages of systemic privilege. Yet it also highlights the stark realities of inequality, where access to wealth-building tools remains uneven. Understanding these dynamics is essential for policymakers, economists, and everyday citizens alike. As the millionaire demographic continues to evolve, so too will its impact. Will it lead to broader prosperity, or will it deepen the divides between the haves and have-nots? The answer lies not just in the numbers, but in the choices we make—individually and collectively—about how wealth is created, shared, and sustained.Comprehensive FAQs
Q: What is the most accurate estimate of how many Americans have a net worth over $1 million?
The most widely cited figure comes from the Spectrem Group, which estimates around 12.3 million U.S. households have net worths exceeding $1 million as of 2023. However, this varies by source—some studies using stricter definitions (like liquid assets only) suggest the number is closer to 10 million. The Federal Reserve’s broader definition of net worth (including primary residences) tends to inflate the count in high-cost housing markets.
Q: How has the number of U.S. millionaires changed over the past 20 years?
According to historical data, the number of Americans with over $1 million in net worth has more than doubled since the early 2000s. In 2000, roughly 4.5 million households met this threshold; by 2023, that figure had grown to 10–12.3 million, reflecting bull markets, real estate appreciation, and policy changes like lower capital gains taxes. The growth was temporarily stalled by the 2008 financial crisis but rebounded sharply in the 2010s.
Q: Are there significant regional differences in millionaire concentrations?
Yes. Coastal cities and tech hubs like San Francisco, New York, and Seattle have the highest densities of millionaires, often exceeding 20% of households in certain ZIP codes. In contrast, rural areas and the Rust Belt see millionaire rates below the national average (around 5–10%). The disparity is driven by housing costs, job markets, and historical wealth accumulation. For example, a millionaire in Miami may have a very different asset composition than one in Omaha.
Q: What percentage of U.S. millionaires are self-made versus inherited wealth?
Estimates suggest that about 60–70% of U.S. millionaires are self-made, meaning they built their wealth through careers, businesses, or investments rather than inheritance. However, this varies by generation: older millionaires are more likely to have inherited assets, while younger cohorts (under 50) skew toward self-made wealth. Studies also show that women and minorities are underrepresented in both categories, often due to systemic barriers in earning and asset accumulation.
Q: How does the U.S. millionaire population compare to other developed nations?
The U.S. has one of the largest absolute numbers of millionaires in the world, but its percentage of millionaire households is lower than some European nations. For example, Switzerland and Germany have higher ratios of millionaire households relative to their populations, partly due to stronger social safety nets that allow for greater wealth preservation. However, the U.S. leads in ultra-high-net-worth individuals (those with $30 million+), reflecting its dynamic startup culture and financial markets.
Q: What are the biggest threats to the growth of the U.S. millionaire class?
The primary risks include rising interest rates (which reduce asset appreciation), inflation (eroding real returns), and policy changes such as wealth taxes or higher capital gains rates. Additionally, demographic shifts—like an aging population and slower wage growth—could temper future growth. The number of Americans with over $1 million in net worth may also stagnate if younger generations face higher student debt burdens or housing costs that outpace income growth.
