
7 Things Worth Knowing About the Best Wealth Preservation Strategies for High-Net-Worth Individuals
The ultra-rich don’t preserve wealth by accident. They do it through deliberate, often counterintuitive moves that exploit legal gray zones, leverage institutional inefficiencies, and insulate assets from systemic risks. These aren’t one-size-fits-all tactics; they’re tailored to the individual’s exposure profile. What works for a tech billionaire in Silicon Valley differs from a European aristocrat with landholdings. The common thread? Best wealth preservation strategies for high-net-worth individuals prioritize control over liquidity, privacy over transparency, and longevity over legacy. The following seven principles cut through the noise. Master them, and wealth becomes self-sustaining. Ignore them, and even the largest fortunes can vanish in a generation.1. Tax Residency as a Strategic Weapon
Wealth preservation starts with jurisdiction. The ultra-rich don’t just move money—they move themselves. Tax residency isn’t a binary choice; it’s a chessboard. A Swiss private banker might advise a client to spend 183 days in Monaco, while a Singaporean trustee could structure residency in Malaysia to access lower capital gains rates. The goal isn’t tax evasion (which remains illegal) but tax optimization within legal boundaries. The most effective strategies involve best wealth preservation strategies for high-net-worth individuals that exploit treaties, territorial taxation, and residency programs. For example, Portugal’s Non-Habitual Resident (NHR) regime offered zero tax on foreign income for a decade—until it was phased out. Now, the focus shifts to Andorra, Dubai, or even less obvious havens like Georgia, where wealth taxes are nonexistent. The key? Dual residency—holding passports in multiple low-tax jurisdictions while maintaining operational bases in high-growth economies.2. The Illusion of Diversification
Diversification is overrated when applied superficially. The ultra-rich don’t just spread risk across asset classes—they correlate risk with control. A private equity fund might hold 20% in tech startups, but the real preservation comes from owning the manager, not just the fund. Similarly, a family office might allocate 10% to art, but the masterpiece is held in a discretionary trust with a Swiss foundation as beneficiary—insulating it from creditors and heirs’ impulsive sales. The best wealth preservation strategies for high-net-worth individuals often involve non-correlated assets: rare metals, vintage wine, or even digital scarcity assets like limited-edition NFTs tied to real-world collateral. The catch? These must be held in structures where valuation isn’t subject to public scrutiny. A family’s $500 million in gold isn’t declared on a balance sheet—it’s stored in a Liechtenstein foundation with anonymous beneficiaries.3. The Trust as a Living Entity
Trusts aren’t static documents. They’re jurisdictional ecosystems. A poorly drafted trust in Delaware is worthless against a Cayman Islands discretionary trust with a Swiss protector and Dubai trustee. The ultra-rich use trusts to: - Decouple ownership from control (e.g., a trust owns a company, but the beneficiary has no voting rights). - Create spendthrift provisions (protecting heirs from lawsuits or divorces). - Enable dynasty planning (assets skip generations tax-free in some jurisdictions). The best wealth preservation strategies for high-net-worth individuals often involve layered trusts: a Delaware revocable trust feeds into a Nevis irrevocable trust, which then distributes to a Singapore family office. Each layer serves a purpose—tax deferral, asset protection, or succession planning—and none can be untangled without triggering legal or financial consequences.4. Crisis-Proofing: When Markets Collapse
Wealth destruction happens in three acts: 1. Liquidity crunches (when assets can’t be sold). 2. Regulatory seizures (governments freezing accounts). 3. Behavioral panics (heirs selling at fire-sale prices). The best wealth preservation strategies for high-net-worth individuals prepare for all three. This means: - Pre-positioned cash in offshore multi-currency accounts (not just USD). - Illiquid but high-value assets (real estate, private equity) held in jurisdictions with strong property rights (e.g., Abu Dhabi freehold zones). - Succession plans that lock in heirs’ behavior (e.g., incentive trusts that penalize early withdrawals). During the 2008 crisis, families with best wealth preservation strategies for high-net-worth individuals in place bought distressed assets while others were forced to liquidate. The difference? Pre-arranged credit lines with private banks and asset-locking mechanisms that prevented forced sales.5. The Privacy Paradox
The more visible your wealth, the more vulnerable it becomes. Best wealth preservation strategies for high-net-worth individuals prioritize opaque ownership structures. This isn’t about hiding from taxes—it’s about hiding from predators: - Shell companies in British Virgin Islands (BVI) or Seychelles to obscure beneficial ownership. - Private placements (selling shares to accredited investors, not the public). - Digital anonymity (using cryptographic identities for transactions, not real names). A single Panama Papers-style leak can trigger lawsuits, kidnapping risks, or regulatory scrutiny. The ultra-rich don’t just use Swiss bank accounts; they use Swiss bank accounts with numbered references, private jet charters (not commercial flights), and cash transactions in low-surveillance economies like Vietnam or the UAE.6. The Generational Transfer Trap
Most fortunes disappear by the third generation. The best wealth preservation strategies for high-net-worth individuals don’t just preserve wealth—they preserve the family’s ability to manage it. This involves: - Education trusts that fund heirs’ financial literacy (many trust beneficiaries don’t understand compounding or inflation). - Staggered distributions (not handing over control at 25). - Professional trustees (not family members) to prevent emotional decisions. A study of Forbes 400 families found that those using best wealth preservation strategies for high-net-worth individuals with independent governance (e.g., family offices with non-family CEOs) retained wealth 40% longer than those relying on direct inheritance.7. The Future-Proofing Gambit
"The only predictable thing about the future is that it will be unpredictable. The best wealth preservation strategies for high-net-worth individuals aren’t about predicting crises—they’re about ensuring you can survive any of them." — James Rickards, economist and author of The Death of MoneyThis means: - Decentralized wealth storage (not all eggs in one bank). - Crisis currencies (gold, Bitcoin, or rare-earth metals as hedges). - Adaptive structures (trusts that can be amended without triggering taxes). The ultra-rich don’t bet on one future—they hedge against all of them. A Singapore-based family office might hold: - 30% in traditional assets (stocks, bonds). - 20% in private equity (illiquid, high-growth). - 20% in hard assets (land, art, collectibles). - 15% in digital assets (crypto, tokenized real estate). - 15% in liquidity buffers (cash, gold, short-term bonds). The mix shifts based on geopolitical signals, not market noise.
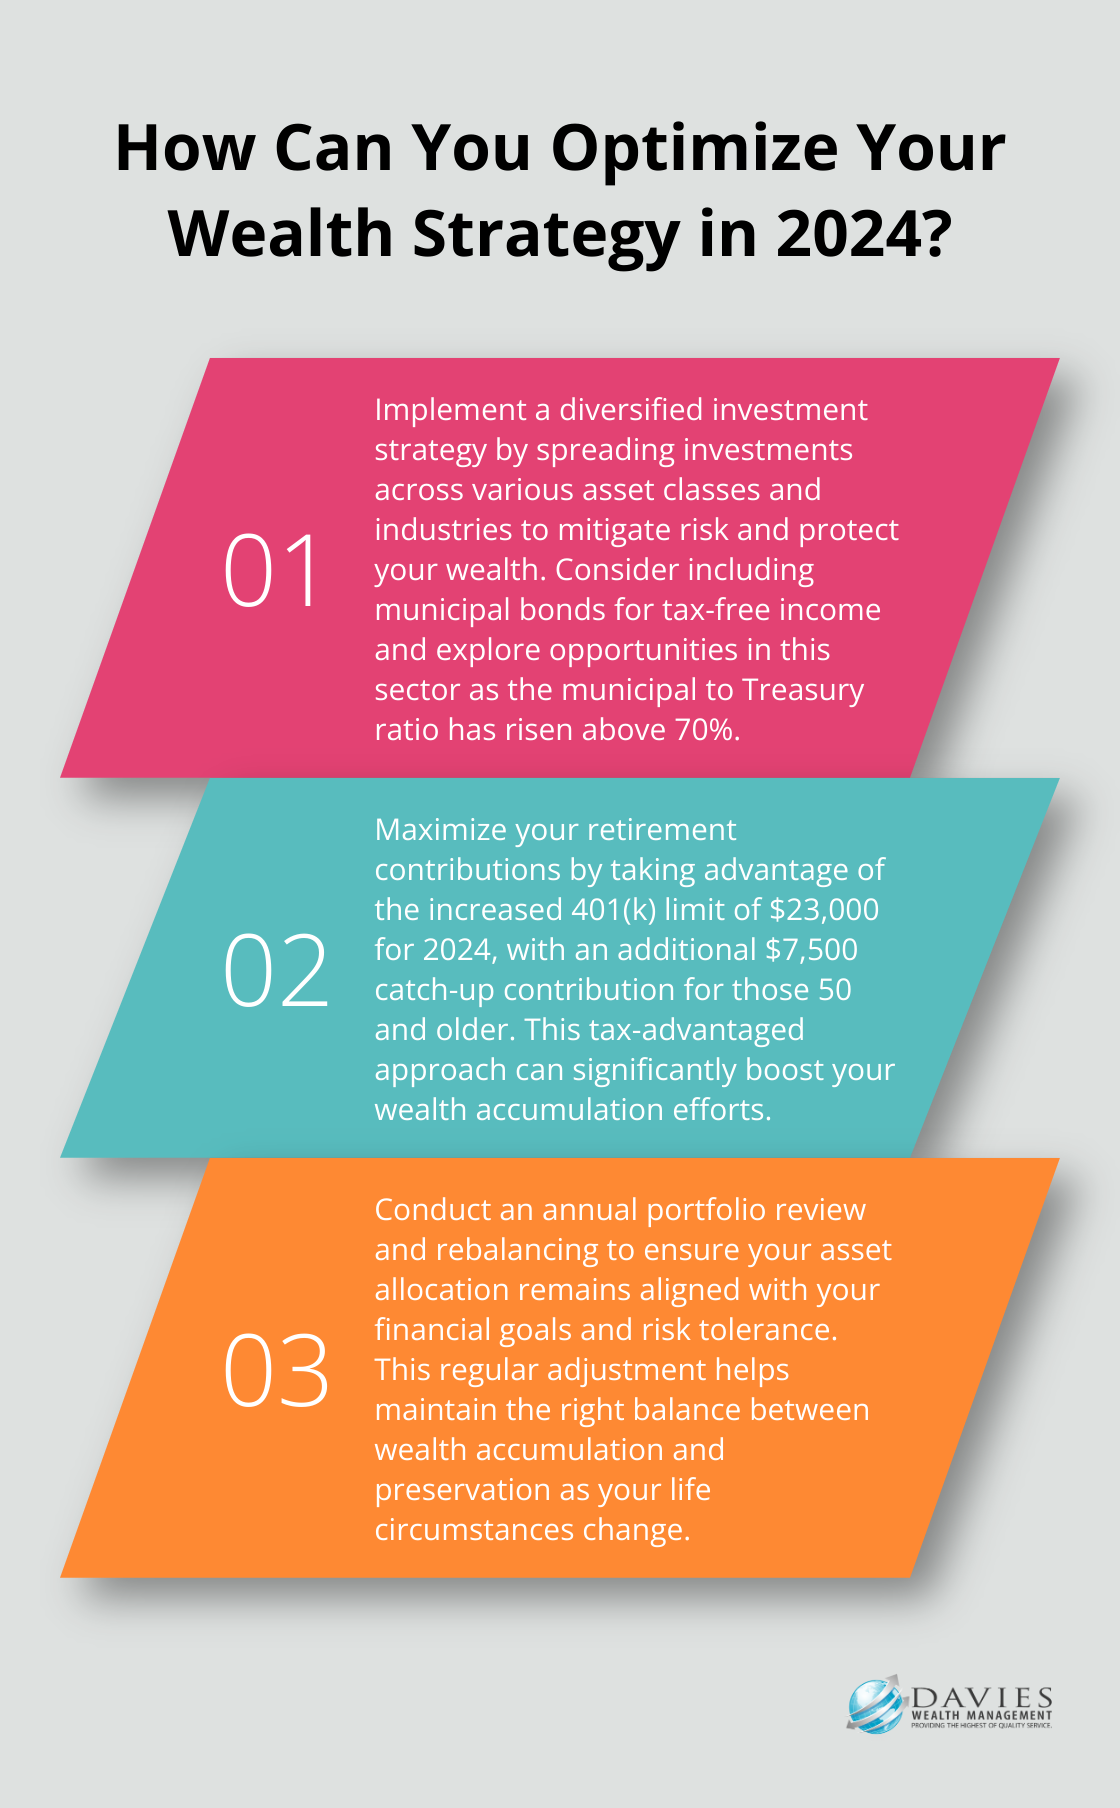
How These Facts Connect
The best wealth preservation strategies for high-net-worth individuals aren’t isolated tactics—they’re a system. Tax residency, trust structuring, and crisis planning don’t work in silos; they reinforce each other. A family that moves to Monaco for tax benefits but keeps assets in New York is exposed to U.S. estate taxes. A trust in Delaware without a Swiss protector can be challenged in court. The ultra-rich think in layers of defense—each strategy assumes the next will fail. The table below compares the core pillars of wealth preservation and their interdependencies:| Strategy | Primary Goal | Biggest Weakness | How to Mitigate |
|---|---|---|---|
| Tax Residency Optimization | Minimize tax liabilities | Regulatory crackdowns (e.g., CRS, FATCA) | Use jurisdictional arbitrage (e.g., Portugal → Georgia) |
| Trust Structuring | Asset protection & succession | Poor drafting or beneficiary disputes | Layered trusts with independent trustees |
| Crisis-Proofing | Survive liquidity shocks | Over-reliance on public markets | Illiquid, high-value assets in safe jurisdictions |
| Privacy Engineering | Avoid predatory lawsuits | Digital leaks (e.g., data breaches) | Cryptographic identities + offshore entities |
Conclusion
Wealth preservation isn’t about holding onto money—it’s about controlling the rules that govern money. The ultra-rich don’t play by the same rules as the middle class; they rewrite them. The best wealth preservation strategies for high-net-worth individuals aren’t found in textbooks or robo-advisors—they’re found in private chambers, tax treaties, and decades-old legal precedents. The biggest mistake? Assuming preservation is passive. It’s active, aggressive, and adaptive. A fortune built in the 1980s won’t survive if structured like a 2020s portfolio. The strategies that work today may need updating by 2030—when AI-driven audits, quantum computing, and global wealth taxes reshape the landscape. The ultra-rich don’t fear losing money. They fear losing control—and that’s what these strategies prevent.Comprehensive FAQs
Q: Can I use these strategies if I’m not a billionaire?
A: Yes, but the scale changes. A high-net-worth individual (e.g., $5–50 million) can use offshore trusts, tax-efficient residency, and private banking—just on a smaller scale. The principles are the same; the execution adapts to net worth. For example, a $10 million portfolio might use a Nevis trust instead of a Liechtenstein foundation, but the goal (asset protection) remains identical.
Q: Are offshore accounts illegal?
A: No—if structured properly. Legal offshore accounts (e.g., in Singapore, Switzerland, or the UAE) are used by multinational corporations and families to optimize taxes and protect assets. Illegal accounts involve tax evasion, money laundering, or fraud. The key difference? Compliance with reporting rules (e.g., CRS, FATCA). The ultra-rich use transparent offshore structures—they just minimize exposure to unnecessary scrutiny.
Q: How do I protect my wealth from my heirs?
A: Through incentive trusts, spendthrift clauses, and staggered distributions. A discretionary trust allows trustees to withhold funds if an heir is reckless, while a life insurance trust ensures tax-free transfers. The best wealth preservation strategies for high-net-worth individuals often include professional trustees (not family members) to prevent emotional decisions. For example, a $50 million trust might release $5 million per year, forcing heirs to live off income rather than sell assets.
Q: What’s the safest place to hold cash?
A: Diversified across jurisdictions. The ultra-rich don’t keep all cash in one bank. Instead, they use: - Swiss private banks (for CHF-denominated accounts). - Singapore dollar accounts (for Asia exposure). - Gold-backed accounts (e.g., Perth Mint allocations). - Multi-currency accounts (e.g., Dubai Islamic Bank). The safest approach? No single account holds more than 10–15% of total liquidity, and none is in a jurisdiction with weak bank secrecy laws (e.g., U.S. or EU for large balances).
Q: Can cryptocurrency be part of wealth preservation?
A: Yes, but only as a small hedge (5–10%). Bitcoin and stablecoins (e.g., USDC, Tether) are used by the ultra-rich for: - Cross-border transfers (faster than SWIFT). - Inflation hedging (in high-inflation economies like Argentina or Venezuela). - Decentralized storage (e.g., self-custody wallets in Switzerland or Singapore). The risk? Regulatory bans (e.g., China’s crypto crackdown) or exchange hacks. The best wealth preservation strategies for high-net-worth individuals treat crypto as one tool among many, not a core holding.
Q: How do I choose a private banker?
A: Reputation, discretion, and global reach matter most. The ultra-rich avoid mass-market private banks (e.g., UBS for retail clients) and seek: - Tiers 1–2 banks (e.g., Julius Baer, Lombard Odier, or EFG). - Specialized boutiques (e.g., Lombard Odier’s wealth management for $50M+ clients). - Independent advisors (not tied to a single bank). The red flags? Aggressive sales pitches, lack of offshore expertise, or transparency issues. The best bankers don’t ask for your entire net worth upfront—they earn trust through discretion and strategy.
Q: What’s the biggest threat to wealth preservation today?
A: Regulatory overreach and digital surveillance. Governments are mapping private wealth like never before: - Automated tax audits (using AI to flag anomalies). - Crypto tracking (e.g., Chainalysis for law enforcement). - Beneficial ownership registers (e.g., EU’s public company ownership databases). The best wealth preservation strategies for high-net-worth individuals now focus on digital anonymity (e.g., Monero for transactions) and jurisdictional agility (e.g., moving assets to Panama or Belize before new laws pass). The era of opaque wealth is ending—opaque but legal wealth is the new standard.
