5 Things Worth Knowing About Applying for FFL License
The path to becoming a licensed firearms dealer is paved with landmines most applicants don’t see until it’s too late. Here’s what separates the prepared from the unprepared.1. The ATF’s "Type" Designation Decides Your Future
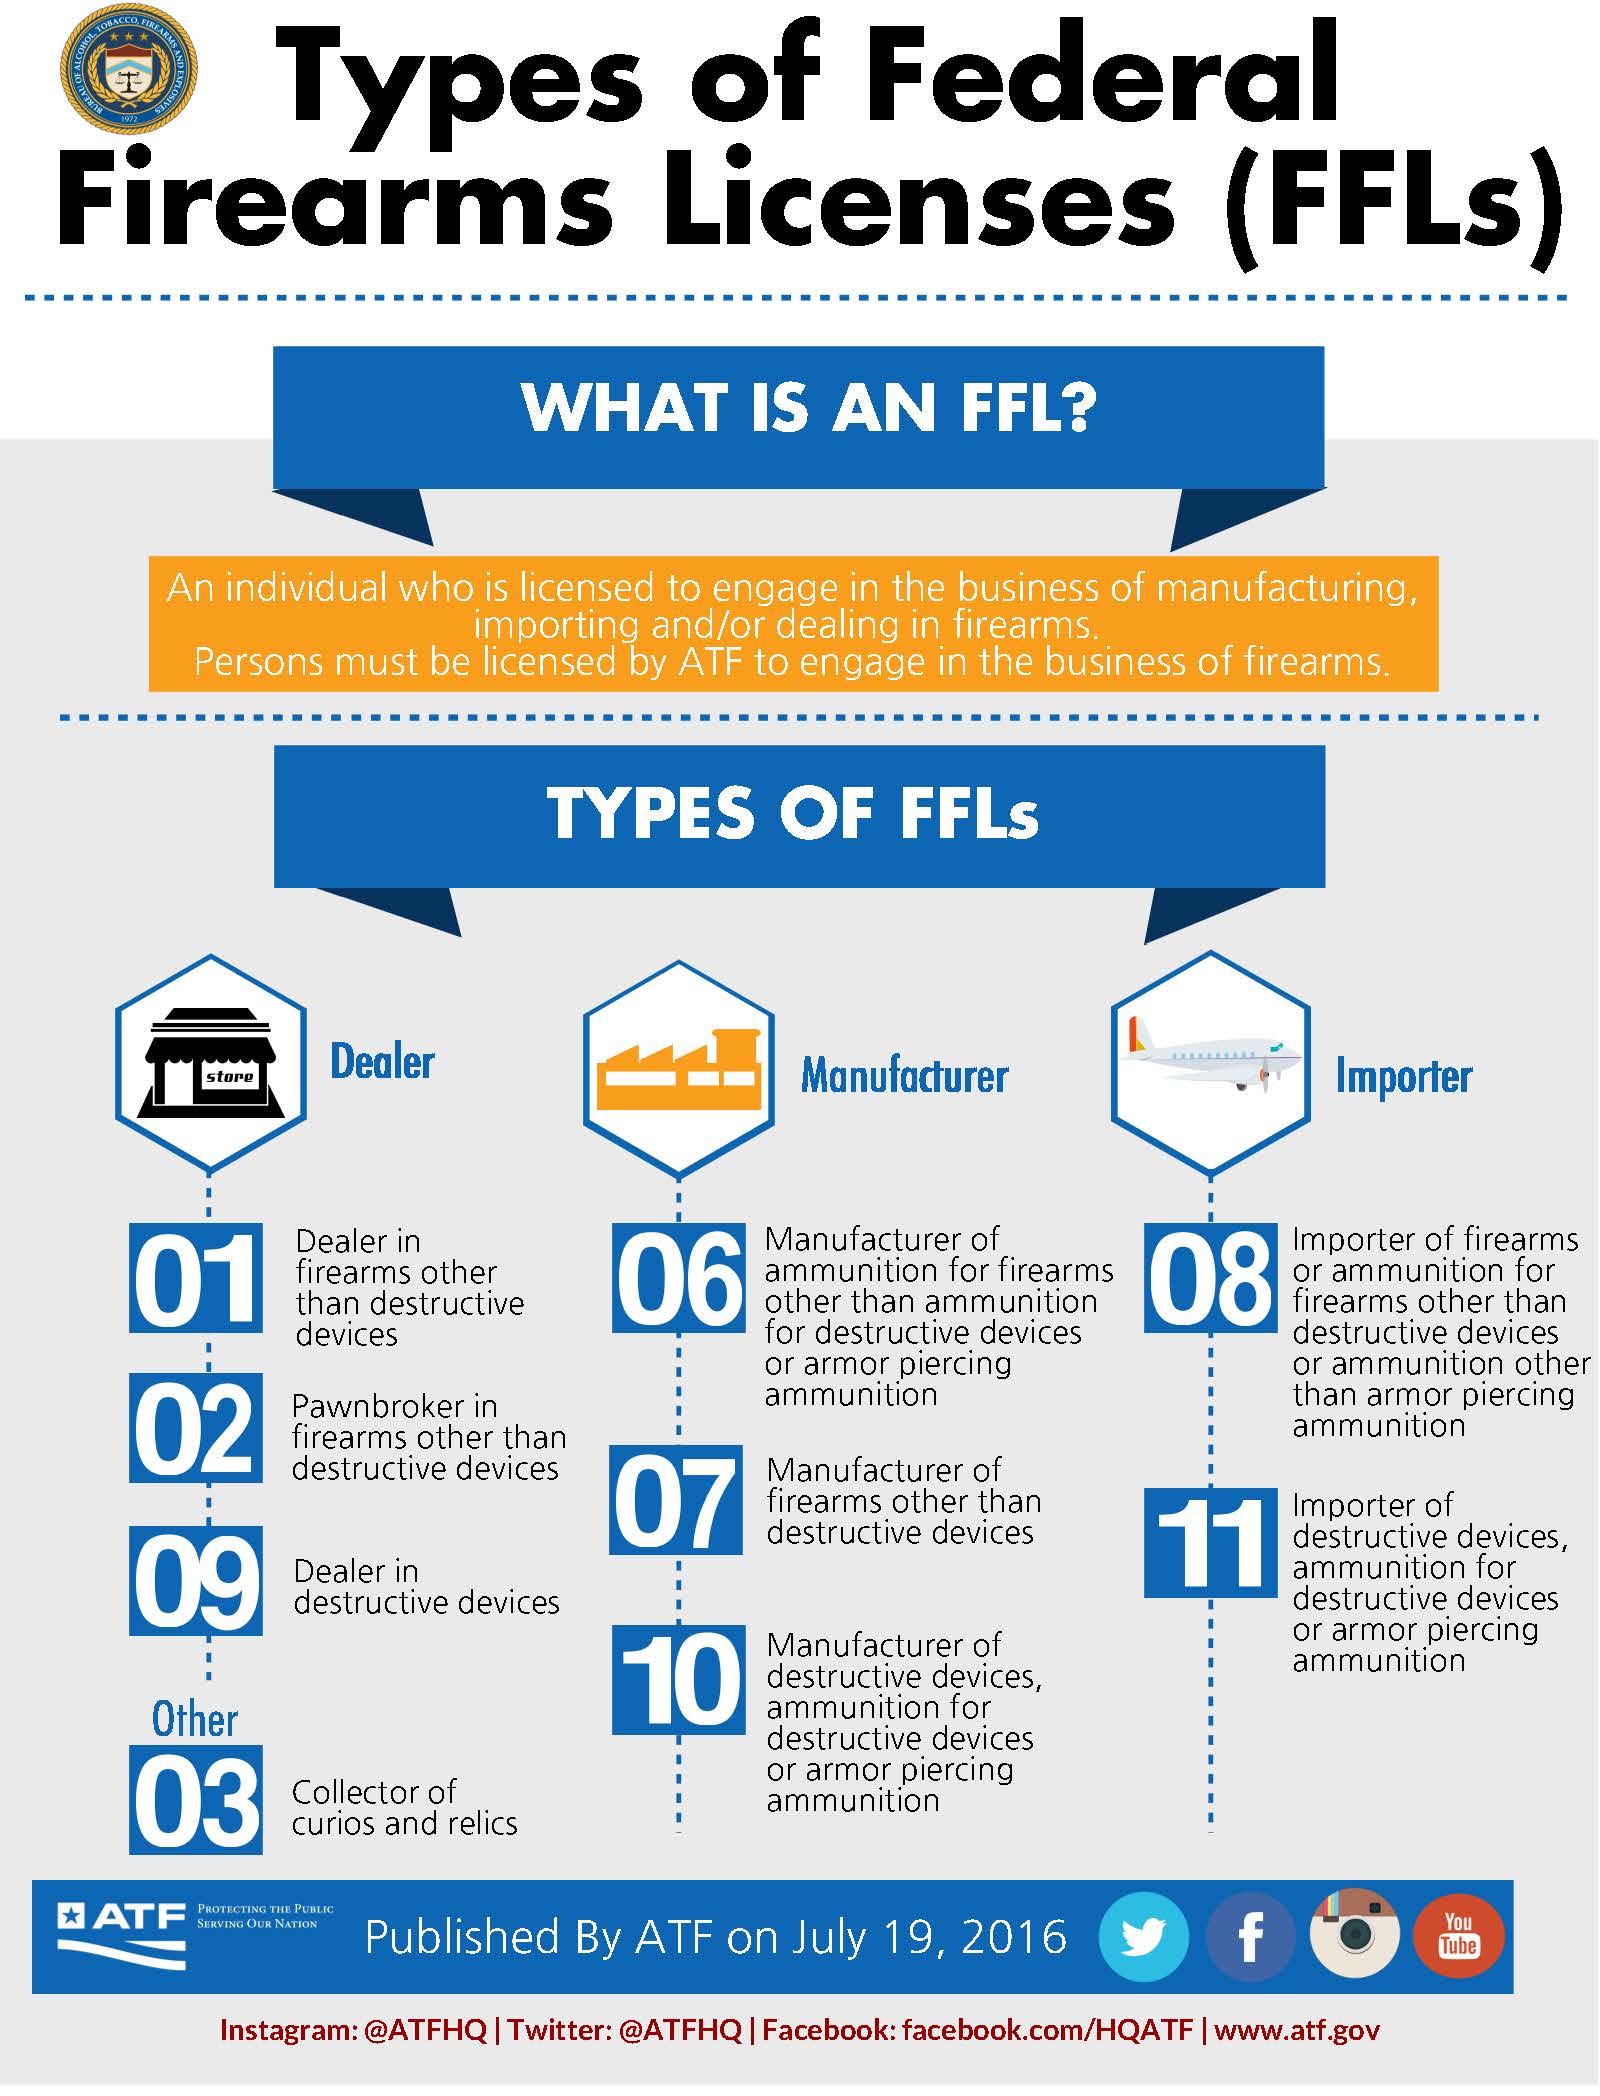
Your FFL application begins with a choice: Type 01 (retail), Type 02 (pawnbroker), Type 03 (manufacturer), or Type 07 (collector). This isn’t just administrative—it dictates your storage requirements, tax obligations, and even which ATF field office will oversee you. A Type 01 dealer, for instance, must comply with the BATFE’s 4473 record-keeping rules, while a Type 07 collector faces no such scrutiny. The mistake? Assuming you can switch types later. The ATF treats type changes as a new application, resetting your processing clock. The deeper issue lies in how the ATF interprets your "primary purpose." If your business plan leans too heavily toward "firearm restoration," they may classify you as a manufacturer (Type 03), subjecting you to additional inspections. One applicant in Texas lost six months after the ATF reclassified his shop based on a single line in his business description: "We refurbish vintage firearms for collectors." The lesson? Every word in your application is a potential audit trigger.2. Background Checks Aren’t Just About You
While your personal history is scrutinized, the ATF also runs background checks on every person listed in your business plan—including silent partners, family members with 10% ownership stakes, and even employees if you’re hiring before approval. A 2023 case in Ohio saw an FFL application denied because the applicant’s uncle, listed as a consultant, had a misdemeanor DUI from 2010 that wasn’t disclosed. The ATF’s logic? "Any individual with influence over the business’s operations is fair game." What’s often overlooked is the state-level cross-checks. Some states, like California and New York, share data with the ATF in real time. If your business address has ever been flagged in a local police report—even for a noise complaint—they’ll note it. The fix? A pre-application consultation with your state’s ATF field office to pre-clear your team.3. The Surety Bond Is Your Financial Guarantee—and a Common Tripwire
All FFL applicants must post a $50,000 surety bond (or $25,000 for Type 07 collectors). The problem? Many applicants assume any insurance company will underwrite it. In reality, gun-related bonds are treated as high-risk by underwriters, leading to higher premiums or outright denials. One dealer in Florida paid £1,200 annually for his bond after three insurers rejected his application due to his shop’s location in a "high-theft zone." The bond isn’t just about cost—it’s a liability buffer. If the ATF later revokes your license, they’ll seize your inventory to cover losses. The bond ensures they’re paid first. The catch? Some applicants use personal assets as collateral, only to find their home equity frozen if the bond lapses. The solution? Work with a specialty surety broker who understands ATF’s bond requirements.4. Your Inventory List Is an Audit Waiting to Happen
The ATF’s Form 4473 Supplement requires a detailed inventory of every firearm in your possession—even if you’re just starting. The mistake? Listing guns under their generic model names (e.g., "AR-15") instead of serial numbers. In 2022, 22% of FFL applications were delayed because inventories lacked precise details. The ATF’s reasoning? "Generic listings suggest potential diversion risks." What’s worse is that the ATF cross-references your inventory with stolen-gun databases. If even one firearm in your list has been reported stolen, your application stalls. The fix? Use the NICS Firearm Inventory System to pre-clear your guns before applying. It’s a free tool, but few applicants know it exists.5. The ATF’s "Business Plan" Section Is a Lie Detector
The ATF doesn’t just want to see a business plan—they want to predict your compliance risk. Vague statements like "We plan to sell firearms to responsible customers" raise red flags. Instead, they look for specifics: projected monthly sales volumes, storage security measures, and even your customer demographic breakdown. One applicant in Arizona was denied because his plan lacked a written policy on denying sales to minors—a requirement under the Protected Persons Act. The deeper concern? The ATF’s natural language processing tools now scan for inconsistencies between your plan and your actual operations. If you list "high-end collectibles" as your niche but your inventory shows mostly budget pistols, they’ll question your motives. The solution? Hire a former ATF examiner to review your plan before submission.
How These Facts Connect
The process of applying for an FFL license isn’t linear—it’s a feedback loop where one misstep cascades into others. Your "type" designation affects your bond requirements, which in turn influence your inventory policies, which then determine how the ATF views your business plan. The ATF’s risk-assessment model treats each section as a data point in a larger algorithm, not as isolated questions. What’s clear is that the ATF’s priorities have shifted. No longer is the focus solely on criminal history—it’s on operational risk. A dealer with a clean record but sloppy record-keeping faces the same scrutiny as someone with a minor past offense. The system is designed to self-police, and the penalties for non-compliance are no longer just financial; they’re existential. One revocation can wipe out years of work.| Factor | Impact on Approval | Common Pitfall |
|---|---|---|
| Type Designation | Determines storage, tax, and inspection rules | Assuming you can switch types later |
| Background Checks | Extends to all business associates | Overlooking silent partners’ histories |
| Surety Bond | High-risk = higher premiums or denials | Using personal assets as collateral |
| Inventory List | Cross-checked with stolen-gun databases | Listing guns by model instead of serial number |
| Business Plan | Scanned for operational inconsistencies | Vague sales projections |
Conclusion
Applying for an FFL license is less about whether you’re legally allowed to sell firearms and more about proving you can do so without becoming a liability. The ATF’s system is built to identify not just rule-breakers, but potential rule-breakers—and the tools they use are far more sophisticated than most applicants realize. The good news? Preparation isn’t just possible; it’s the only way to navigate the process without running into the ATF’s automated red flags. The key is treating your application as a stress test. Every section—from your bond details to your inventory list—should be reviewed as if it’s already under audit. The dealers who succeed aren’t the ones who cut corners; they’re the ones who anticipate the ATF’s next question before it’s asked.Comprehensive FAQs
Q: How long does the ATF take to process an FFL application?
A: The ATF’s official processing time is 90 days, but delays are common. In 2023, 42% of applications took 120–180 days due to backlogs. A pre-submission consultation with your local ATF field office can sometimes accelerate this.
Q: Can I apply for an FFL license if I’ve been denied before?
A: Yes, but only after one year has passed since the denial. The ATF requires you to address the original reason for denial in your new application. Many applicants hire a former ATF examiner to rework their case before reapplying.
Q: Do I need a separate license to sell firearms online?
A: No—your FFL license covers online sales, but you must comply with additional state laws (e.g., California’s 10-day waiting period for online purchases). The ATF also requires digital record-keeping for all online transactions, which many dealers overlook.
Q: What happens if the ATF audits my inventory after approval?
A: The ATF can conduct unannounced inspections at any time. If discrepancies are found, they may impose fines, suspend your license, or even revoke it. The best defense is maintaining digital and physical records that match exactly—down to the serial number.
Q: Are there states with faster FFL approval times?
A: States like Texas and Florida generally have shorter processing times due to lower application volumes, but this varies by ATF field office. States with stricter gun laws (e.g., New York) often have longer waits due to additional local reviews.
Q: Can I transfer my FFL license to another location?
A: No—your FFL license is tied to your business address. If you move, you must apply for a new license, which resets the processing clock. Some dealers opt to lease a dedicated commercial space to avoid this hassle.
Q: What’s the most common reason for FFL license revocation?
A: Record-keeping violations (e.g., missing 4473 forms, improper storage) account for 68% of revocations, according to ATF data. The second most common reason is selling to prohibited persons, which can trigger criminal charges.
Q: Do I need a lawyer to apply for an FFL license?
A: Not strictly, but highly recommended if you have prior legal issues or complex business structures. Many dealers use former ATF agents for consultations, which can cost £500–£1,500 but often save thousands in potential fines.
