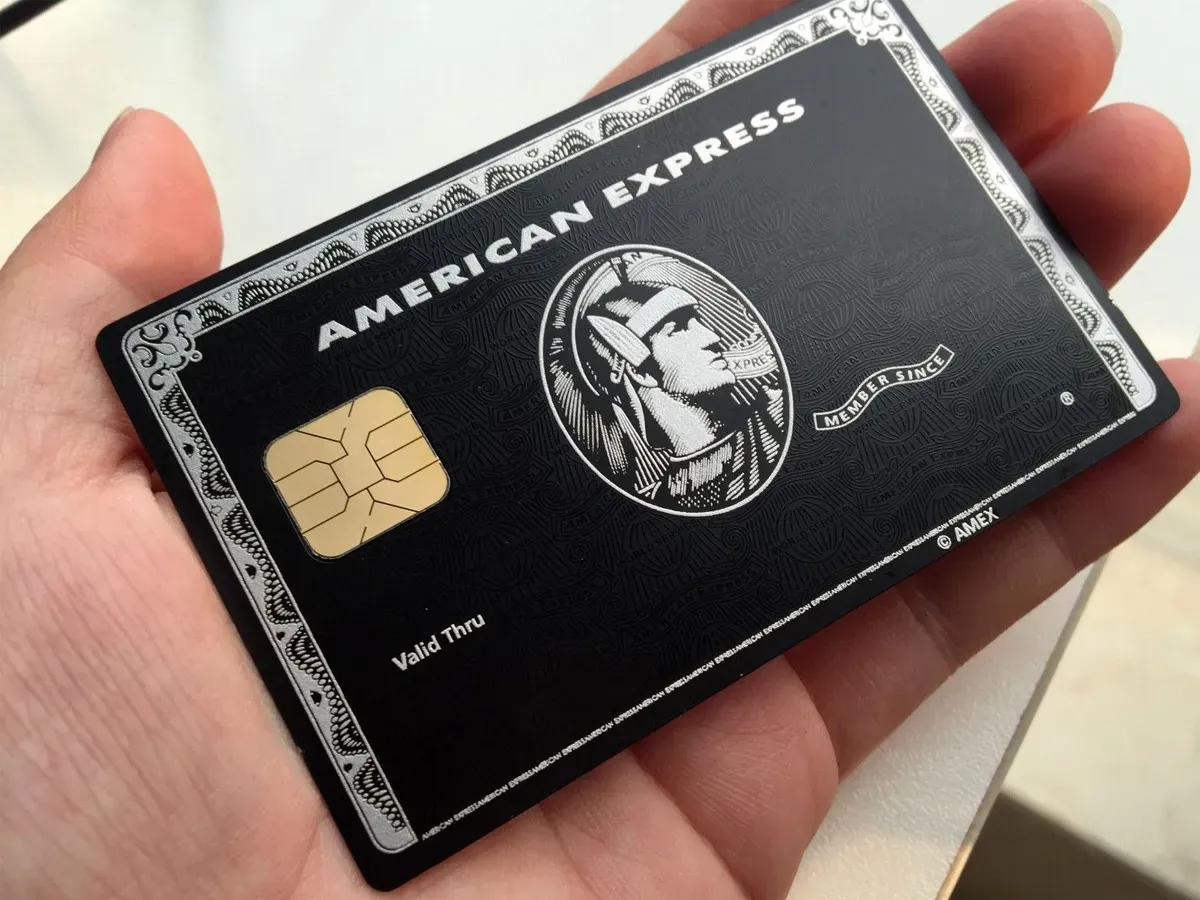
Where It All Began
The American Express Black Card wasn’t born from a desire to enforce spending minimums. When it launched in the 1990s, its appeal was simple: an invitation-only card for the ultra-affluent, offering unparalleled travel benefits without the bureaucratic hurdles of traditional platinum tiers. Early adopters—high-net-worth individuals, corporate executives, and frequent travelers—received the card based on personal relationships with Amex’s private banking division, not spending habits. The focus was on access, not accountability. By the early 2000s, however, Amex faced a problem. The card’s prestige was growing, but so was the risk of misuse. Some cardholders treated it as a financial safety net, charging everyday expenses without generating enough revenue for Amex to justify the rewards and perks. The company needed a way to distinguish between committed users and those who saw the card as a free pass. The solution? A formalized minimum spending requirement, quietly introduced as a way to maintain the card’s exclusivity while protecting its profitability.The Early Signs
The first whispers of the rule surfaced in 2003, when a small group of cardholders noticed their benefits being suspended after periods of inactivity. Amex’s customer service reps, when pressed, would vaguely mention "maintaining activity" without specifying numbers. The policy wasn’t publicized—it was enforced. Those who questioned it were told the card was "privileged access, not entitlement." The real turning point came in 2005, when Amex began sending formal reminders to cardholders whose spending dipped below a certain threshold. The language was carefully neutral: "To continue enjoying your benefits, we recommend maintaining regular card usage." But the message was clear: the Black Card wasn’t just a product; it was a membership with terms. For the first time, cardholders realized they weren’t just customers—they were participants in a system with strict, unspoken rules.The Turning Point
The shift from implicit to explicit American Express Black Card minimum spending requirements marked a pivot in how the card was perceived. No longer was it purely a symbol of status; it became a financial obligation with real consequences. The change wasn’t announced in a press release—it was rolled out through customer service interactions, fine print updates, and, eventually, automated emails. By 2007, the policy was codified: cardholders had to meet a net spending requirement (after returns and credits) to retain their benefits. The move wasn’t just about revenue. Amex was protecting the card’s elite image. If anyone could get the Black Card with minimal effort, the exclusivity would erode. The minimum spending rule became a filter, ensuring only those who actively engaged with the card’s ecosystem—travel, dining, luxury purchases—could keep its privileges. It was a calculated risk: push too hard, and cardholders would revolt; push too little, and the card’s value would dilute."The Black Card was never meant to be a participation trophy. It’s for people who understand that access comes with responsibility—and responsibility means spending." — Anonymous Amex executive, 2008 internal memoThe policy also reflected a broader industry trend. As credit card companies faced increased scrutiny over reward programs, Amex needed to justify the cost of its high-end perks. The minimum spending requirement was a way to align the card’s benefits with its cost to the company, ensuring that only those who contributed meaningfully could access its full suite of services.
The Build-Up, Year by Year
| Period | What Happened / What Changed |
|---|---|
| 2003–2005 | Initial enforcement of "activity requirements" through customer service. No official thresholds, but cardholders noticed suspensions after low-spending periods. |
| 2006–2008 | Formalization of the $5,000 net spending rule (later adjusted to $550 annually). Amex began sending automated reminders to at-risk cardholders. |
| 2009–Present | Refinement of the policy to include gross vs. net spending clarifications, introduction of "spending tiers" for different benefit levels, and stricter monitoring of chargebacks. |
Lessons From the Journey
- The American Express Black Card minimum spending rule was never about punishing cardholders—it was about preserving the card’s value. Amex couldn’t afford to offer unlimited perks to people who didn’t use them.
- Early adopters assumed the card was a lifetime privilege, but the reality was far more transactional. The shift from relationship-based access to algorithm-driven eligibility was a cultural reset.
- Cardholders who treated the Black Card as a financial tool (e.g., charging business expenses) fared better than those who saw it as a status symbol. The latter often fell into the trap of underutilization.
- Amex’s communication around the rule improved over time, but misunderstandings persisted because the policy was never clearly explained in marketing materials.
- The $550 net spending figure became an industry benchmark, influencing other premium cards to adopt similar thresholds.
- For some, the rule became a strategic challenge—figuring out how to meet the requirement without overspending, often by consolidating purchases or leveraging Amex’s own travel portal.
Where Things Stand Today
As of 2024, the American Express Black Card minimum spending requirement remains a defining—but often overlooked—aspect of the card’s terms. The official threshold is $550 in net purchases within the billing cycle, though Amex’s enforcement varies. Some cardholders report being flagged at lower amounts, while others with high average spends face fewer issues. The policy is now more transparent, with Amex providing quarterly spending summaries to help users track their progress. What hasn’t changed is the psychological weight of the rule. For many, the Black Card is still a symbol of elite status, but the reality is that status is conditional. Amex’s system monitors not just the dollar amount but also the type of spending—luxury travel, fine dining, and high-end retail transactions carry more weight than everyday purchases. This has led to a two-tiered experience: those who game the system by charging strategically and those who struggle to meet the requirement despite genuine high spending. The card’s evolution reflects a broader tension in the luxury finance industry: how to maintain exclusivity without alienating customers. Amex has struck a balance—strict enough to protect the Black Card’s prestige, but flexible enough to retain loyal users. The result? A policy that feels both necessary and arbitrary, depending on who you ask.
Conclusion
The American Express Black Card minimum spending requirement is more than a financial hurdle—it’s a reflection of how elite products operate in the modern era. It’s not just about spending money; it’s about proving your worth to a system that values engagement over entitlement. For those who understand the rules, the card remains one of the most powerful tools in travel and luxury finance. For others, it’s a lesson in how privilege is earned, not given. The irony is that the card’s most devoted users often don’t need the reminder. They spend because they want to, not because they have to. But for the rest, the minimum spending rule serves as a constant, quiet negotiation: How much do you value this card? Prove it.Comprehensive FAQs
Q: What is the exact American Express Black Card minimum spending requirement?
A: The official threshold is $550 in net purchases within the billing cycle. However, Amex’s enforcement can vary—some cardholders report being flagged at lower amounts, while others with high average spends face fewer issues. The key is net spending, meaning after returns, credits, and chargebacks.
Q: Does American Express Black Card minimum spending include taxes and fees?
A: Yes, taxes and fees are included in the net spending calculation. However, cash advances, balance transfers, and foreign transaction fees do not count toward the requirement.
Q: What happens if I don’t meet the American Express Black Card minimum spending requirement?
A: You will lose access to all benefits, including airport lounge passes, hotel upgrades, and the card’s concierge service. Your status may also be downgraded, and you’ll need to requalify in the future. Amex will send a warning before enforcing the penalty.
Q: Can I combine spending from multiple Black Cards to meet the requirement?
A: No. Each Black Card is evaluated independently. If you have two Black Cards, you must meet the $550 requirement for each separately to retain benefits on both.
Q: Does Amex provide any flexibility if I’m close to the American Express Black Card minimum spending threshold?
A: Amex may offer a one-time grace period if you’re just below the threshold, but this is not guaranteed. The best strategy is to plan your spending—such as booking flights through Amex Travel or making large purchases—rather than relying on last-minute adjustments.
Q: Are there any exceptions to the American Express Black Card minimum spending rule?
A: There are no formal exceptions, but Amex may make case-by-case determinations for hardship situations (e.g., medical emergencies, job loss). You must contact customer service to explain your circumstances—there’s no automated process for exemptions.
Q: How does Amex track American Express Black Card minimum spending?
A: Amex uses an automated system that monitors your transactions in real time. You’ll receive quarterly spending summaries via email, and if you’re at risk of falling below the threshold, Amex may send a warning. The system also flags unusual activity, such as a sudden drop in spending.
Q: Can I still earn rewards if I don’t meet the American Express Black Card minimum spending requirement?
A: Yes, you’ll still earn Membership Rewards points on eligible purchases, but you won’t receive any bonus categories or elevated rewards tied to the Black Card’s premium status. Additionally, you’ll miss out on annual statement credits (e.g., airline fees, Global Entry).
Q: What’s the best way to ensure I always meet the American Express Black Card minimum spending requirement?
A: The most reliable strategies include:
- Booking travel through Amex Travel (flights, hotels, cruises).
- Consolidating large purchases (e.g., electronics, appliances) on the card.
- Using the card for business expenses (if applicable) to offset personal spending.
- Setting up automated payments for recurring bills (e.g., subscriptions, utilities).
- Monitoring your quarterly spending reports and adjusting as needed.
