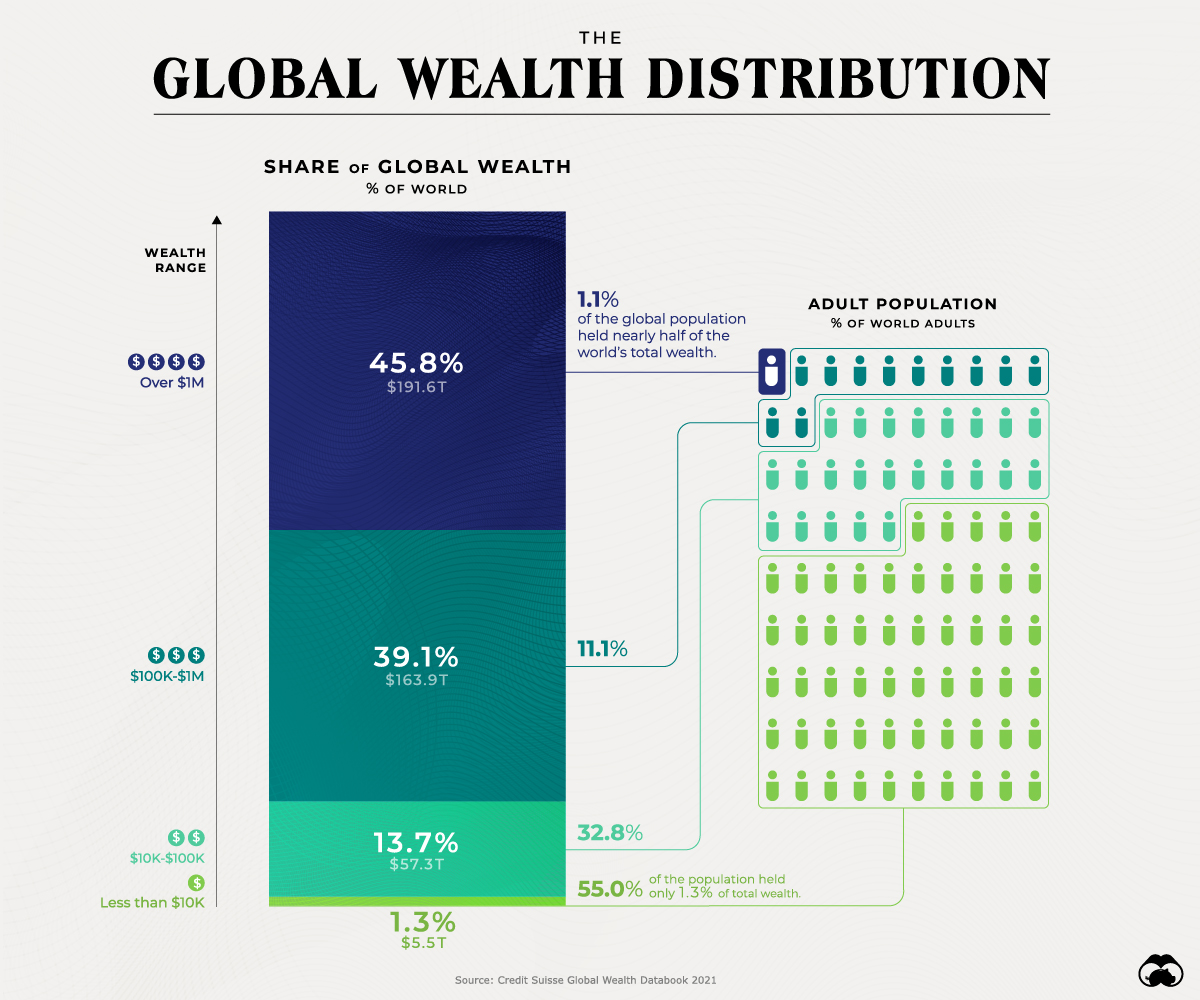
Breaking Down the Numbers
The numbers tell a story of concentration and control. According to Credit Suisse’s Global Wealth Report, the top 1% of adults held 64% of global wealth as of 2023, up from 43% in 2000. That’s not just growth—it’s structural dominance. The ultra-wealthy don’t just invest; they architect systems where wealth compounds across generations, insulated from inflation, currency devaluations, and even political instability. What’s less discussed is how this wealth is deployed. Traditional metrics—like the size of offshore accounts—miss the bigger picture. The real game is in asset location, where the choice of jurisdiction isn’t just about taxes but about legal enforceability, succession rules, and even cultural norms around inheritance. For example, a family might hold their primary residence in London (for lifestyle and stability) but title the underlying property through a Mauritius global business company (GBC), which offers creditor protection and no capital gains tax on disposals after two years.The Verified Baseline
Public filings and leaked documents—like the Pandora Papers and FinCEN Files—reveal patterns, not exceptions. The most common structures involve: 1. Trusts and foundations, particularly in Luxembourg, Liechtenstein, and the Cayman Islands, where they’re treated as separate legal entities with their own tax obligations (or lack thereof). 2. Private investment funds registered in Singapore, Delaware (for US exposure), or Guernsey, which allow for limited liability and pass-through taxation. 3. Real estate holding companies in Monaco, Panama, or the British Virgin Islands, where properties can be held anonymously or under corporate wrappers. The data is clear: global wealth strategy isn’t about hiding money—it’s about controlling the rules of the game. A 2022 study by the International Monetary Fund found that the wealthiest 0.1% of households use an average of three jurisdictions for their financial affairs, each serving a distinct purpose (tax, asset protection, succession).What the Estimates Suggest
Industry estimates paint a more aggressive picture. Private wealth managers suggest that top-tier clients—those with net worth exceeding $50 million—allocate 20-30% of their liquid assets to structures outside their home country. The remainder is split between domestic investments (for stability) and alternative assets like art, wine, or rare collectibles (where valuation and transfer are less scrutinized). Figures around the £500 billion range have been suggested for the total value of assets held in non-cooperative jurisdictions by European residents alone, though these numbers are speculative. What’s certain is that the ultra-wealthy are increasingly turning to "neutral" hubs like Switzerland, Hong Kong, and the UAE, where they can access global markets without the regulatory overreach of their home countries.
Case Study: A Closer Look
Consider the case of a European tech founder who built a $1.2 billion company in the early 2010s. His global wealth strategy unfolded in three phases: 1. Liquidity phase (2012-2015): He sold shares to a Delaware-based holding company, which then distributed proceeds to a Swiss private bank account structured under a discretionary trust. This allowed him to defer capital gains taxes while maintaining access to funds. 2. Diversification phase (2016-2019): As geopolitical risks rose, he shifted 25% of his net worth into Singapore-listed private equity funds and Dubai real estate (held via a Panamanian corporation). The Singapore funds provided access to Asian markets; Dubai offered 100% foreign ownership in certain sectors and no inheritance tax. 3. Legacy phase (2020-present): He established a Liechtenstein foundation to hold family assets, with trustees in Geneva and Hong Kong. This structure allows for multi-generational wealth transfer with minimal tax leakage, as Liechtenstein has no capital gains tax and strict privacy laws. The founder’s approach wasn’t about evasion—it was about optimization. His primary residence remained in Zurich, but his wealth was no longer monolithic. If Switzerland introduced new wealth taxes, he could pivot assets to Monaco or the Bahamas. If the EU tightened reporting rules, his Delaware entity could re-domicile to Cayman."The best wealth strategies aren’t about hiding money—they’re about making sure no single country can dictate the terms of your financial future." — Private wealth advisor, Zurich (2023)
| Factor | Estimated Impact |
|---|---|
| Jurisdictional diversity | Reduces systemic risk by ~40% compared to single-country exposure (industry estimates). |
| Trust/foundation structures | Can defer 30-50% of inheritance taxes over two generations (varies by country). |
| Private equity funds (Singapore/Dubai) | Access to emerging markets with limited liability and tax-deferred growth. |
| Real estate (Monaco/Panama) | Appreciation 2-3x faster than domestic markets in some cases, with no capital gains tax on disposals. |
What This Means Going Forward
The next decade will test the limits of global wealth strategy. Three trends are reshaping the landscape: 1. Automated tax transparency (like OECD’s CRS) is closing loopholes, but the ultra-wealthy are adapting by using "compliant complexity"—structures that meet reporting requirements while still delivering tax benefits. 2. Digital assets (crypto, NFTs, tokenized real estate) are emerging as unregulated wealth stores, though their volatility remains a wild card. 3. Geopolitical fragmentation—US-China tensions, EU sovereignty moves—means neutral hubs (Singapore, Switzerland, UAE) will gain importance as default jurisdictions for cross-border families. The shift is from static wealth preservation to dynamic wealth mobility. The families who thrive will be those who treat their global wealth strategy as a living system, not a fixed plan.
Conclusion
Global wealth isn’t just about money—it’s about control. The most successful strategies aren’t the ones that exploit loopholes but those that anticipate regulatory shifts, leverage asymmetry, and ensure continuity across generations. The days of simple offshore accounts are over. Today’s global wealth strategy demands a mix of legal precision, financial flexibility, and geopolitical awareness. For the rest of us, the takeaway isn’t just envy—it’s a lesson in structural thinking. Wealth, at scale, isn’t held; it’s orchestrated.Comprehensive FAQs
Q: Is a global wealth strategy only for billionaires?
A: No—though the tools are more accessible to high-net-worth individuals (typically $5M+), diversification across jurisdictions can benefit anyone with significant assets. For example, a $2M portfolio could split holdings between a US brokerage account, a Singapore REIT, and a Swiss bank account for currency diversification. The key is risk mitigation, not just tax savings.
Q: Are trusts and foundations the only options?
A: Far from it. Alternatives include: - Private investment funds (for illiquid assets like private equity). - Real estate investment trusts (REITs) in low-tax jurisdictions. - Insurance-based structures (like Singapore’s private cell insurance), which can hold assets outside traditional banking systems. The best choice depends on liquidity needs, succession goals, and regulatory comfort.
Q: How do digital assets fit into a global wealth strategy?
A: Digital assets (crypto, tokenized real estate, private equity tokens) are still high-risk, but they offer borderless transfer and potential tax advantages in jurisdictions like Portugal (0% capital gains on crypto after 1 year) or Dubai (0% tax on profits). The challenge is volatility and regulatory uncertainty—most advisors recommend allocating no more than 5-10% of a diversified portfolio to digital assets.
Q: What’s the biggest mistake people make with global wealth?
A: Overcomplicating it. The most effective strategies are simple but robust—think of them as financial Swiss Army knives, not Rube Goldberg machines. Common pitfalls include: - Ignoring succession rules (e.g., assuming a trust in one country will hold in another). - Underestimating currency risk (holding too much in a single currency). - Chasing "secret" jurisdictions instead of focusing on legal certainty and liquidity. The best global wealth strategy is one that works in daylight, not one that relies on secrecy.
