
Where It All Began
The story of the largest auction houses in the world starts not with a grand auction but with a simple idea: that objects, once owned, could be reclaimed by the highest bidder. In 1744, Samuel Baker, a London bookseller, hosted the first recorded auction of books and prints, a modest affair that laid the groundwork for what would become Sotheby’s. The business expanded slowly, but by the late 18th century, it had begun to attract more than just scholars—collectors with deeper pockets. The shift from selling books to selling fine art marked the turning point, as the house realized that the most valuable objects weren’t just knowledge but also beauty, rarity, and the patina of history. Christie’s, founded in 1766 by James Christie, took a different path. While Sotheby’s began with books, Christie’s was from the outset an auctioneer’s enterprise, specializing in high-value items. The two houses would later become rivals, their battles over major lots—like the 1987 sale of Van Gogh’s Irises—becoming legendary. But their early years were defined by one critical factor: the rise of the British aristocracy. As dukes and earls liquidated estates during the Industrial Revolution, the auction houses became the primary market for their treasures. This period cemented the idea that auctions weren’t just transactions but cultural events, where the elite could display their taste—and their wealth.The Early Signs
By the 19th century, the largest auction houses in the world had begun to operate like financial institutions. Christie’s, for instance, expanded into continental Europe, while Sotheby’s opened branches in Paris and New York. The key innovation wasn’t the auction itself but the infrastructure around it: catalogs that functioned as marketing tools, private sales that kept wealthy clients engaged, and a growing network of experts who could authenticate and appraise works. These houses didn’t just sell art; they sold confidence in the art market itself. The American entrance of both firms in the early 20th century was pivotal. New York emerged as the third pole of the auction world, alongside London and Paris, thanks to the rise of American collectors like J.P. Morgan and the Guggenheims. The Great Depression temporarily stalled growth, but the post-WWII era saw a resurgence, driven by the Marshall Plan’s infusion of wealth into Europe and the growing disposable income of American industrialists. The largest auction houses in the world had evolved into global players, their reach extending from Manhattan to Monaco.The Turning Point
The 1980s marked the moment when the largest auction houses in the world stopped being mere facilitators of sales and became active shapers of the art market. The decade began with a bang: in 1987, Christie’s sold Van Gogh’s Irises for a then-unthinkable $53.9 million, a figure that sent shockwaves through the industry. The sale wasn’t just about the price—it was about the message. Art was no longer a luxury; it was an investment. Banks began offering loans against art, and collectors started treating masterpieces like stocks. This shift was mirrored in the houses’ internal strategies. Sotheby’s, under the leadership of Dick Snyder, embraced aggressive expansion, acquiring rival firms and diversifying into real estate and financial services. Christie’s, meanwhile, doubled down on its reputation for exclusivity, courting the world’s wealthiest families with private sales and bespoke services. The result was a two-pronged approach: mass-market auctions to drive volume, and high-net-worth clients to drive prestige.“Auction houses don’t just sell art—they sell the idea of art’s value. And in the 1980s, we learned that if you can convince the world a painting is worth more than it was yesterday, you can keep raising the ceiling.” — Anonymous senior executive at a major auction house, 1995The turning point wasn’t just about money, though. It was about the realization that the largest auction houses in the world could influence cultural narratives. A single auction could elevate an artist from obscurity to immortality—or bury them under a mountain of debt if the sale flopped. The houses became arbiters of taste, their catalogs functioning as curated histories of what was “important” at any given moment.

The Build-Up, Year by Year
| Period | Key Developments |
|---|---|
| 1990s |
|
| 2000s |
|
| 2010s |
|
| 2020s |
|
Lessons From the Journey
- The duopoly is fragile. Despite their dominance, Christie’s and Sotheby’s must constantly innovate to fend off challengers like Phillips, which has carved out a niche in specialized auctions.
- Private sales are the real money-makers. While headline-grabbing auctions draw attention, the bulk of high-value transactions happen behind closed doors, often with no public record.
- Geopolitics dictates the market. Sanctions, currency fluctuations, and political instability (e.g., Russia’s invasion of Ukraine) can freeze entire segments of the market overnight.
- Reputation is everything. A single failed auction or authenticity scandal can erode trust faster than any PR campaign can rebuild it.
Where Things Stand Today
The largest auction houses in the world are currently at a crossroads. On one hand, they’ve never been more profitable. Christie’s reported revenues of over $5 billion in 2022, while Sotheby’s followed closely behind, with both firms benefiting from a post-pandemic surge in luxury spending. The houses have also expanded their offerings beyond fine art, now handling everything from rare wines to vintage cars, ensuring that no matter the economic climate, there’s always a market for something. Yet challenges loom. The rise of alternative platforms (like Artnet’s private sales arm) threatens their monopoly, while environmental concerns—auction houses are notorious for their carbon footprint—are forcing them to rethink logistics. Additionally, the next generation of collectors, raised on digital-native platforms, may not share the same reverence for physical auctions. The largest auction houses in the world must now decide whether to lean into technology or double down on tradition. The answer will determine whether they remain untouchable—or just another relic of the old economy.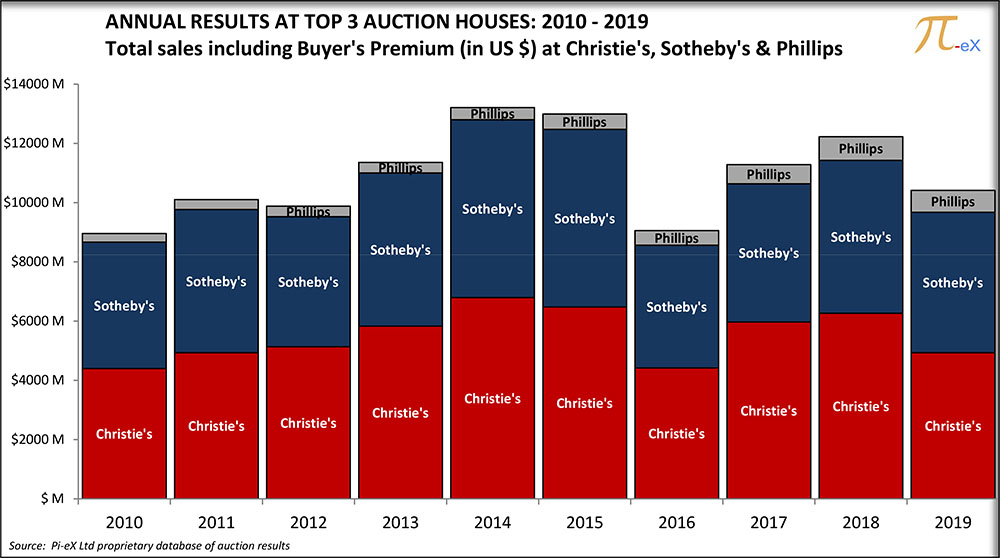
Conclusion
The auction house model has endured for nearly 300 years because it solves a fundamental problem: how to assign value to the intangible. Whether it’s a Rembrandt or a rare first-edition book, the largest auction houses in the world provide a rare intersection of liquidity and legitimacy. But their power isn’t just economic—it’s cultural. These institutions don’t just reflect society’s tastes; they shape them, deciding which artists enter the canon and which fade into obscurity. The future of the auction world will likely be defined by two forces: the relentless march of technology and the unyielding demand for exclusivity. If the largest auction houses in the world can navigate these currents without losing their soul, they’ll continue to thrive. If they fail, they risk becoming just another chapter in the history of how wealth changes hands—rather than the architects of that change.Comprehensive FAQs
Q: Which auction house has the highest market share globally?
Christie’s and Sotheby’s together control roughly 70-80% of the global fine art auction market, with Christie’s often leading in high-value sales. Phillips, Bonhams, and smaller regional houses make up the remainder, focusing on niche segments like Asian art or watches.
Q: How do private sales differ from public auctions?
Private sales occur off-market, often brokered directly between the auction house and a client. They offer discretion, higher commissions (sometimes 10-12%), and no bidding wars—but also no public record of the sale price. Public auctions, while more transparent, come with fees (buyer’s premiums up to 25%) and the risk of underbidding.
Q: Can anyone bid at a major auction, or is it invitation-only?
Public auctions are theoretically open to anyone, but the reality is more complex. High-value lots often require pre-approval for credit checks, and some houses reserve seats for preferred clients. For truly exclusive sales, invitations are sent based on past purchasing history or connections.
Q: What happens if no one bids on a lot?
If a lot fails to sell at auction, the auction house typically absorbs it into its inventory or offers it to pre-approved buyers in a “buy-in” process. In extreme cases, the seller may be left holding the unsold item, though most contracts include clauses to mitigate this risk.
Q: How do auction houses authenticate artworks?
Authentication is a mix of expertise, provenance research, and sometimes controversy. Major houses employ in-house specialists, consult external experts, and rely on historical documentation. However, disputes—like those surrounding Jackson Pollock or Cy Twombly—remain common, with some works selling for vastly different prices based on contested authenticity.
Q: Are there auction houses specializing in non-art categories?
Yes. Bonhams focuses on antiques and collectibles, Phillips on contemporary art, and specialized firms like RR Auction (watches) or Ketterer (prints) cater to niche markets. Even Christie’s and Sotheby’s now handle everything from cars to wine, though fine art remains their core business.
Q: How do economic downturns affect auction house revenues?
Recessions typically lead to a drop in high-end sales, but auction houses adapt by targeting mid-tier collectors or diversifying into luxury goods. The 2008 financial crisis, for example, saw a 30% decline in fine art auctions, but revenues rebounded within five years as wealth inequality widened and new collectors emerged.
