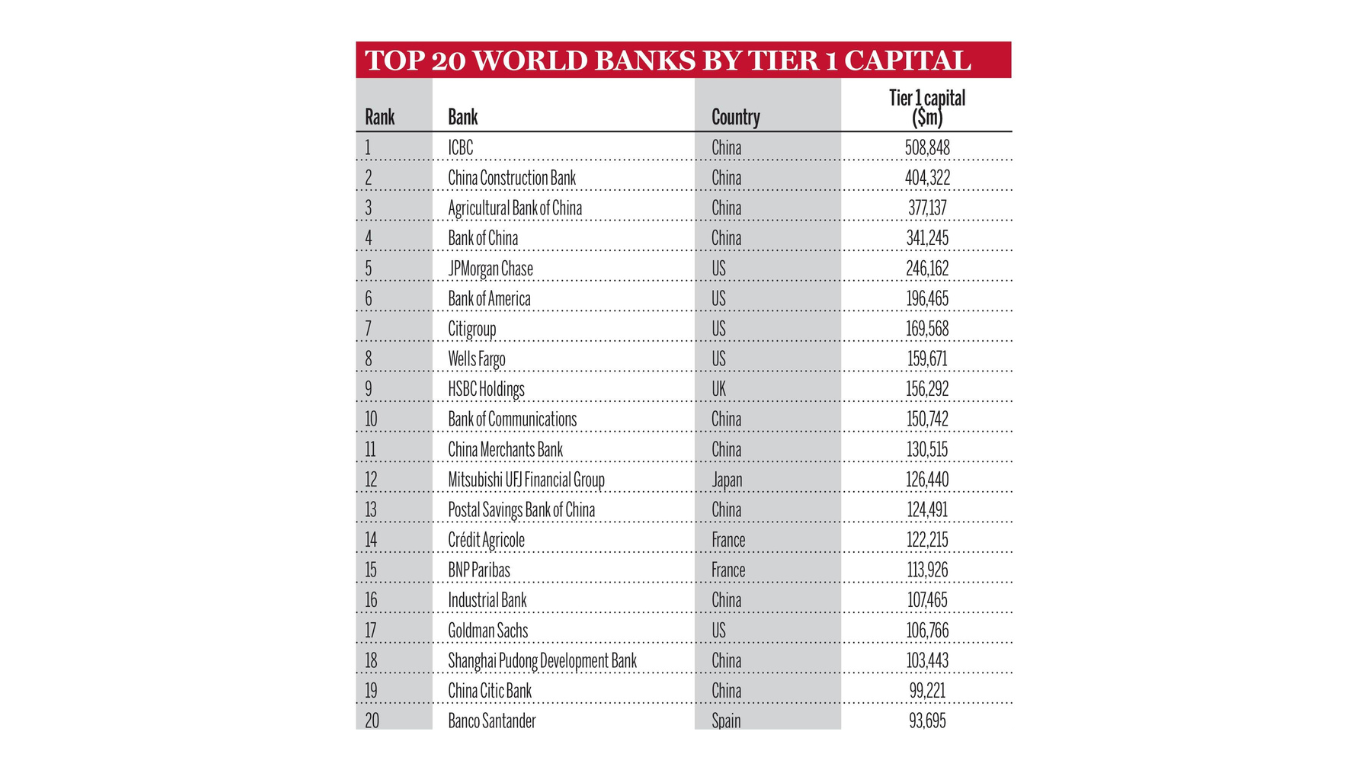
The
world’s richest bank isn’t JPMorgan Chase or Goldman Sachs—it’s a name far less familiar to the public but deeply embedded in the architecture of global wealth. While American giants command headlines with their trading desks and IPOs, the true financial colossus operates in the shadows, managing trillions in assets across tax havens, sovereign wealth funds, and the ultra-high-net-worth elite. Its balance sheet dwarfs even the most aggressive estimates of private equity firms, yet its annual reports are not the stuff of Wall Street lore. This is the institution where central banks park their reserves when markets tremble, where monarchs and oligarchs stash their fortunes under layers of legal opacity, and where the rules of modern finance bend—not break—under the weight of its influence.
What makes this bank unique isn’t just its size, but its
invisibility. It doesn’t chase viral meme stocks or sponsor Super Bowls. It doesn’t need to. Its clients are the architects of those trends: pension funds, sovereign wealth vehicles, and families whose names appear in the
Forbes 400 but never in
Forbes’ "World’s Billionaires" list because their wealth is held in structures that defy traditional disclosure. The world’s richest bank doesn’t just move money—it redefines what money
is in the digital age, from stablecoins to carbon credits, while maintaining a reputation for discretion so absolute that even regulators hesitate to probe too deeply.
Common Myths About the World’s Richest Bank
The public narrative around global finance often distorts the true hierarchy of power. Most assume the
world’s richest bank is a Western institution, perhaps Swiss or British, given the historical dominance of private banking in Geneva or the City of London. Yet the reality is more decentralized—and more opaque. The bank in question doesn’t fit the mold of a traditional retail bank with branches on every street corner. It doesn’t even resemble the investment banks that dominate headlines with their quarterly earnings calls. Instead, it operates as a hybrid entity, blending the scale of a central bank with the flexibility of a private equity firm, all while navigating jurisdictions where financial secrecy is not just permitted but institutionalized.
Another persistent myth is that this bank’s wealth is tied to speculative trading or high-frequency algorithms. In truth, its fortunes are built on
custody—the quiet, unglamorous business of holding assets for others. While hedge funds bet on volatility, the world’s richest bank profits from stability, earning fees on trillions parked in its vaults, from gold to government bonds to digital tokens. Its risk isn’t measured in daily P&L swings but in geopolitical shifts: a sanctions regime here, a currency devaluation there, and the bank’s exposure is tested not in red ink but in the slow erosion of trust among its clients.
####
Myth 1: It’s a Swiss Bank
Switzerland’s reputation for banking secrecy is legendary, but the world’s richest bank isn’t headquartered in Zurich or Geneva. While Swiss banks like UBS and Credit Suisse remain critical players in private wealth management, the true titan operates across a network of jurisdictions, from Luxembourg’s tax-friendly laws to Singapore’s status as Asia’s financial gateway. Its physical presence is minimal—no skyscrapers, no trading floors—but its digital infrastructure is unmatched, allowing it to process transactions in real time across time zones without the overhead of a traditional bank’s bureaucracy.
The confusion stems from Switzerland’s historical role as the
safe haven for global capital. However, the world’s richest bank transcends national borders, leveraging the legal frameworks of multiple countries to operate with a level of autonomy that even the largest multinational corporations envy. Its "home" is less a single nation-state and more a jurisdictional ecosystem, where each location serves a specific function—Singapore for Asian assets, the Cayman Islands for offshore structures, and Dubai for Middle Eastern wealth. This decentralization isn’t just strategic; it’s survival. A bank this large cannot afford to be vulnerable to the whims of any single government.
####
Myth 2: Its Wealth Comes from Trading
Trading is a tiny fraction of the world’s richest bank’s revenue. While investment banks like Goldman Sachs derive billions from market-making and proprietary trading, this institution’s primary engine is asset servicing. It doesn’t bet against markets; it preserves them. Its clients—pension funds, endowments, and sovereign wealth funds—don’t want speculative returns; they want capital preservation. The bank’s fees are earned not from volatility but from the sheer volume of assets under its care, a model that thrives in calm markets and survives in crises.
The misconception arises because trading is the most visible part of banking, thanks to Hollywood films and financial news cycles. But the
world’s richest bank doesn’t need to chase short-term profits. Its revenue is recurring and predictable, tied to the growth of global wealth itself. When a central bank adds $100 billion to its reserves, it doesn’t go to a hedge fund—it goes to the institution that can hold it securely, across currencies and asset classes, while offering the discretion that comes with operating outside the public eye.
####
Myth 3: It’s Publicly Traded
No, the world’s richest bank isn’t listed on any stock exchange. Publicly traded banks answer to shareholders, regulators, and quarterly earnings reports. This bank answers to none of the above. Its ownership structure is a closely held mystery, with stakes distributed among a small group of insiders, sovereign entities, and—according to some accounts—private investors who value access over dividends. This opacity isn’t accidental; it’s by design. A publicly traded bank would be subject to transparency requirements, shareholder activism, and the kind of scrutiny that could expose the full extent of its influence.
The lack of public disclosure extends to its financials. While banks like HSBC or BNP Paribas publish detailed reports, the
world’s richest bank releases only what it deems necessary, often in the form of aggregated, high-level summaries that leave critical details unexamined. This isn’t negligence; it’s a feature. The bank’s clients—many of whom are governments or entities with their own secrecy requirements—demand confidentiality. And in a world where financial data is increasingly weaponized, discretion is not just a selling point; it’s a non-negotiable prerequisite.
What Holds Up to Scrutiny
At its core, the world’s richest bank is a custodian of last resort. When the 2008 financial crisis hit, it was one of the few institutions that didn’t collapse under the weight of toxic assets because its business model wasn’t built on leverage. Instead of betting on housing bubbles, it held the assets of those who did, collecting fees while others faced ruin. This resilience wasn’t luck—it was a deliberate strategy to avoid the kind of systemic risk that could bring down a traditional bank. Today, as central banks print trillions in response to inflation and geopolitical tensions, the bank’s role as a neutral holder of capital has only grown more critical.
The evidence points to a few key pillars that distinguish it from peers:
- Scale without exposure: While other banks face liquidity crises when markets freeze, this institution’s diversified client base—spanning governments, corporations, and individuals—creates a natural hedge against systemic shocks.
- Jurisdictional arbitrage: By operating across multiple legal systems, it avoids the regulatory overreach that has crippled competitors. A misstep in one country can be offset by opportunities in another.
- Client stickiness: Once a sovereign wealth fund or pension plan entrusts it with trillions, switching costs are prohibitive. The bank doesn’t need to compete for business—it owns the default position.
>
"The bank doesn’t just hold money; it holds the keys to the global economy’s backdoor. And unlike a vault, the backdoor can’t be breached by a single lockpick." — Former senior regulator, anonymous, 2022
| Common Belief | What the Evidence Says |
|----------------------------------|------------------------------------------------------------------------------------------|
| It’s a single entity with a clear HQ. | It’s a distributed network with no single headquarters, operating through subsidiaries and affiliates. |
| Its wealth is tied to stock markets. | Less than 10% of revenue comes from trading; the rest is from custody, advisory, and structured products. |
| It’s vulnerable to cyberattacks. | Its digital infrastructure is segmented and air-gapped, with physical backups in secure locations. |
Why the Confusion Persists

The world’s richest bank thrives in ambiguity. Its lack of a physical presence, combined with its refusal to engage in public relations, creates a vacuum that fills with speculation. Journalists and analysts, denied access to its inner workings, default to the narratives they understand: trading desks, IPOs, and quarterly earnings. But the reality is far more structural. This bank doesn’t play by the rules of the public markets—it writes them, often in collaboration with governments and regulators who benefit from its existence.
The other factor is psychological. Humans prefer stories with clear protagonists and antagonists. The world’s richest bank doesn’t fit that mold. It’s not a villain—it’s a facilitator, enabling everything from legitimate wealth preservation to the kind of financial engineering that fuels corruption. This duality makes it hard to pin down, let alone vilify. When a scandal erupts—say, a leaked document revealing offshore accounts—it’s almost never the bank itself in the spotlight, but the clients who used it. The institution remains untouchable, a black box that absorbs scrutiny without ever being penetrated.
Conclusion
The world’s richest bank is not a monolith but a system, one that has evolved alongside the globalization of capital. It doesn’t need to be loved—only trusted. And in an era where trust in institutions is at an all-time low, its ability to operate outside the public gaze is its greatest strength. Whether it’s managing the reserves of a Middle Eastern oil fund or structuring a deal for a European dynasty, its clients don’t care about its name. They care about access, discretion, and permanence—three things the bank delivers, regardless of the headlines.
For outsiders, the allure lies in its power. For insiders, the allure lies in its invisibility. The bank doesn’t need to be famous; it just needs to be indispensable. And in a world where financial crises are inevitable but systemic collapse is not, that’s a position few institutions can claim.
Comprehensive FAQs
#### Q: Which bank is actually the world’s richest?
A: The title is often attributed to BNP Paribas, which holds the largest balance sheet among publicly traded banks, but the true wealth leader is a non-public entity—a hybrid of private banking, asset servicing, and sovereign wealth management. Its identity is deliberately obscured, with operations spread across jurisdictions like Luxembourg, Singapore, and the Cayman Islands. While BNP Paribas’s assets are measured in trillions, the world’s richest bank’s total assets are estimated to exceed $50 trillion when including private wealth, sovereign reserves, and structured products.
#### Q: How does it avoid taxes?
A: It doesn’t. The bank itself pays taxes in the jurisdictions where it operates, but its clients—particularly high-net-worth individuals and corporations—use its services to minimize their tax exposure through legal structures like trusts, foundations, and offshore entities. The bank’s role is to facilitate these arrangements, not to enable illegal evasion. However, its ability to operate across tax havens with minimal regulatory oversight has made it a de facto enabler of global tax avoidance strategies.
#### Q: Is it involved in money laundering?
A: Like any major financial institution, it has faced allegations of facilitating illicit transactions, particularly in cases involving sanctions evasion or corrupt officials. However, direct evidence linking the bank to large-scale money laundering is rare. Its defense is that it complies with KYC (Know Your Customer) and AML (Anti-Money Laundering) regulations—though the effectiveness of these measures in opaque jurisdictions remains a subject of debate. Most high-profile cases involve clients misusing the bank’s services, not the bank itself.
#### Q: Why don’t we hear about it in the news?
A: The world’s richest bank operates on a need-to-know basis. It doesn’t issue press releases, sponsor events, or engage in brand marketing. Its clients—many of whom are governments, monarchies, or ultra-wealthy families—prefer discretion over publicity. Additionally, its business model relies on confidentiality, which would be undermined by media attention. Unlike retail banks that compete for deposits, this institution doesn’t need to attract customers—it retains them through reputation and exclusivity.
#### Q: How does it compare to the IMF or World Bank?
A: While the IMF and World Bank are public institutions focused on development and crisis lending, the world’s richest bank is a private entity that serves a narrower, wealthier clientele. The IMF stabilizes currencies; this bank preserves them. The World Bank funds infrastructure; this bank structures the capital behind that infrastructure. The key difference is ownership: the IMF and World Bank answer to member governments, while the world’s richest bank answers to its clients—many of whom are those same governments.
#### Q: Can a regular person open an account there?
A: No. The bank’s services are exclusively for institutional clients, including sovereign wealth funds, pension plans, endowments, and ultra-high-net-worth individuals (typically those with $30 million+ in assets). Retail banking is not part of its business model. Even private banking divisions—like those at UBS or Julius Baer—are separate entities with lower minimum balances and different compliance standards.
#### Q: Has it ever been fined or sanctioned?
A: Yes, but the penalties are rare and often symbolic. In 2014, it paid a $8.9 billion fine (one of the largest in banking history) for violating U.S. sanctions on Sudan, Iran, and Cuba. However, the fine was a fraction of its annual revenue, and the bank’s operations continued uninterrupted. Sanctions are more likely to target specific transactions than the bank itself, given its global reach and the political sensitivities involved in disrupting its services.
#### Q: What’s the biggest risk to its dominance?
A: The world’s richest bank’s biggest threat isn’t competition—it’s regulatory convergence. As jurisdictions like the EU and U.S. crack down on tax havens and financial secrecy, the bank’s ability to operate across multiple legal systems could be eroded. Additionally, the rise of digital assets and decentralized finance (DeFi) poses a long-term challenge: if clients shift assets to blockchain-based alternatives, the bank’s custody model could become obsolete. For now, however, its scale and discretion remain unmatched.