
Where It All Began
The concept of a personal financial statement net worth paper traces back to the 19th century, when banks and insurance underwriters first demanded proof of solvency. Before spreadsheets, wealthy families handwrote ledgers in leather-bound books, listing land deeds, gold reserves, and even livestock. These weren’t just records—they were status symbols. A merchant’s net worth statement could make or break a business partnership in a single meeting. The document’s evolution mirrored the rise of modern capitalism: what started as a tool for aristocrats became a necessity for the middle class as credit expanded. By the mid-20th century, the financial net worth statement had standardized into the format we recognize today—two columns, assets on one side, liabilities on the other, a net worth figure at the bottom. The U.S. Internal Revenue Service codified its use in tax filings, and accounting firms began offering templates to clients. The shift from handwritten ledgers to printed forms reflected a broader cultural change: finance was no longer the domain of the elite. It was now a personal responsibility, documented in black and white. Yet even as the document became ubiquitous, its true purpose—beyond compliance—was often overlooked.The Early Signs
The first cracks in the system appeared when people realized the personal financial statement net worth paper could be weaponized. Divorce attorneys discovered that hidden assets, or strategically undervalued liabilities, could alter settlements overnight. Lenders used net worth statements to deny loans not based on income, but on the illusion of wealth. Meanwhile, the ultra-wealthy began treating these documents as negotiable artifacts—sometimes inflating values to secure better terms, other times burying them to avoid scrutiny. The real turning point came in the 1980s, when personal computers democratized financial tracking. Software like Quicken allowed individuals to generate their own net worth statements, bypassing the gatekeepers of banks and accountants. Suddenly, the document wasn’t just a passive record—it became a dynamic tool for self-assessment. The shift from static paper to interactive data marked the beginning of financial transparency as a personal power play.The Turning Point
The collapse of the dot-com bubble in 2000 forced a reckoning. Thousands of entrepreneurs, their net worth statements inflated by stock options and unsecured loans, found themselves overnight with liabilities far exceeding assets. The crisis exposed a harsh truth: a personal financial statement net worth paper wasn’t just a snapshot—it was a stress test. Those who had treated it as a static document faced ruin, while those who monitored it closely could pivot before the crash. The aftermath saw a surge in financial literacy programs, but the real change was cultural. Millennials, raised on the ashes of 2008, approached net worth statements with skepticism. They demanded more than just numbers—they wanted context. Why was their student loan debt classified as an asset? How did their side hustle income affect their liquidity? The document, once a dry ledger, now had to tell a story."A net worth statement isn’t just a balance sheet—it’s a confession. It says, ‘This is what I own, this is what I owe, and this is what I’m willing to risk.’ The problem is, most people never read it until it’s too late." — A former Big Four audit partner, speaking off-record
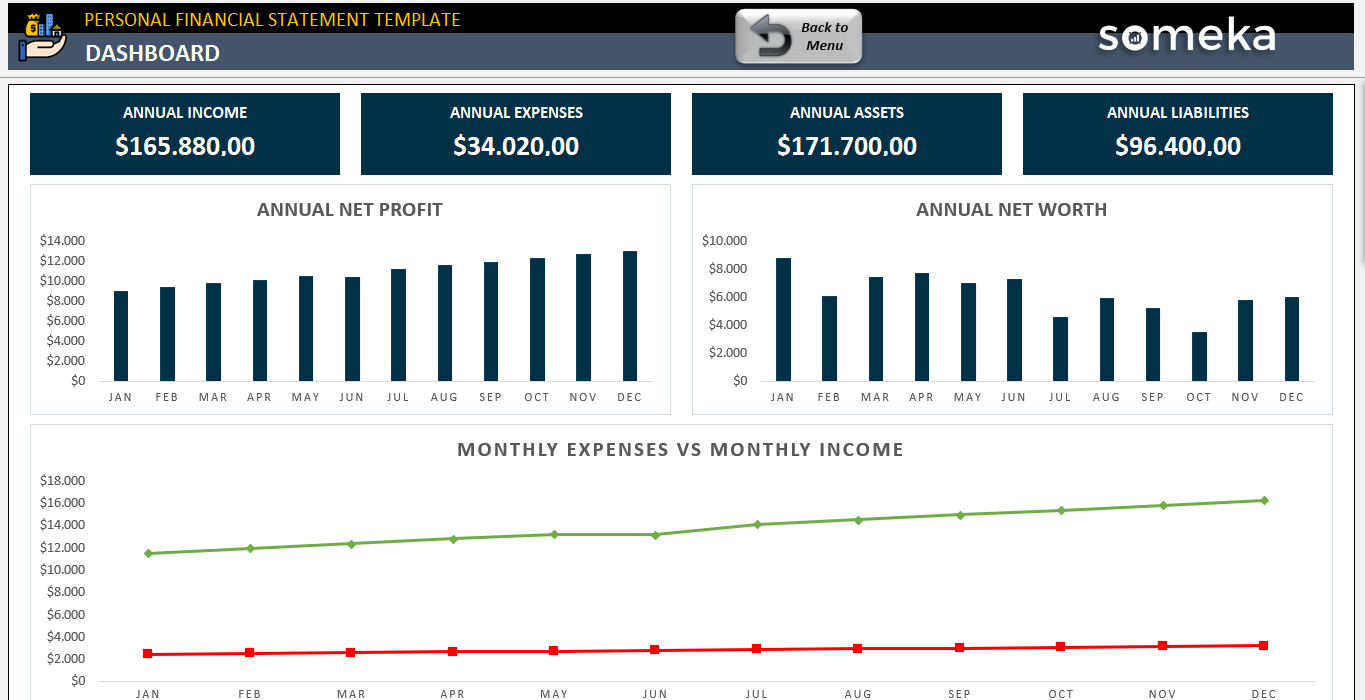
The Build-Up, Year by Year
| Period | What Happened |
|---|---|
| 1990s | Banks introduce standardized personal financial statement net worth papers for mortgage approvals. The rise of home equity loans makes net worth a collateralizable asset. |
| 2005–2007 | Subprime lending explodes. Borrowers with inflated net worth statements secure loans based on paper wealth, not cash flow. The document becomes a tool of speculation. |
| 2010–2015 | Post-recession, fintech apps (Mint, Personal Capital) automate net worth tracking. The financial net worth statement shifts from annual to real-time monitoring. |
| 2018–2020 | Cryptocurrency and gig economy income complicate traditional net worth statements. Accountants scramble to classify volatile assets like Bitcoin and Airbnb rental income. |
| 2023–Present | AI-driven tools generate personalized net worth projections. The personal financial statement net worth paper evolves into a predictive dashboard, not just a historical record. |
Lessons From the Journey
- Net worth isn’t static. A document frozen in time is a liability. The most successful individuals treat their financial net worth statement as a living document, updated monthly.
- Debt isn’t always the enemy. A mortgage or student loan can be a strategic liability if it fuels income-generating assets. The statement’s power lies in how it’s framed.
- Transparency is a competitive advantage. Partners, investors, and even future selves benefit from an accurate personal financial statement net worth paper. Hiding assets only works until it doesn’t.
- The best statements tell a story. Numbers alone don’t explain why someone holds a particular asset or takes a specific risk. The narrative behind the statement matters more than the figures themselves.
Where Things Stand Today
Today, the personal financial statement net worth paper exists in three forms: the official version for banks and tax filings, the personal version for self-tracking, and the "shadow" version—often undocumented—that reflects real-time financial health. The official version remains a compliance tool, but the personal and shadow versions have become the real drivers of decision-making. Apps like YNAB and Wealthfront now generate dynamic net worth statements that adapt to spending habits, market fluctuations, and even emotional triggers. The biggest shift? The document is no longer just about what you own—it’s about what you can own. Algorithmic lenders now use net worth data to predict future behavior, not just past performance. A high net worth statement might get you a loan, but a consistent upward trend gets you better terms. The game has changed: it’s not enough to have wealth on paper. You need to prove you’re building it right now.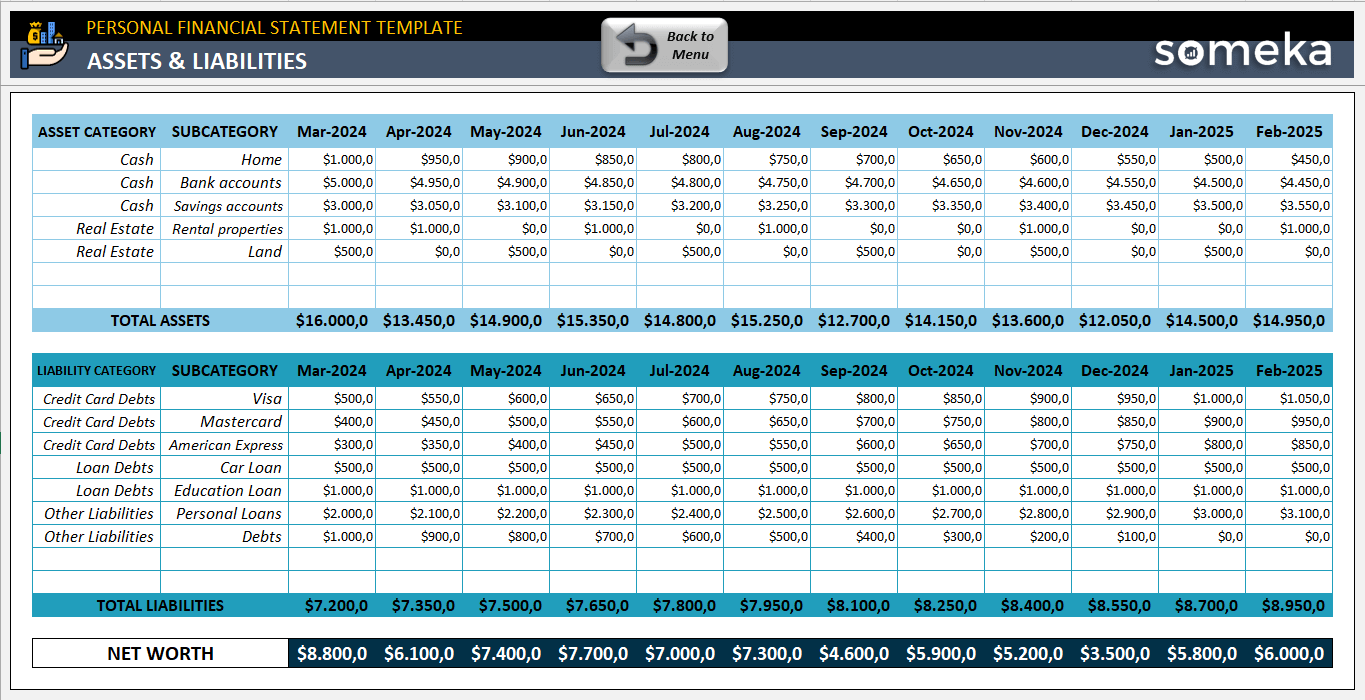
Conclusion
The personal financial statement net worth paper is the original financial selfie—a raw, unfiltered look at where you stand. Its value isn’t in the ink or the pixels, but in the discipline it demands. The people who thrive aren’t the ones who ignore it; they’re the ones who use it to ask the right questions. How much of my net worth is tied to illiquid assets? What would happen if my biggest liability disappeared? The answers shape everything from daily spending to life-altering moves. Yet for all its power, the document remains misunderstood. It’s not a trophy to display or a problem to avoid—it’s a mirror. The best financial plans start with a clear, unvarnished financial net worth statement, not wishful thinking. The rest is just execution.Comprehensive FAQs
Q: Do I need a professionally prepared personal financial statement net worth paper?
A: Only if you’re applying for high-value loans, seeking investment, or facing legal/tax scrutiny. For personal tracking, DIY tools like spreadsheets or apps suffice. The key is consistency—even a rough draft is better than nothing.
Q: How often should I update my net worth statement?
A: Monthly for active management, quarterly for passive tracking. Major life events (marriage, inheritance, job changes) warrant immediate updates. Ignoring fluctuations risks outdated decisions.
Q: Can I exclude certain assets from my net worth statement?
A: Technically, yes—but strategically, no. Excluding assets (e.g., off-book cash, undervalued collectibles) may help short-term goals, but it undermines long-term trust. Transparency builds credibility with lenders, partners, and even yourself.
Q: What’s the difference between a net worth statement and a balance sheet?
A: They’re functionally the same, but "net worth statement" is the personal finance term, while "balance sheet" is the accounting term. The structure is identical: assets minus liabilities equals net worth. The difference lies in audience—one for banks, one for you.
Q: How do I handle volatile assets (crypto, stocks) in my statement?
A: List them at current market value for accuracy, but note volatility in a separate section. Over time, track trends rather than daily swings. The goal is to see patterns, not react to noise.
Q: Is a high net worth statement enough to secure a loan?
A: Not always. Lenders care about liquidity and cash flow, not just paper wealth. A statement with $1M in illiquid assets (e.g., real estate) may still get rejected if monthly income doesn’t support debt. Focus on both net worth and income stability.
Q: Can I use my net worth statement for estate planning?
A: Absolutely. It’s the foundation of wills, trusts, and inheritance tax strategies. A clear statement helps executors distribute assets efficiently and minimizes family disputes over "missing" wealth.
Q: What’s the biggest mistake people make with their net worth statements?
A: Treating it as a one-time exercise. Net worth is a process, not a destination. The real value comes from tracking changes over time—spotting trends, adjusting strategies, and avoiding complacency.
