
The Complete Overview of Global Net Worth Percentiles
Global net worth percentiles are the financial equivalent of a weather map—showing where you stand in the storm of global inequality. Unlike gross income, which measures annual flow, net worth captures the accumulated power of assets minus liabilities. It’s not just about how much you earn but how much you’ve managed to retain, protect, and grow over time. The median global net worth in 2023 was estimated at around $82,000, but that figure masks vast disparities. In Switzerland, the median was over $200,000; in India, it dropped to $1,500. Your percentile isn’t just a personal stat—it’s a reflection of the economic ecosystem you were born into. The real value of understanding your global net worth percentile lies in its predictive power. Historically, percentiles have been used to identify trends before they become crises. For instance, the collapse of the dot-com bubble in 2000 was preceded by a sharp drop in the 90th+ percentile’s stock portfolios, while the 2008 financial crisis saw the bottom 60% of earners lose wealth at a rate 3x faster than the top 1%. Today, tools like the Credit Suisse Global Wealth Databook and Forbes Real-Time Billionaires List provide snapshots, but most individuals lack access to real-time percentile tracking. The gap between raw data and personal insight is where strategy begins—or fails.Historical Background and Evolution
The concept of wealth distribution percentiles emerged in the early 20th century as economists sought to quantify inequality beyond simple averages. Pioneers like Vilfredo Pareto observed that wealth followed a predictable 80/20 rule, where a small fraction of the population held disproportionate assets. His work laid the groundwork for modern percentile analysis, though early models were limited to national data. The post-WWII era saw the rise of cross-border wealth studies, accelerated by the creation of institutions like the World Bank and IMF, which began publishing comparative wealth reports in the 1980s. These early datasets revealed that while the U.S. and Western Europe had higher median net worths, emerging markets like South Korea and China were experiencing rapid percentile compression—meaning more people were moving into higher brackets faster than in mature economies. The digital revolution of the 1990s and 2000s transformed percentile tracking. The advent of big data allowed researchers to correlate net worth with factors like education, geography, and even social media activity. Platforms like Credit Suisse and McKinsey now use machine learning to adjust for inflation, currency fluctuations, and asset volatility, providing near-real-time percentile estimates. However, the democratization of data has also created challenges: wealth hoarding in tax havens, the rise of "paper wealth" in crypto, and the erosion of traditional asset classes (like real estate) in favor of intangible assets (like patents or digital IP) have forced percentile models to evolve. Today, a person’s global net worth percentile isn’t just about money—it’s about portfolio diversity in an era where borders are increasingly porous.Core Mechanisms: How It Works
At its core, calculating your global net worth percentile involves three steps: asset aggregation, liability deduction, and global benchmarking. Asset aggregation includes liquid assets (cash, stocks), illiquid assets (property, art), and intangible assets (pensions, intellectual property). Liabilities—mortgages, student loans, credit card debt—are subtracted to arrive at a net figure. This net worth is then compared against a global percentile distribution curve, which adjusts for purchasing power parity (PPP) to account for cost-of-living differences. For example, $1 million in Tokyo buys far less than $1 million in Warsaw, so percentile rankings are PPP-adjusted to reflect true economic standing. The mechanics behind percentile shifts are less about raw numbers and more about structural advantages. A software engineer in Berlin might see their percentile drop if they take on student debt, while a real estate investor in Lisbon could see theirs rise if property values surge. Tax policies, inheritance laws, and even cultural attitudes toward saving play a role. For instance, in countries like Singapore or Hong Kong, where wealth is passed down through multiple generations, the 99th percentile often includes families with intergenerational wealth pools—a factor absent in countries with weaker inheritance protections. The global net worth percentile isn’t static; it’s a dynamic reflection of how systems—both economic and social—shape individual outcomes.Key Benefits and Crucial Impact
Understanding your global net worth percentile isn’t just about vanity metrics—it’s about financial sovereignty. For high-net-worth individuals, it clarifies tax optimization strategies; for middle-class earners, it highlights where they might be falling behind. In 2022, a McKinsey study found that individuals in the 70th+ percentile were 40% more likely to achieve generational wealth transfer than those in the 50th. The percentile also acts as a risk indicator: those in the top 5% historically weathered recessions better due to diversified portfolios, while the bottom 30% often faced asset erosion. The impact isn’t just personal—it’s political. Countries with higher median net worth percentiles tend to have more stable democracies, while those with extreme wealth concentration face higher inequality-related unrest. The psychological weight of percentile awareness is often underestimated. A 2021 Harvard Business Review study found that individuals who knew their global net worth percentile were 22% more likely to engage in long-term financial planning, from retirement accounts to estate planning. The reason? Percentiles create a reference point—a way to measure progress against a global standard, not just local benchmarks. For example, a teacher in Finland might feel "rich" compared to peers but realize they’re in the 65th percentile globally—a wake-up call to invest in assets that appreciate beyond salary growth."Wealth is not about how much you have, but how much you can move without losing your percentile." — Nassim Nicholas Taleb, Antifragile
Major Advantages
- Tax optimization: Knowing your percentile helps identify offshore strategies, trust structures, or tax-efficient jurisdictions that align with global benchmarks.
- Investment alignment: High percentiles often correlate with access to private equity, hedge funds, or alternative assets like timber or wine—opportunities typically closed to lower brackets.
- Succession planning: Families in the 95th+ percentile can structure trusts or dynasty trusts to preserve wealth across generations, a luxury unavailable to those in lower percentiles.
- Geographic arbitrage: Percentile awareness reveals where your wealth is strongest (e.g., high in Switzerland, low in Brazil) and how to relocate or diversify accordingly.
- Philanthropic leverage: Ultra-high-net-worth individuals (top 0.1%) can use percentile data to maximize charitable impact through donor-advised funds or impact investing.
- Risk mitigation: Lower percentiles benefit from understanding how to protect against wealth erosion (e.g., inflation hedges, insurance structures) based on global trends.

Comparative Analysis
| Factor | Top 1% Global Net Worth Percentile | Median Global Net Worth Percentile |
|---|---|---|
| Asset Composition | 60% financial assets (stocks, bonds), 30% real estate, 10% alternatives (art, private equity) | 40% real estate, 30% financial assets, 30% liquid savings |
| Wealth Growth Rate | Annualized growth of 7-12% (diversified portfolios) | Annualized growth of 2-5% (salary-driven, less diversification) |
| Systemic Risks | Lower exposure to job loss; higher exposure to market volatility | Higher exposure to employment instability; lower exposure to asset bubbles |
Future Trends and Innovations
The next decade will see percentile tracking become personalized and predictive. Advances in AI are enabling real-time net worth monitoring, where algorithms adjust for cryptocurrency volatility, NFT valuations, and even social capital (e.g., the value of professional networks). Companies like Wealthfront and Betterment are already integrating percentile dashboards into their platforms, allowing users to see how their portfolio stacks up against global peers. The rise of decentralized finance (DeFi) may also reshape percentiles, as borderless assets like stablecoins and yield farming could create new wealth brackets outside traditional banking systems. Geopolitical shifts will further distort percentiles. The U.S.-China tech war, sanctions on Russia, and the eurozone’s debt crisis are already causing wealth to cluster in specific regions. For example, the 2022 devaluation of the ruble pushed Russian oligarchs into the global top 0.5% overnight, while Ukrainian refugees saw their percentiles plummet. Meanwhile, climate migration could create new percentile hotspots—imagine a future where coastal cities in Southeast Asia become wealth hubs as European assets depreciate. The global net worth percentile isn’t just a static snapshot; it’s a moving target shaped by forces beyond individual control.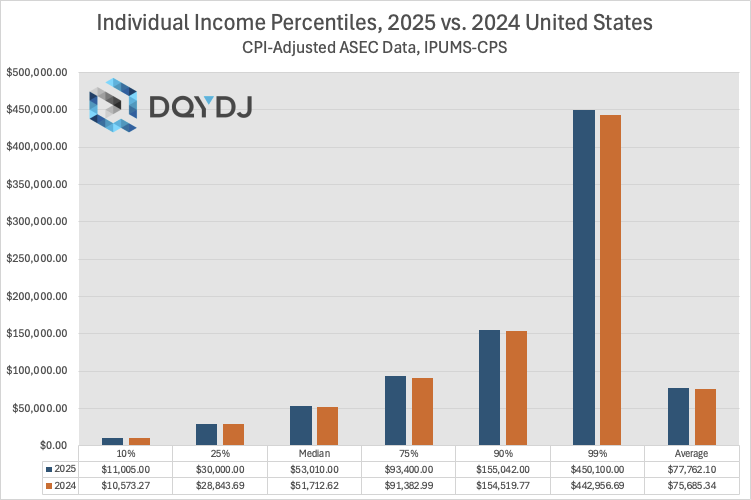
Conclusion
The global net worth percentile is more than a number—it’s a report card on the systems that shape your life. Whether you’re in the 10th percentile struggling with debt or the 99th percentile optimizing trusts, your percentile reflects the rules of the game. The key insight? Percentiles are malleable. A teacher in the 50th percentile can shift upward through real estate or side hustles; a corporate executive in the 95th can protect their standing by diversifying into emerging markets. The difference between stagnation and growth often comes down to awareness—and the willingness to play by rules that aren’t always fair. The future of percentile tracking will lie in democratization. As tools become more accessible, individuals will no longer rely on vague "middle-class" labels but on data-driven benchmarks. Governments may even use percentile thresholds to design policies—imagine a world where tax brackets adjust based on global percentile rankings, not just national averages. For now, the message is clear: your global net worth percentile isn’t just about how much you have. It’s about what you can do with it—and what the world will let you do.Comprehensive FAQs
Q: How often should I check my global net worth percentile?
Annual reviews are ideal, but quarterly checks are better for high-net-worth individuals due to market volatility. Use tools like Credit Suisse’s Global Wealth Databook or local financial platforms that offer percentile comparisons. Remember: percentiles shift with inflation, currency changes, and asset performance.
Q: Can my percentile change drastically in a short time?
Yes. A single event—a stock market crash, a real estate boom, or an inheritance—can move you 10-20 percentiles overnight. For example, the 2020 COVID-19 market dip saw the 90th percentile drop to the 80th for many investors, while those with diversified portfolios held steady. Percentile volatility is highest in emerging markets and lowest in stable economies like Switzerland or Singapore.
Q: Does my country’s currency affect my global percentile?
Absolutely. A strong currency (like the Swiss franc) inflates your percentile globally, while a weak one (like the Turkish lira) deflates it—even if your local net worth hasn’t changed. For instance, a Polish engineer earning $50,000 might be in the 70th percentile locally but the 40th globally due to currency conversion. Always use PPP-adjusted percentile tools for accuracy.
Q: Are there industries where percentiles grow faster than others?
Tech, healthcare, and alternative energy sectors historically see faster percentile growth due to high margins and asset appreciation. For example, a mid-level software engineer in the 60th percentile can reach the 90th in a decade through equity compensation. Traditional industries like manufacturing or retail see slower percentile progression unless they involve asset ownership (e.g., owning a franchise).
Q: How do I improve my percentile without increasing my income?
Leverage asset appreciation (real estate, stocks), debt optimization (refinancing high-interest loans), and tax-efficient structures (retirement accounts, trusts). For example, a nurse in the 50th percentile could boost their percentile by investing in index funds or buying a rental property—without a salary increase. The key is portfolio diversification and minimizing liabilities that drag down net worth.
Q: Can governments manipulate percentile rankings?
Indirectly, yes. Policies like capital gains taxes, inheritance laws, and property regulations directly impact percentiles. For instance, France’s wealth tax historically suppressed the top 1%’s percentile growth, while Singapore’s lack of inheritance taxes allowed wealth to compound faster. Even central bank policies (e.g., interest rates) can shift percentiles by making debt cheaper or more expensive.
Q: What’s the most underrated asset for percentile growth?
Intellectual property and digital assets (patents, royalties, SaaS businesses) are often overlooked but can skyrocket percentiles because they’re not tied to physical location or inflation. For example, a musician in the 30th percentile might reach the 80th through streaming royalties or a YouTube channel—without traditional wealth markers like a mansion or stock portfolio.
