Common Myths About Tracking Financial Progress
The first misconception is that net worth alone tells the whole story. It doesn’t. A tech executive with a seven-figure net worth might still face liquidity crises if their cash flow is erratic—think of the Silicon Valley founders who sold companies for billions but later struggled to pay salaries. Meanwhile, a teacher with modest assets but consistent monthly surpluses could retire decades earlier than the executive. What is the value of comparing monthly cash flow and net worth statements over time? It’s the difference between a static portrait and a motion picture of your finances. Another myth is that cash flow tracking is only for the self-employed or those with irregular incomes. That’s false. Even salaried professionals benefit from monitoring inflows and outflows because expenses don’t disappear when paychecks do. A corporate lawyer earning £200,000 annually might still face cash flow shocks from unexpected medical bills or a market downturn that triggers bonus deferrals. The overlap between cash flow and net worth—when analyzed together—exposes vulnerabilities before they become crises.Myth 1: "Net worth is the only metric that matters for long-term wealth"
Net worth is a lagging indicator, not a leading one. It reflects past decisions but doesn’t predict future stability. Consider the case of a real estate investor whose portfolio value (net worth) surged during a housing boom. On paper, they looked wealthy. But if their rental income barely covered mortgage payments—and they relied on refinancing to cover living expenses—their cash flow was negative. When the market corrected, they faced foreclosure despite a high net worth. What is the value of comparing monthly cash flow and net worth statements over time? It’s the early warning system that net worth alone cannot provide. The data backs this up. A 2022 study by the Federal Reserve found that households with volatile cash flow—even those with high net worth—were three times more likely to experience financial distress within five years. Net worth doesn’t account for liquidity risk, and liquidity is what keeps you afloat during downturns. Tracking both metrics forces you to ask: Is my wealth accessible, or is it an illusion?Myth 2: "Cash flow tracking is just for budgeting—it doesn’t affect net worth"
This separates form from function. Cash flow is the engine; net worth is the destination. If you spend more than you earn month after month, your net worth will eventually stagnate or decline, regardless of market conditions. The reverse is also true: disciplined cash flow—even with modest income—can compound into significant net worth over time. Historian Niall Ferguson’s research on wealth accumulation shows that consistent savings rates (a cash flow discipline) explain more of the wealth gap than investment returns alone. The confusion arises because people treat cash flow as a short-term exercise. But when you compare monthly cash flow and net worth statements over time, you see how small leaks—like unused subscriptions or impulse purchases—erode long-term growth. A £5 daily coffee habit might seem trivial, but over a decade, it costs £9,125 in lost savings. That’s not just a budgeting issue; it’s a net worth destroyer.Myth 3: "I don’t need to track this if I’m young or early in my career"
This is the most dangerous myth of all. Early-career professionals often assume they have time to "figure it out later." But financial habits form in these years, and the compounding effect of cash flow discipline is exponential. A 2023 Bank of America report found that individuals who tracked both cash flow and net worth in their 20s and 30s built net worth 40% faster than those who started later, even with similar starting salaries. The reason? Small monthly surpluses, when reinvested, outpace the impact of later-life windfalls. The flip side is equally true: early-career cash flow mismanagement—like relying on credit cards to cover lifestyle inflation—can create liabilities that take decades to overcome. What is the value of comparing monthly cash flow and net worth statements over time? For young professionals, it’s the foundation for avoiding the "wealth illusion," where people feel rich because their home value rises but are actually drowning in debt.
What Holds Up to Scrutiny
The evidence is clear: the most financially resilient individuals don’t rely on one metric. They treat cash flow and net worth as complementary lenses. Cash flow reveals operational health—how well you manage the day-to-day. Net worth reveals strategic health—how your assets and liabilities align with long-term goals. When you compare monthly cash flow and net worth statements over time, you get a dynamic view of your financial ecosystem. Take the example of a mid-career professional who switches from renting to buying a home. Their net worth might dip initially due to closing costs and property taxes, but their cash flow improves if mortgage payments are lower than rent. Over three years, their net worth recovers—and their cash flow provides a buffer against unexpected expenses. Without tracking both, they might misinterpret the dip as failure rather than a calculated trade-off."Net worth is a photograph; cash flow is the film. One shows where you’ve been. The other shows where you’re headed—and whether you’ll get there." — Morgan Housel, The Psychology of Money
| Common Belief | What the Evidence Says |
|---|---|
| "Net worth is enough to plan for retirement." | Retirement planning requires cash flow projections. A high net worth doesn’t guarantee sustainable withdrawals—especially if assets are illiquid (e.g., a business or real estate). |
| "Cash flow tracking is only for people with irregular incomes." | Even salaried employees face cash flow risks (e.g., medical bills, job transitions). Tracking prevents lifestyle creep from eroding net worth. |
| "My net worth is growing, so I don’t need to monitor cash flow." | Growing net worth with negative cash flow signals debt dependency. Historically, households with this pattern face higher default rates during economic downturns. |
| "I’ll start tracking later when I have more money." | Early tracking compounds advantages. A £200 monthly surplus at 25, invested at 7% annually, grows to ~£450,000 by 65. The same surplus starting at 40 yields ~£120,000. |
Why the Confusion Persists
Two factors dominate: cultural conditioning and tool limitations. Most financial education focuses on net worth—assets, investments, and "get rich" narratives—while cash flow is treated as a secondary concern. This mirrors how society glorifies wealth symbols (homes, cars) over financial discipline. Meanwhile, personal finance tools often silo the two. Mint tracks cash flow but lacks deep net worth insights; Wealthfront shows net worth but ignores monthly flows. The result? Users treat them as separate puzzles instead of a system. The other issue is behavioral bias. People prefer the simplicity of a net worth number because it feels like progress. But cash flow is uncomfortable—it exposes spending habits and forces accountability. The discomfort leads to avoidance, even though the data proves that comparing monthly cash flow and net worth statements over time is the only way to spot inefficiencies before they become crises.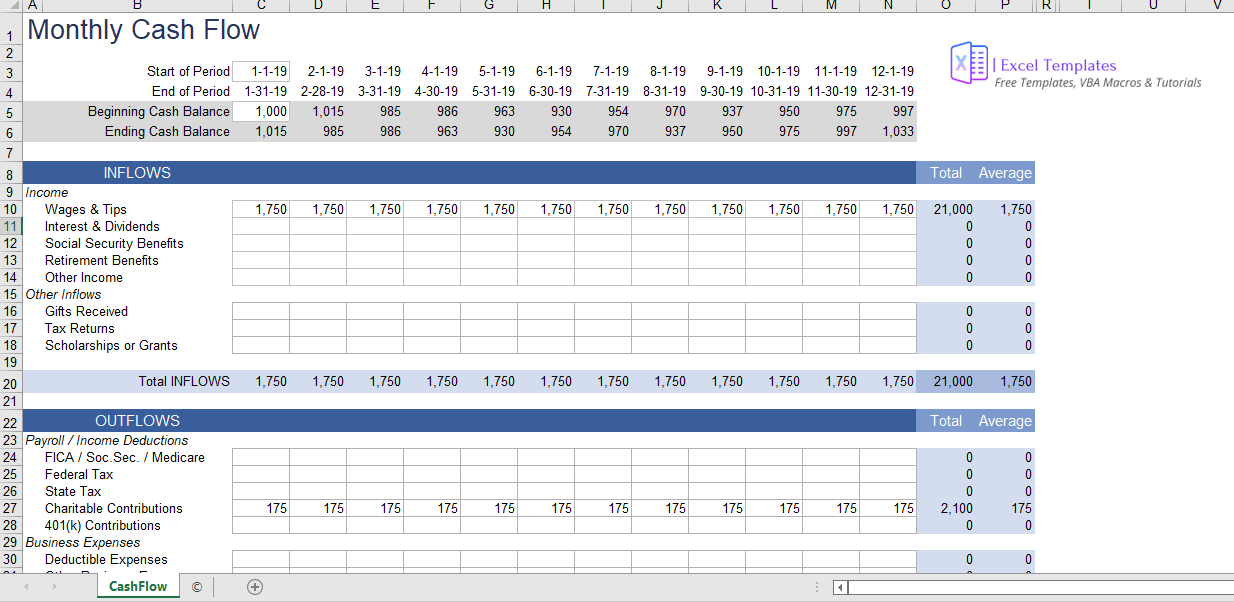
Conclusion
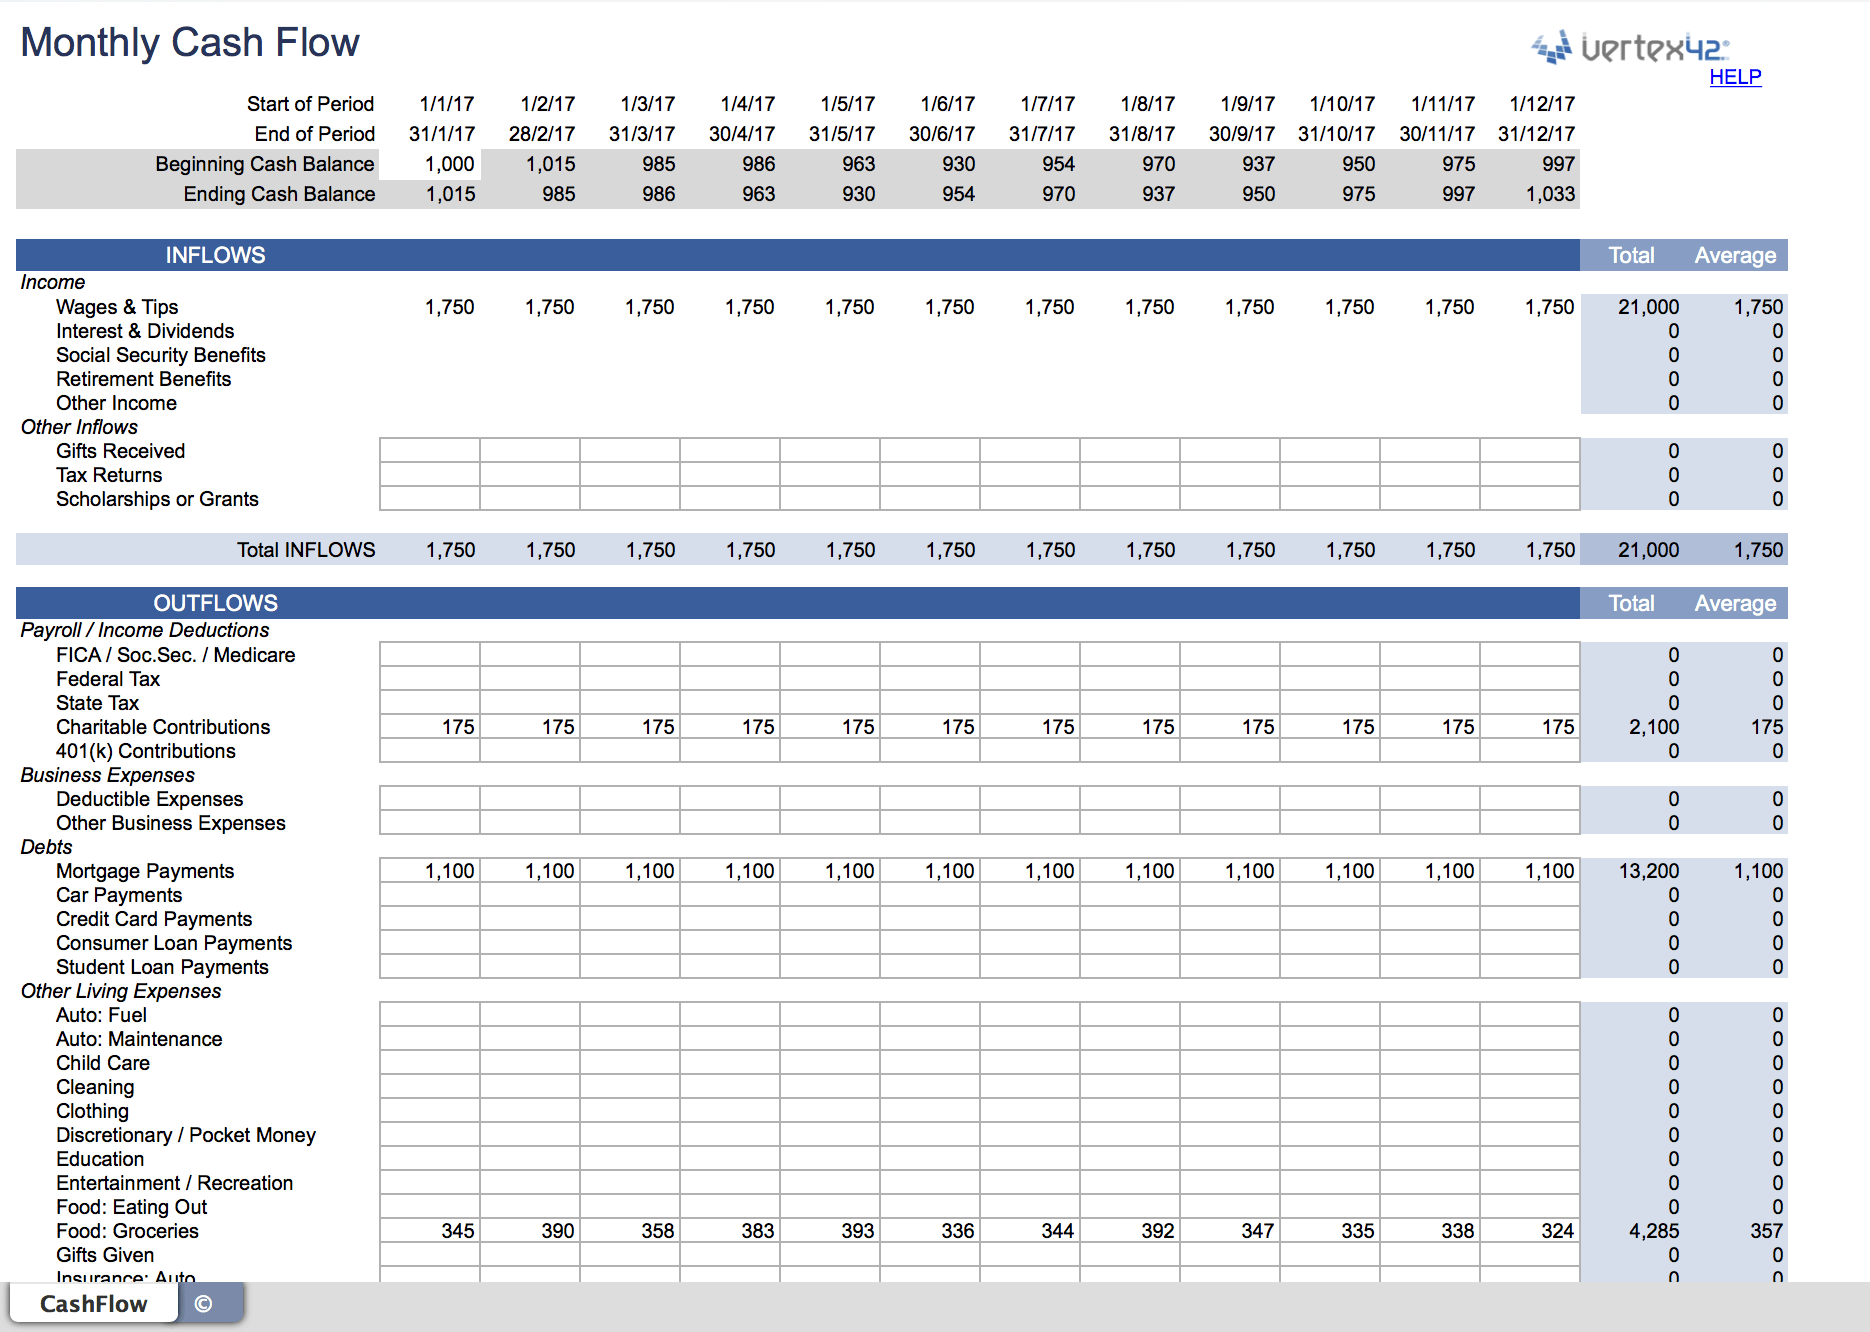
The value of what is the value of comparing monthly cash flow and net worth statements over time isn’t just analytical—it’s psychological. It shifts your relationship with money from reactive to intentional. You stop asking, "How much do I have?" and start asking, "How am I using what I have?" The distinction matters. A high net worth with poor cash flow is like a race car with no fuel—impressive on paper, but useless when it counts. For most people, the insight comes not from the numbers themselves but from the gaps between them. A widening gap between cash flow and net worth might reveal overleveraging. A shrinking gap could signal frugality paying off. The key is consistency. Track both monthly, not annually. Use tools that integrate them—like YNAB for cash flow and Personal Capital for net worth—or build your own spreadsheet. The goal isn’t perfection; it’s visibility. And visibility is the first step toward control.Comprehensive FAQs
Q: How often should I compare my cash flow and net worth statements?
Monthly is ideal, but the minimum is quarterly. Monthly tracking catches leaks early; quarterly works if you have stable income but want to reduce overhead. The critical factor is consistency—not frequency alone. What matters is spotting trends over time, not chasing daily fluctuations.
Q: Can I rely on bank statements alone, or do I need specialized tools?
Bank statements show transactions but don’t categorize them for cash flow analysis. Tools like Mint, YNAB, or Tiller automate categorization, while spreadsheets (Google Sheets/Excel) offer customization. For net worth, platforms like Personal Capital or Wealthfront pull investment data automatically. The trade-off? Tools save time but may lack flexibility. A hybrid approach—bank statements for raw data, tools for analysis—often works best.
Q: What’s the biggest mistake people make when tracking these metrics?
Ignoring liquidity. Many focus on net worth growth without ensuring assets are accessible. For example, a high net worth tied to a business or illiquid investments might look strong on paper but fail during a crisis. The mistake isn’t tracking cash flow—it’s treating it as a side note while prioritizing net worth. What is the value of comparing monthly cash flow and net worth statements over time? It forces you to ask: Can I use my wealth when I need it?
Q: How do I explain the importance of this to someone who’s skeptical?
Use the "stress test" analogy: Imagine your net worth is a dam, and cash flow is the water behind it. A high dam (net worth) with cracks (poor cash flow) will fail when pressure rises. The skeptic might argue, "I’ll be fine." But history shows that 90% of financial distress isn’t caused by low net worth—it’s caused by cash flow mismanagement. Start with a simple exercise: Compare their last three months of cash flow to their net worth change. The disconnect will speak louder than any lecture.
Q: Are there industries or professions where this comparison is more critical?
Yes. Self-employed professionals (freelancers, consultants) rely heavily on cash flow because income varies. Real estate investors must balance cash flow from rentals against net worth tied to property values. Public sector workers (teachers, government employees) often face predictable cash flow but need to monitor net worth growth against inflation. Even in stable corporate jobs, bonus-dependent earners (sales, finance) benefit from tracking how irregular income affects both metrics. The rule? The more volatile your income or assets, the more critical the comparison.
