Common Myths About Tracking Financial Trends
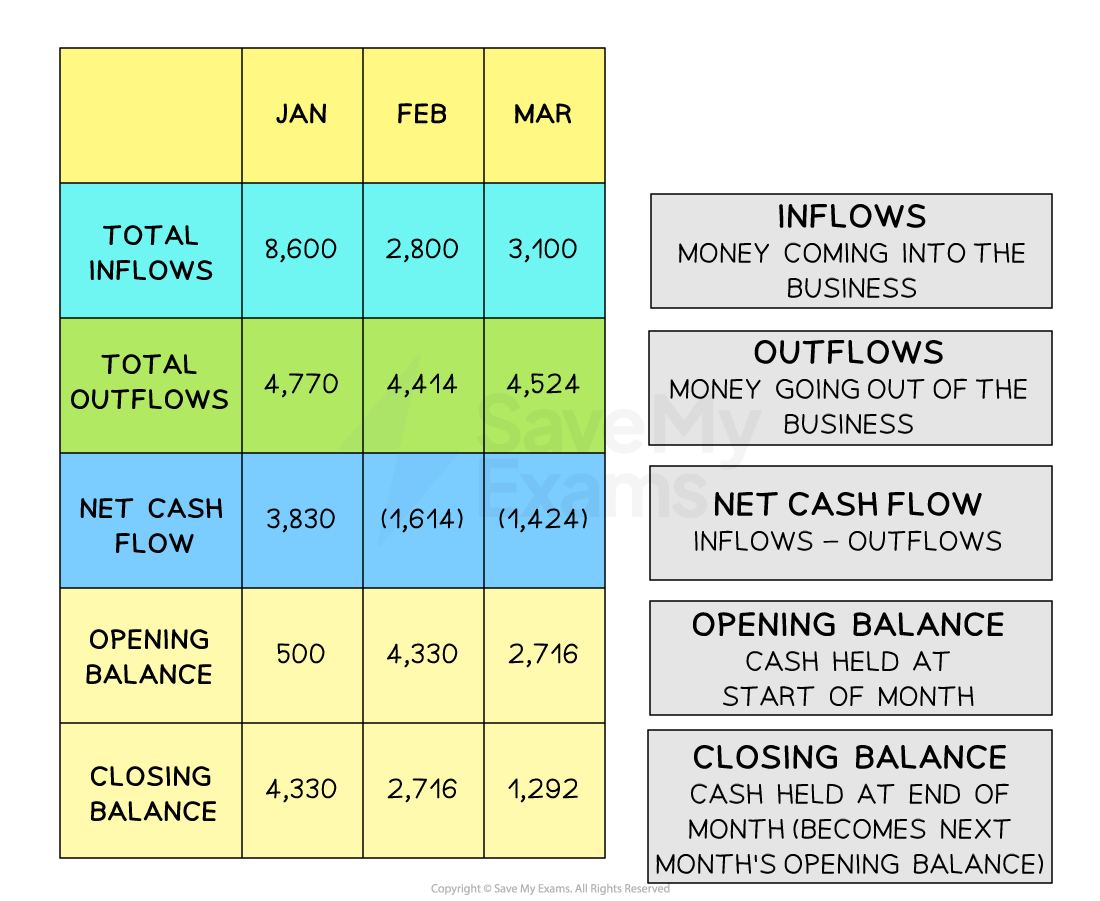
The first misconception is that net worth alone tells the full story. Many assume if their assets exceed liabilities by a healthy margin, their finances are sound. But net worth is a lagging indicator—it reflects past decisions, not current flexibility. Cash flow, meanwhile, is leading. A person could have a net worth of £500,000 yet face liquidity crises because their income is tied to illiquid assets. Comparing monthly cash flow and net worth statements over time forces you to confront this disconnect. Another persistent myth is that tracking both metrics requires advanced accounting skills. In reality, most personal finance software automates the heavy lifting. The challenge isn’t data collection; it’s interpretation. People overlook how seasonal expenses, one-time investments, or market volatility distort short-term trends. Without a long-term lens, those distortions create false narratives—like assuming a single month of high spending means a lifestyle you can’t sustain.Myth 1: "If my net worth is rising, I don’t need to track cash flow."
This ignores the fact that net worth growth can be an illusion. Consider someone who sells a £200,000 property, takes a £150,000 mortgage against it, and pockets £50,000 in cash. Their net worth jumps by £50,000—but their cash flow just became precarious. Without monthly tracking, they might not realize their liquidity buffer has evaporated until a crisis hits. The benefit of comparing monthly cash flow and net worth statements over time is that it surfaces these hidden trade-offs before they become disasters. Even in stable markets, cash flow dictates what net worth can do. A high net worth means little if you can’t access the capital. Tracking both reveals whether your asset growth is sustainable or just a temporary spike. For example, a freelancer’s net worth might rise when they land a big project—but if that project drains their cash reserves for six months, their long-term flexibility suffers.Myth 2: "Cash flow is more important than net worth."
This oversimplifies the relationship between the two. Cash flow without net worth growth is like a river with no delta—it flows but doesn’t build. Conversely, net worth without cash flow is a castle with no moat. The truth is that evaluating how cash flow impacts net worth over time is what separates financial health from mere survival. Take two scenarios: A salary earner with £80,000 in savings but £10,000 in monthly expenses might appear stable, but if their income drops, they’re just months from depletion. Meanwhile, a business owner with £300,000 in assets but erratic cash flow could face insolvency despite the higher net worth. The key isn’t prioritizing one over the other; it’s understanding how they interact dynamically.Myth 3: "I don’t need to track this until I’m close to retirement."
This is the most dangerous myth of all. By the time someone reaches retirement age, the damage from ignored trends is often irreversible. The advantage of comparing monthly cash flow and net worth statements over time is that it lets you adjust before small leaks become floods. A 25-year-old with a £5,000 annual subscription habit might not think it matters—until that habit delays homeownership by a decade. Early tracking also reveals structural issues. For instance, someone in their 30s might notice that while their net worth grows steadily, their cash flow never improves because they keep upgrading lifestyles with raises. Without intervention, this habit erodes their ability to weather downturns. The earlier you spot these patterns, the more you can redirect them toward compounding assets.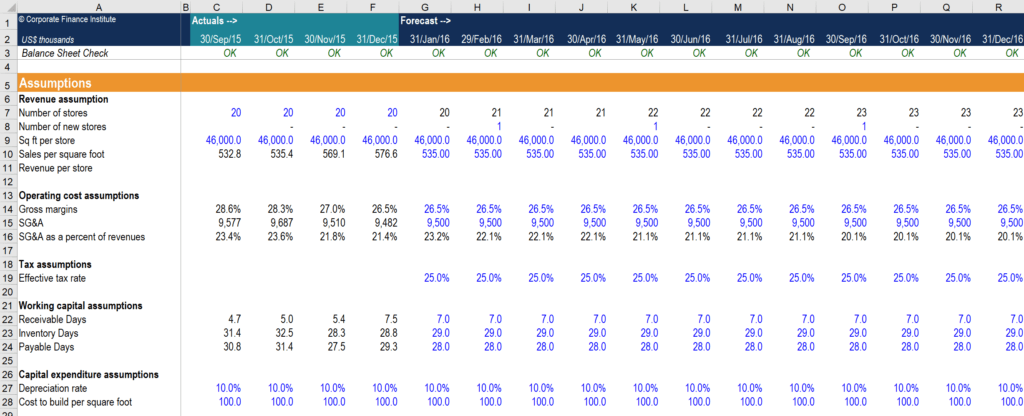
What Holds Up to Scrutiny
The core principle is simple: Cash flow is the engine; net worth is the destination. But the journey isn’t linear. A single month’s surplus doesn’t guarantee progress, just as a single month’s deficit doesn’t doom you. What matters is the trend—how these two metrics move in relation to each other over years, not weeks. The evidence supports this approach. Studies on high-net-worth individuals consistently show that those who track both metrics regularly adjust spending, reinvestment, and risk-taking more effectively. They’re not just reacting to numbers; they’re anticipating how cash flow will affect net worth in six months or six years. This isn’t theoretical. It’s observable in how families preserve wealth across generations."Wealth isn’t about what you own; it’s about what you can do with what you own when you need to." — Financial historian Niall Ferguson
| Common Belief | What the Evidence Says |
|---|---|
| "Net worth is the only metric that matters." | Net worth alone can’t predict liquidity crises. A 2022 study by the Federal Reserve found that 40% of households with high net worth faced cash flow shortages within five years. |
| "Cash flow is just about budgeting." | Cash flow analysis reveals systemic issues—like how tax liabilities or asset illiquidity distort spending power. The average high-earner loses 15–20% of income to non-discretionary cash drains. |
| "Tracking this is only for the wealthy." | Even modest incomes benefit. A 2023 survey of middle-class families showed those tracking both metrics had 30% higher savings rates after three years. |
Why the Confusion Persists
Part of the problem is cultural. Financial education often treats cash flow and net worth as separate topics—one for "daily money" and the other for "big-picture wealth." This compartmentalization ignores how they’re interconnected. Another factor is the allure of quick fixes. People prefer to focus on a single metric (like net worth) because it feels like a tangible achievement, even if it’s misleading. The tools don’t help either. Many budgeting apps prioritize expense tracking over asset-liability analysis, reinforcing the myth that cash flow is an end in itself. Without a system that forces the comparison, users miss the forest for the trees. The result? A generation that’s financially literate in fragments but clueless about the big picture.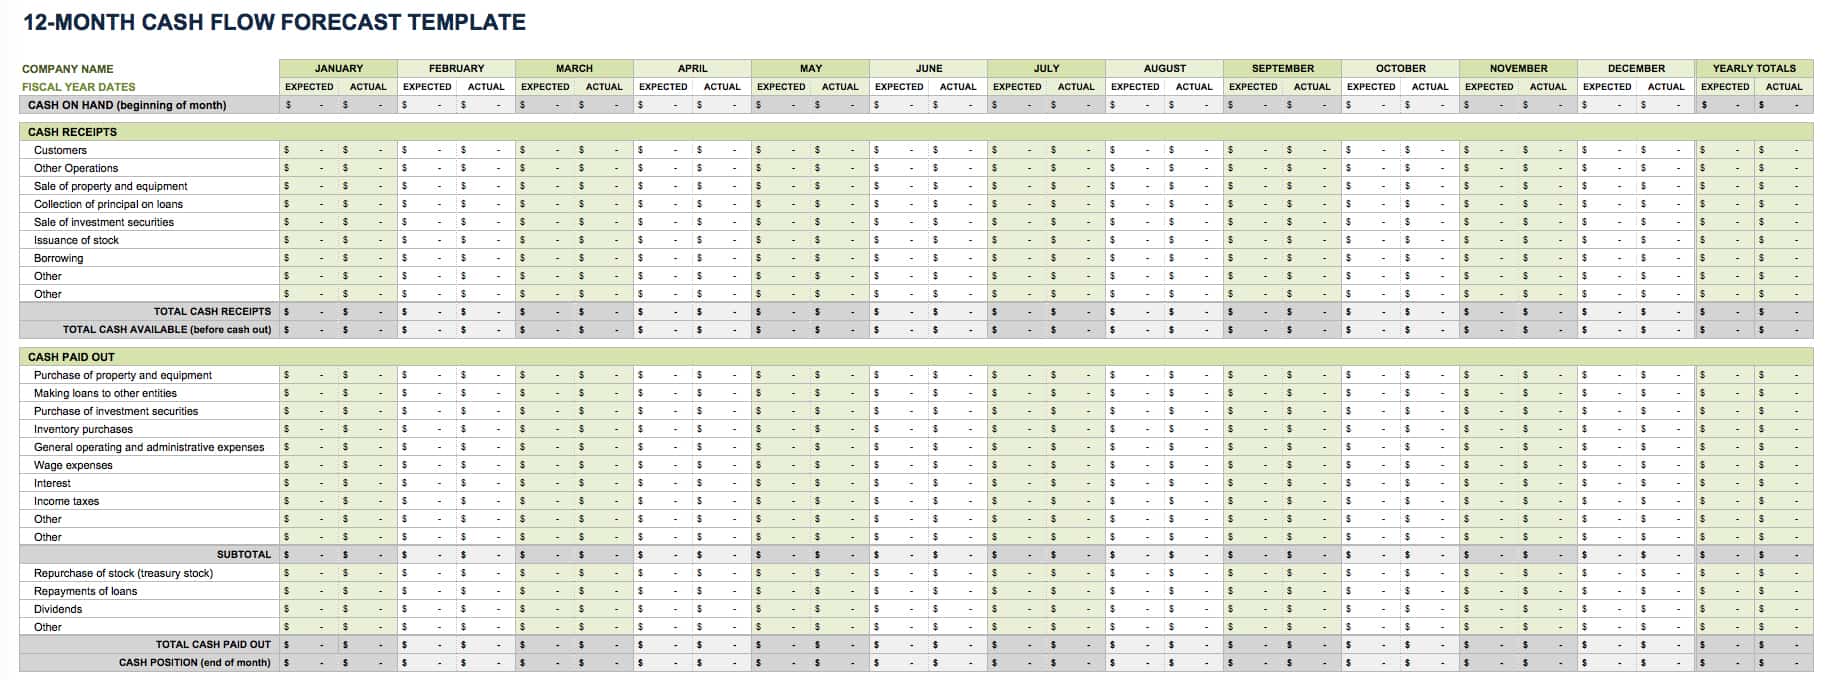
Conclusion
The most valuable financial habit isn’t tracking one metric—it’s seeing how monthly cash flow and net worth statements interact over time. This isn’t about chasing perfection; it’s about spotting anomalies before they become crises. A single month’s dip in cash flow might seem harmless, but if net worth hasn’t grown to offset it, that dip could signal a leak. Conversely, a spike in net worth without improved cash flow might mean you’re trading liquidity for paper gains. The real insight comes from the patterns. Over time, you’ll notice how certain expenses correlate with asset growth, how debt cycles align with income seasons, and how external shocks (like market drops or job changes) affect both metrics. This isn’t just data—it’s a financial autobiography. And like any good story, the most revealing parts aren’t the high points. They’re the quiet moments where trends shift, unnoticed until it’s too late.Comprehensive FAQs
Q: How often should I compare these statements?
A: Monthly is ideal, but the critical threshold is consistency. If you only review them quarterly, you’ll miss short-term trends—like seasonal spending spikes or one-off investments that distort the picture. The goal is to catch deviations early, so frequency matters more than rigid schedules.
Q: Can I do this manually, or do I need software?
A: Manual tracking works, but it’s error-prone. Spreadsheets can handle the math, but most people underestimate the time required to reconcile transactions, categorize expenses, and project trends. Dedicated tools (like YNAB, Personal Capital, or even free options like Google Sheets templates) automate the heavy lifting and highlight anomalies you’d miss otherwise.
Q: What if my cash flow is volatile but my net worth is stable?
A: This is common in early-stage businesses or freelance careers. The key is to assess whether the volatility is cyclical (e.g., seasonal work) or structural (e.g., unreliable clients). If it’s cyclical, build a buffer during high-cash-flow periods. If it’s structural, you may need to diversify income streams or adjust expenses to match long-term net worth growth.
Q: Does tracking these metrics guarantee financial success?
A: No system guarantees success, but this method dramatically improves your odds. It forces you to confront reality—like realizing you’re spending savings instead of investing them, or that your "safe" assets are actually illiquid. The difference between failure and success often comes down to spotting these truths early enough to act.
Q: How do I handle irregular income (e.g., bonuses, side hustles)?
A: Irregular income requires a two-part approach. First, categorize it separately in your cash flow statements to avoid blending it with steady income. Second, allocate a portion of irregular windfalls to either debt reduction or investments that align with your net worth goals. The rule of thumb: Treat unexpected income as if it’s part of your baseline, but with a higher savings rate.
Q: What’s the biggest mistake people make when comparing these?
A: Ignoring the why behind the numbers. A drop in net worth might seem alarming, but if it’s due to a deliberate reinvestment (like buying a rental property), it’s strategic. Conversely, a rise in cash flow without net worth growth could mean you’re just deferring expenses. Always ask: Is this trend temporary or structural? The answer changes everything.
Q: Can this method help with debt management?
A: Absolutely. By comparing cash flow to net worth, you’ll see how debt servicing affects your liquidity and asset growth. For example, a mortgage might increase net worth over time, but if your cash flow is stretched thin, you’re trading future flexibility for today’s stability. The method helps you decide whether debt is a tool or a trap.
