
6 Things Worth Knowing About the Largest Candy Companies
The dominance of the leading confectionery firms isn’t accidental. It’s the result of decades of calculated moves: buying competitors before they innovate, locking in supply chains, and turning sugar into a strategic commodity. These six insights explain how they maintain their grip—and why their influence extends far beyond the checkout line.1. Mars Wrigley’s Vertical Empire
Mars Wrigley, the world’s largest candy maker by revenue, operates what amounts to a self-sustaining ecosystem. The company controls everything from cocoa bean sourcing to retail shelf placement, reducing reliance on volatile commodity markets. Its 2018 acquisition of Wrigley—creating Mars Wrigley—consolidated gum and chocolate under one roof, giving it unmatched leverage in both categories. The move also eliminated a direct competitor, a playbook repeated across the industry as major candy conglomerates swallow up niche players to stifle innovation. What’s less discussed is how Mars Wrigley’s supply chain extends into agricultural diplomacy. The company has faced criticism for its cocoa sourcing practices in West Africa, where child labor persists despite corporate pledges. Yet its scale allows it to push for industry-wide reforms—even as it profits from the system. The tension between ethical pressure and profit margins defines modern confectionery’s moral calculus.2. Hershey’s U.S. Fortress
While Mars Wrigley dominates globally, Hershey holds an unassailable position in North America, controlling nearly 40% of the U.S. chocolate market. Its strength stems from two pillars: brand loyalty (Reese’s, Kit Kat U.S. rights) and aggressive cost-cutting. Hershey’s 2018 decision to shut down its Lancaster, PA, plant—laying off 500 workers—sparked backlash, but the move slashed production costs by 20%. The company’s ability to weather such controversies underscores its strategic ruthlessness. Hershey’s also exemplifies how regional dominance can stifle competition. Smaller U.S. chocolatiers struggle to gain shelf space, while Hershey’s private-label deals with retailers like Walmart further tighten its grip. The result? A market where innovation often means incremental tweaks to existing formulas rather than bold new flavors.3. The Monopoly Problem
The top five candy companies—Mars Wrigley, Hershey, Mondelez (Cadbury, Milka), Ferrero (Nutella, Ferrero Rocher), and Lindt—account for over 70% of global confectionery sales. This concentration raises antitrust concerns, yet regulators rarely intervene. Why? Because these firms operate across borders, making jurisdiction complex. The EU’s 2021 probe into Ferrero’s market dominance in Italy—accusing it of abusing its position to block smaller competitors—shows how geopolitical fragmentation protects them. Industry insiders argue that without consolidation, smaller brands would struggle to compete with the R&D budgets of global candy giants. Yet the lack of competition also means fewer choices for consumers. The trade-off between efficiency and diversity is a defining feature of today’s confectionery landscape.4. Innovation: The Illusion of Choice
Consumers perceive candy innovation as a cornucopia of new flavors, but much of it is incremental repackaging. Take Mondelez’s acquisition of Halls cough drops in 2017—a move that expanded its presence in health-focused confections. Or Ferrero’s 2020 launch of "Ferrero Rocher Caramel," a variation on a classic. These tweaks keep brands relevant without disrupting supply chains."Innovation in candy isn’t about breakthroughs—it’s about extending the lifecycle of existing products. A new flavor of M&M’s might seem revolutionary, but it’s just a way to keep the same machinery running." — Former Mondelez R&D executive, speaking off-record to Confectionery NewsThe real innovation happens behind the scenes: predictive analytics to forecast flavor trends, or partnerships with tech firms to develop "smart candy" (like Hershey’s lab-grown chocolate experiments). Yet for consumers, the perception of novelty often outweighs actual change.
5. Sugar’s Dark Supply Chain
The largest candy companies rely on sugar—a commodity tied to deforestation, water shortages, and labor exploitation. Mars Wrigley sources sugar from Brazil, where land grabs for cane fields have displaced indigenous communities. Ferrero, meanwhile, has faced lawsuits over child labor in its cocoa supply chain, despite pledges to certify 100% of its beans by 2025. The industry’s response? Voluntary sustainability initiatives that critics call toothless. Hershey’s "Hershey’s Cocoa for Good" program, for example, has improved some farms but done little to address systemic issues. The result is a paradox: consumers demand ethical candy, but the market rewards scale over ethics.6. The Lobbying Machine
Candy isn’t just sold—it’s politically engineered. The National Confectioners Association, representing giants like Mars and Hershey, spends millions lobbying against sugar taxes, food labeling laws, and even health warnings on chocolate. In 2019, the group successfully blocked a California bill that would’ve required warning labels on sugary foods, arguing it would "stigmatize" candy. This influence extends globally. Ferrero lobbied against Italy’s proposed sugar tax, while Mondelez fought EU plans to cap sugar in children’s products. The message is clear: regulations threaten profits more than public health.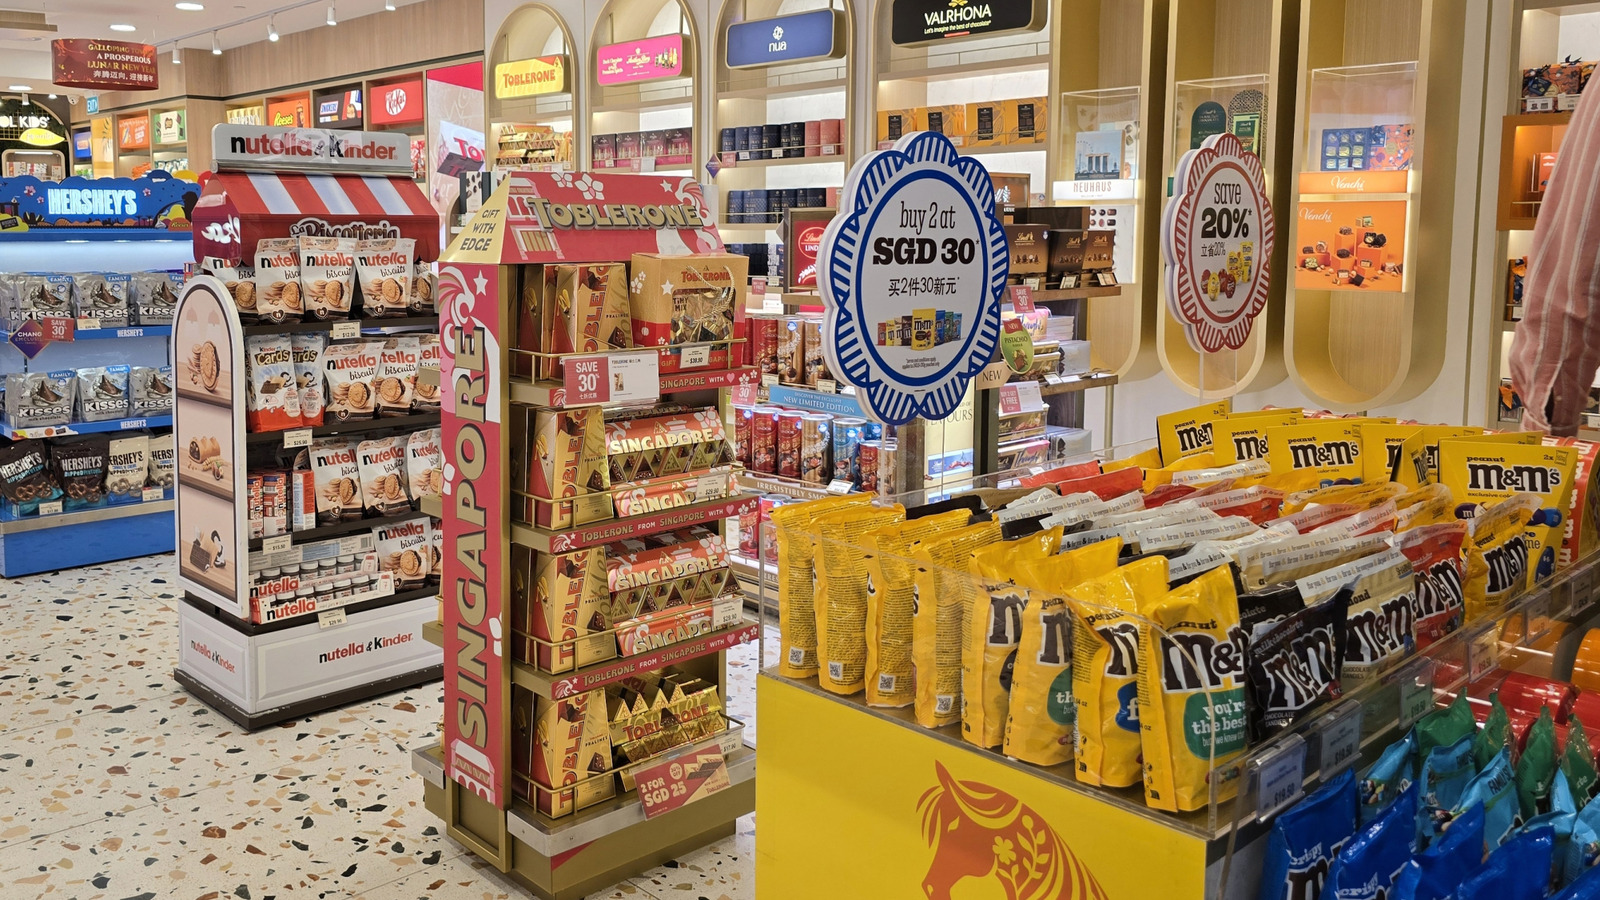
How These Facts Connect
The largest candy companies operate as both economic engines and cultural arbiters. Their vertical integration ensures supply chain control, while mergers eliminate competition before it emerges. Yet this consolidation comes at a cost: fewer choices, ethical compromises, and a market where innovation is often a smokescreen for stagnation. What’s striking is how these firms balance public perception with corporate interests. They fund childhood obesity research while selling sugary snacks, and they promise sustainability while relying on exploitative supply chains. The disconnect isn’t accidental—it’s a feature of their business model. The table below contrasts their public image with their operational realities:| Company | Public Image | Operational Reality |
|---|---|---|
| Mars Wrigley | Family-friendly, innovative | Vertical control, child labor risks in cocoa |
| Hershey | American icon, community-focused | Aggressive cost-cutting, U.S. market monopoly |
| Ferrero | Luxury confectionery, ethical sourcing | Lobbying against sugar taxes, supply chain controversies |
| Mondelez | Global leader, health-conscious options | Acquisition-driven growth, incremental "innovation" |
Conclusion
The largest candy companies are more than purveyors of sweetness; they’re architects of modern consumption. Their strategies—consolidation, lobbying, and supply chain dominance—reveal an industry where ethics often yield to efficiency. Yet their cultural footprint remains undeniable. From Halloween to Valentine’s Day, their products are woven into rituals that define generations. The challenge lies in holding them accountable without stifling the creativity of smaller brands. As consumers grow more health-conscious, the global candy titans face a dilemma: double down on their business model or risk becoming relics of a less scrutinized era. One thing is certain—their influence won’t wane without pressure from regulators, investors, and shoppers who refuse to ignore the cost of their confections.Comprehensive FAQs
Q: Which company is the largest candy maker by revenue?
A: Mars Wrigley, formed by the 2018 merger of Mars and Wrigley, consistently ranks as the world’s largest candy company by revenue, though exact figures vary by year. Its global reach—spanning chocolate, gum, and pet treats—gives it an edge over regional players like Hershey.
Q: How do the largest candy companies influence sugar policies?
A: Through lobbying groups like the National Confectioners Association, these firms spend millions opposing sugar taxes, food labeling laws, and health warnings. Their political clout often trumps public health concerns, as seen in blocked legislation in the U.S. and EU.
Q: Are there any ethical alternatives to mainstream candy?
A: Yes, but they’re niche. Brands like Tony’s Chocolonely (which funds fair-trade cocoa) or Divvies (a U.S. company using upcycled ingredients) offer alternatives. However, their market share remains tiny compared to global candy giants, which benefit from economies of scale.
Q: How do mergers affect candy innovation?
A: Mergers often reduce competition rather than spur innovation. When Mars acquired Wrigley, for example, it eliminated a direct competitor, leaving fewer players to invest in R&D. Most "innovation" post-merger is incremental—new flavors or packaging—rather than breakthrough products.
Q: What’s the biggest controversy facing the largest candy companies today?
A: Supply chain ethics, particularly child labor in cocoa farming and environmental damage from sugar production, dominate criticism. While companies like Hershey and Ferrero have launched sustainability programs, critics argue they’re insufficient to address systemic issues.
Q: Can smaller candy brands compete with the largest players?
A: It’s extremely difficult but not impossible. Smaller brands often succeed by focusing on niche markets (e.g., organic, vegan, or regional specialties) or leveraging direct-to-consumer sales. However, they face supply chain disadvantages and limited retail shelf space controlled by the major candy conglomerates.
